I’ve Built 3 Multimillion-Dollar Businesses — and Here’s My Simple Secret to Success
Opinions expressed by Entrepreneur contributors are their own.

When I started out, the goal was pretty straightforward: Make lots of money. Like most new entrepreneurs, I figured once I’d “made it,” then I’d give back. That part would come later. Success first, impact second.

Looking back, I now realize that mentality was a massive mistake. In fact, I believe it was one of the fundamental reasons it took me years to find any success. I now realize that pushing purpose to the back burner might be the thing that stalls your growth even more than poor marketing.

Everything turned around for me when I stopped “chasing paper” and started asking how I could help. When that shift happened, my business started to thrive in ways I never expected. And the money? It followed, as a side effect. It’s a fact that we all know deep down, but too often forget.

We’re told that giving back is something you earn the right to do once your company is big, your team is built, and your bank account looks a certain way. But the reality is that purpose isn’t a luxury; it’s a growth strategy. This attitude of abundance needs to be something that you embody both internally and externally as well.

Related: How to Balance Profits With Purpose at Your Business

The first focus needs to be on how you approach your day-to-day operations. At BotBuilders, our work centers around AI and automation. But that’s not really what drives us. The deeper mission is helping small business owners believe in what they’re building and giving them tools to actually pull it off.

The more we’ve invested in our clients’ success, the more we’ve seen our own business expand. Not just in revenue, but in reach, loyalty and community. Real relationships have carried us further than any marketing tactic ever could. It’s not something you can track or budget for, but we’ve all experienced how one relationship can lead to exponential growth, on many levels.

The second way to have an impact is how your company shows outside of your core competency. Namely, in your community. How often do you and your team get out and serve those who need it most? Money is great, but there is no comparison to the difference that a smile can make.

One of the biggest culture-shaping moments we’ve ever had started in the most unexpected place: a bowling alley in Arizona. Working with Special Olympics Arizona, we put together the Bowl-A-Thon Bash. The annual event pairs athletes with local business owners for high-fives, gutter balls, and a whole lot of laughter.

At first, it felt like a one-off community event. But after that night, something shifted. It became tradition. And every year we go back it resets something in us. We leave lighter, clearer, and more in tune with what really matters. That one night has done more to anchor our company values than any vision statement ever could.

Don’t get me wrong, money is important. I’m not dismissing that. But if we’re talking about real impact? Giving your time and actually showing up, things just hit different. Over the years, our team has done all kinds of small things that ended up being huge. We’ve served meals at shelters. We’ve planted trees. We’ve hosted holiday parties in retirement homes just to bring some joy to folks who don’t get many visitors.

Related: This CEO Says Prioritizing Purpose Over Profit Is Key to Consistent Growth and Sustainable Profit — Here’s Why.

None of that was fancy. None of it was scalable or “optimized.” But the growth those moments sparked? You could feel it. In how we communicated, how we worked together and how we showed up on Monday mornings. When we work together to do good for others, we are connected on a level much deeper than winning awards or even with traditional team-building activities.

So if you’re leading a team, never forget the fact that your values are contagious. Culture doesn’t come from the posters on your wall or the perks in your handbook. It’s built in the quiet choices. It shows up in how you respond when no one’s watching. It’s shaped by what you say “yes” to, and what you’re willing to let slide. As my angel-of-a-mother always says, “never miss a chance to help someone out.”

When you lead with meaning, people notice. They step up. And the ripple effects extend way beyond your team. So don’t wait for the perfect opportunity. You don’t need a giant audience, a massive checkbook or a five-year plan to make an impact. You just need to care enough to begin. You’ll be amazed by what comes of it on every level of your organization.

Pick something simple. Volunteer for a day, and invite your team into the process. Whatever you do, it doesn’t have to be perfect; it just has to be real. Because when your business stands for something more, people stand with you. And that is when things really start to grow.

When I started out, the goal was pretty straightforward: Make lots of money. Like most new entrepreneurs, I figured once I’d “made it,” then I’d give back. That part would come later. Success first, impact second.

Looking back, I now realize that mentality was a massive mistake. In fact, I believe it was one of the fundamental reasons it took me years to find any success. I now realize that pushing purpose to the back burner might be the thing that stalls your growth even more than poor marketing.

Everything turned around for me when I stopped “chasing paper” and started asking how I could help. When that shift happened, my business started to thrive in ways I never expected. And the money? It followed, as a side effect. It’s a fact that we all know deep down, but too often forget.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/growing-a-business/ive-built-3-multimillion-dollar-businesses-and-heres/494881



Use Rosetta Stone to Impress Clients Around the World with Fluent, Natural Speech

Disclosure: Our goal is to feature products and services that we think you’ll find interesting and useful. If you purchase them, Entrepreneur may get a small share of the revenue from the sale from our commerce partners.

When your career takes you across borders, being able to speak the local language isn’t just helpful — it’s a competitive edge. Rosetta Stone’s immersive language platform has been trusted for 27 years by organizations such as NASA and TripAdvisor, and it’s now available to new users as a lifetime subscription for just $148.97 with code FLUENT until September 7.

With access to 25 languages — including Spanish, Mandarin, French, German, Arabic, and Japanese — you’ll be equipped for nearly any global business opportunity. Rosetta Stone’s intuitive training method mimics how we learned our first language, helping you absorb vocabulary, structure, and pronunciation naturally. The platform’s speech-recognition technology analyzes your accent in real time, offering instant feedback.

Progressive lessons start with practical conversations such as ordering food, giving directions, or talking through a meeting, and advance to more nuanced discussions like negotiating, giving feedback, and navigating cultural topics. Whether you’re prepping for an overseas project, building international client relationships, or managing a global team, this tool is designed to keep you sharp and culturally competent.

This deal is for new users only, and you’ll need to activate it within 30 days of purchase. Once you do, you’ll have lifetime access on desktop and mobile with no monthly fees, and you can switch between languages whenever you want.

Secure your edge in global business with lifetime Rosetta Stone access for $148.97 through September 7 by entering promo code FLUENT at checkout.

StackSocial prices subject to change.

When your career takes you across borders, being able to speak the local language isn’t just helpful — it’s a competitive edge. Rosetta Stone’s immersive language platform has been trusted for 27 years by organizations such as NASA and TripAdvisor, and it’s now available to new users as a lifetime subscription for just $148.97 with code FLUENT until September 7.

With access to 25 languages — including Spanish, Mandarin, French, German, Arabic, and Japanese — you’ll be equipped for nearly any global business opportunity. Rosetta Stone’s intuitive training method mimics how we learned our first language, helping you absorb vocabulary, structure, and pronunciation naturally. The platform’s speech-recognition technology analyzes your accent in real time, offering instant feedback.

Progressive lessons start with practical conversations such as ordering food, giving directions, or talking through a meeting, and advance to more nuanced discussions like negotiating, giving feedback, and navigating cultural topics. Whether you’re prepping for an overseas project, building international client relationships, or managing a global team, this tool is designed to keep you sharp and culturally competent.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/living/use-rosetta-stone-to-impress-clients-around-the-world-with/496377


The New Number 1 AI Agent to Build a Profitable One-Person Business That Runs While You Sleep

Opinions expressed by Entrepreneur contributors are their own.

Most entrepreneurs are still stuck treating AI like a writing assistant — pumping out blog posts, captions or emails and hoping it moves the needle. But OpenAI’s latest update just changed the game.

This isn’t another “AI tool.” It’s ChatGPT’s new Agent — a fully autonomous virtual worker that can predict trends, reverse-engineer your competitors and even scan your Instagram for untapped revenue hiding in forgotten DMs.

In this video, you’ll see exactly how solopreneurs are using it to run profitable one-person businesses on autopilot — replacing tasks that once took entire teams.

Here’s what you’ll discover:

  • Viral trend prediction: How this Agent spots breakout topics before they hit the mainstream — helping you publish first and ride the wave.
  • Competitor edge: A real-time playbook that reveals where your competitors are weak — and hands you the exact moves to outrank them.
  • Free PR on demand: How the Agent finds podcasts, researches hosts and drafts custom pitches that actually get you booked.
  • Revenue recovery: The hidden sales buried in your inbox and social DMs — and how this Agent brings them back to life.

The bottom line: this isn’t about saving time. It’s about building a business that grows without burning you out — one that works even when you’re not online.

The AI Success Kit is available to download for free, along with a chapter from my new book, The Wolf is at The Door.

Most entrepreneurs are still stuck treating AI like a writing assistant — pumping out blog posts, captions or emails and hoping it moves the needle. But OpenAI’s latest update just changed the game.

This isn’t another “AI tool.” It’s ChatGPT’s new Agent — a fully autonomous virtual worker that can predict trends, reverse-engineer your competitors and even scan your Instagram for untapped revenue hiding in forgotten DMs.

In this video, you’ll see exactly how solopreneurs are using it to run profitable one-person businesses on autopilot — replacing tasks that once took entire teams.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/science-technology/the-new-1-ai-agent-to-build-a-profitable-one-person/496485


The ‘Topgolf’ of Surfing Is a $65 Billion Opportunity

Disclosure: Our goal is to feature products and services that we think you’ll find interesting and useful. If you purchase them, Entrepreneur may get a small share of the revenue from the sale from our commerce partners.

When world champions and proven leaders unite, investors pay attention.

As the former President of Topgolf, Troy Warfield helped transform golf from an exclusive pastime into a global entertainment empire worth billions. That’s why there’s arguably no better CEO to help Surf Lakes bring surfing to the 99% with their patented 360° wave technology.

Since most people don’t live near a beach, surf parks are a $65B market opportunity on the rise. And Surf Lakes is positioning itself as a global leader in the space. World surfing champions Tom Curren and Mark “Occy” Occhilupo are even joining as shareholders and ambassadors.

But the real opportunity is not just in the parks. Here’s how Surf Lakes is redefining the sport, and how you can share in their potential growth.

Millions of people want to surf, but 99% aren’t near a beach

Despite having an estimated 25 million to 35 million participants worldwide, surfing is still mostly limited to the coasts. Less than 1% of the global population lives near surfable waves. For everyone else, the ocean might as well be off-limits.

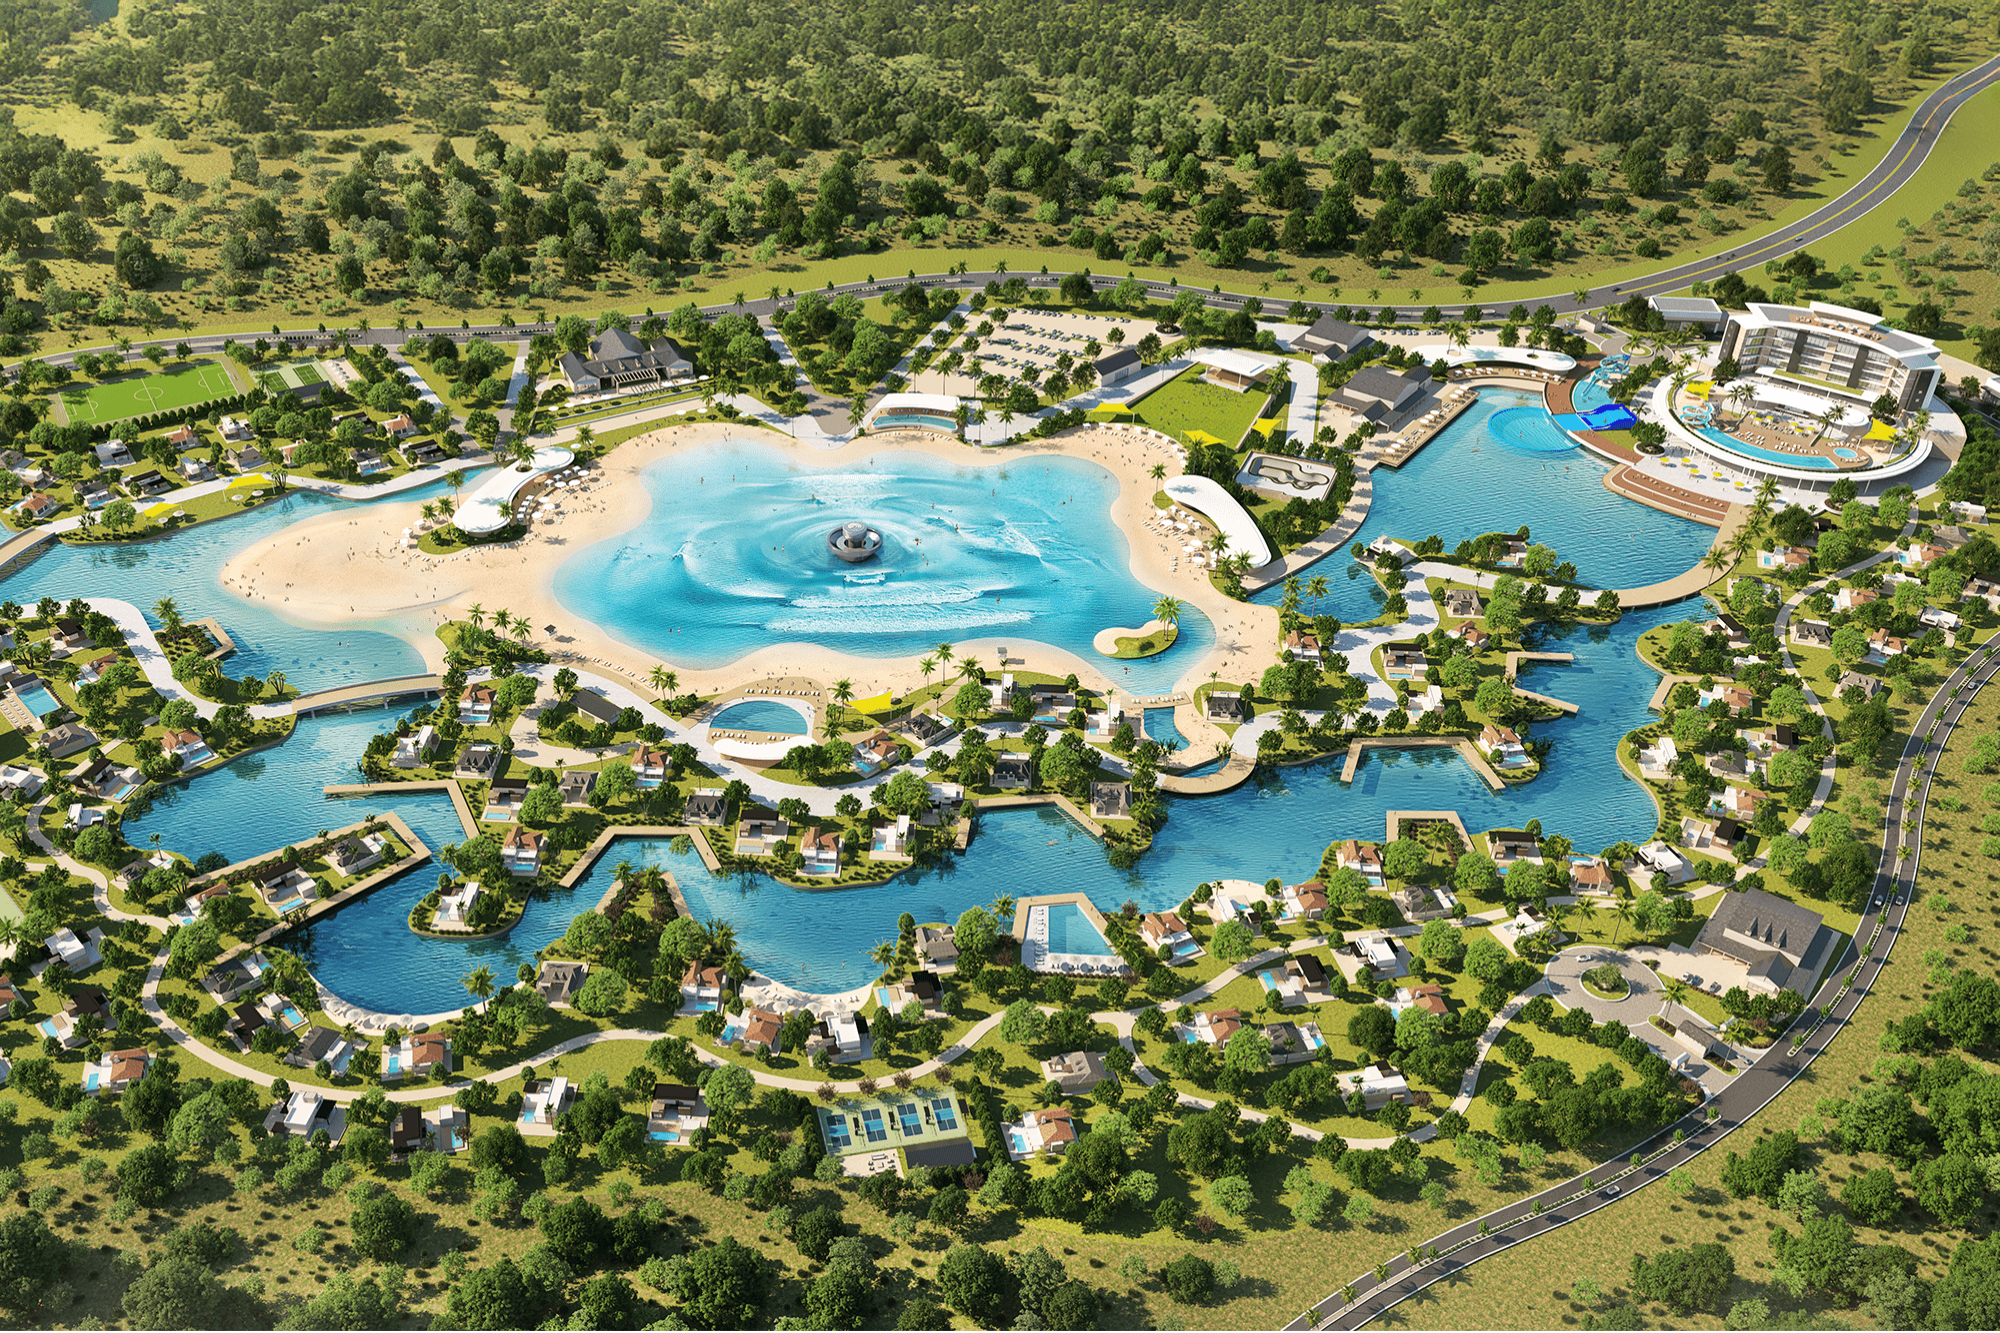
Surf Lakes solves that problem. Their tech produces 2,000 ocean-quality rides per hour across five skill levels, from beginners catching their first roller to pros training in barreling waves. The tech opens a huge opportunity in the surf park market.

Surfing is growing in popularity as we speak. The sport is now a permanent Olympic event, with 47 million viewers tuning in to the Paris 2024 competition in Brazil alone. Surf parks nearly doubled worldwide in 2024, as developers scramble to meet surging demand.

For perspective:

  • 6,000+ ski resorts exist worldwide
  • 38,000+ golf courses are operating
  • 410M+ in global theme park attendance

Surf Lakes believes that the number of surf parks worldwide will reach the hundreds very quickly.

Multiple ways to profit from surfing

The Surf Lakes model isn’t just about ticket sales. Their wave tech opens the door to licensing fees and royalties from global partners, memberships and day passes for recurring revenue, competitions, training programs, food, beverage, retail, and more.

Each new park creates multiple, scalable income streams, just like Topgolf did with memberships, events, and hospitality.

Surf Lakes has already sold nine tech licenses across the U.S. and Australia. Their first full-scale commercial park is in the works. With industry legends and proven leadership behind them, they’re positioned as the technology provider of choice in a market just hitting critical mass.

Here’s how investors can be a part of it.

Get in at the start of Surf Lakes’ next chapter

For investors, Surf Lakes represents a unique chance to get in ahead of what could be the next global entertainment boom. With patented technology, their first park in the works, and licensing traction accelerating, this company has the potential to dominate.

That’s why surfing legends and proven business leaders are coming aboard. A-list celebrities are even chiming in—Chris Hemsworth, Hollywood actor and avid surfer, called Surf Lakes an “incredibly surreal experience.”

The brand is already global. This is an opportunity for investors to join at a pivotal moment before their expansion. Learn more and invest in Surf Lakes by 9/12 to get up to 15% bonus shares.

This is a paid advertisement for Surf Lakes’ Regulation CF offering. Please read the offering circular at https://invest.surflakes.com

When world champions and proven leaders unite, investors pay attention.

As the former President of Topgolf, Troy Warfield helped transform golf from an exclusive pastime into a global entertainment empire worth billions. That’s why there’s arguably no better CEO to help Surf Lakes bring surfing to the 99% with their patented 360° wave technology.

Since most people don’t live near a beach, surf parks are a $65B market opportunity on the rise. And Surf Lakes is positioning itself as a global leader in the space. World surfing champions Tom Curren and Mark “Occy” Occhilupo are even joining as shareholders and ambassadors.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/money-finance/the-topgolf-of-surfing-is-a-65-billion-opportunity/496494


Lessons from Macmillan’s CEO on Leading Through Change Without Losing Your Why

Opinions expressed by Entrepreneur contributors are their own.

As someone who regularly speaks with CEOs about their industries, paths and philosophies, my conversation with Jon Yaged, CEO of Macmillan, stood out. It wasn’t just about books or publishing — it was about values, culture and the role of business leaders in a time of social friction.

What surprised me wasn’t Jon’s passion for literature — that was expected — but how candidly he spoke about the challenges Macmillan faces in a world where books are being banned.

Book banning may sound like a relic, but as Jon explained, it’s a growing issue. Schools and libraries across the country are under pressure to remove books that address race, gender and identity. For Macmillan, one of the “Big Five” U.S. publishers, this isn’t just a sales issue — it’s cultural and political. Jon made it clear: their role isn’t to publish what’s comfortable, but what’s important. And that comes with risk, especially when distributors, schools or local governments push back.

Related: 7 Ways Entrepreneurs Can Sharpen Their Leadership Skills and Drive Business Growth

We also discussed what it means to be a CEO amid cultural pushback. Jon doesn’t take a performative approach. He doesn’t try to be loud or overly polished about Macmillan’s values. Instead, he focuses on listening, standing firm and partnering with those who share their mission. That kind of clarity stood out. Leadership isn’t always about fighting loud battles — sometimes it’s about quietly protecting space for discourse, with conviction.

Our conversation turned to AI and its impact on publishing. Jon’s view was pragmatic: use AI to streamline operations, improve accessibility and support editors — not replace them. He wasn’t overly optimistic or alarmist — he simply saw AI as a tool that needs thoughtful handling. For an industry often seen as traditional, Macmillan appears forward-looking — without losing its editorial soul.

There’s something here for leaders in any industry. Jon is navigating a company at the intersection of culture, politics and innovation. He’s not leading with fear or distraction — he’s leading with clarity. What’s the mission? Who are we serving? Where can we evolve without compromising our principles? Those are questions worth asking, whether you’re in publishing or running a tech startup.

What I took from this interview was a deeper understanding of how leadership and culture intersect. Jon Yaged isn’t trying to make a spectacle of Macmillan’s stance — he’s working to keep the lights on for writers and stories that matter. And in a time when polarization and noise dominate, that quiet resolve made a lasting impression.

As someone who regularly speaks with CEOs about their industries, paths and philosophies, my conversation with Jon Yaged, CEO of Macmillan, stood out. It wasn’t just about books or publishing — it was about values, culture and the role of business leaders in a time of social friction.

What surprised me wasn’t Jon’s passion for literature — that was expected — but how candidly he spoke about the challenges Macmillan faces in a world where books are being banned.

Book banning may sound like a relic, but as Jon explained, it’s a growing issue. Schools and libraries across the country are under pressure to remove books that address race, gender and identity. For Macmillan, one of the “Big Five” U.S. publishers, this isn’t just a sales issue — it’s cultural and political. Jon made it clear: their role isn’t to publish what’s comfortable, but what’s important. And that comes with risk, especially when distributors, schools or local governments push back.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/leadership/lessons-from-macmillans-ceo-on-leading-through-change/496307


Domain Costs Can Spiral — Take These Steps to Stay in Control and Save Thousands

Opinions expressed by Entrepreneur contributors are their own.

The right domain is essential in 2025 and beyond. Brands need that perfect web address to establish credibility and attract traffic. In practice, domain brokerage firms act as intermediaries between buyers and sellers, often negotiating opaque fees that can increase the final costs.

Join me as I reveal the reality of domain brokers, highlighting common fees and negotiation strategies that help keep budgets under control. Fellow entrepreneurs will learn what questions to ask when hiring a broker, which hidden costs to watch for and how to challenge price tags. Ultimately, I’ll demonstrate how to prepare for acquiring high-value domains without overspending.

What is a domain brokerage?

Domain brokers serve as intermediaries in negotiating the purchase of premium web addresses. They utilize private marketplaces, proprietary networks and historical sales data to discover domains that might not show up on public auction sites.

  • Brokers often provide expertise in valuing domain assets, advising on trademark risks and handling escrow services.
  • Firms tend to charge a mix of retainer fees, flat rates or commissions on successful deals.

Brands relying on brokers expect quicker access to top-tier domains with professional negotiation, but they often face confusing bills with multiple line items. Entrepreneurs who understand what they’re signing up for avoid sticker shock at closing.

Related: 5 Unforgettable Lessons I Learned Spending $1 Million on a Domain Name

Typical fees found in domain brokerage deals

Most brokers quote a base commission but also add extra charges, such as appraisal fees, which can range from $200 to $1,000. Escrow services typically cost between $75 and $150 per transaction. Legal reviews of trademark and contract language often add a few hundred dollars at a minimum. Premium placement on listing sites involves either monthly or one-time marketing fees.

Be aware that some brokers inflate domain renewal fees or charge administrative fees for international transfers. Companies that don’t review fee schedules beforehand risk paying three times the domain’s market value after all charges are applied.

How hidden costs balloon your bill

An entrepreneur seeking a three-letter .com domain may plan to spend $10,000, including a 15% broker commission.

  • This is where the broker finds the domain and negotiates a seller price of $9,000. A commission of $1,350 seems reasonable.
  • Adding a $500 appraisal fee, $100 escrow fee, $300 legal review charge and a $1,000 premium listing fee increases the total to $11,950.
  • Domain renewal costs of $200 and transfer fees of $150 push the total closer to $12,300.

In the end, unexpected fees turn a $10,000 budget into a $12,300 expense.

Vetting brokers without overspending

Brands should request potential brokers to provide a detailed fee schedule that outlines both upfront and contingent charges. Essential questions to ask include whether appraisals or escrow services are included in the commission, what happens if the deal falls through and who is responsible for legal costs.

Successful brokers share case studies, transparent pricing and sample invoices. Brands can compare flat-fee firms with percentage-based brokers. Flat-fee brokers typically charge between $2,500 and $5,000 regardless of domain price, making them appealing for high-value domain targets. Percentage-based brokers are generally better suited for budget-conscious acquisitions, where commissions remain reasonable and affordable.

What to look for in a domain name broker for businesses

Track record matters. Brands should seek brokers with proven experience in securing domains within their industry niche and review broker performance portfolios. Positive client testimonials and case studies demonstrate success rates and average savings.

Having strong escrow partnerships ensures secure funds transfer. Expert negotiators know how to approach domain owners without spooking them into holding out for inflated offers. Transparent communication frameworks keep brands informed throughout every step.

Related: A Great Domain Name Can Add Millions to Your Business — Here’s How to Get One (Even If It’s Already Taken)

Negotiation tactics that cut costs

Arming yourself with market comparables and past sale prices levels the playing field. Brokers should provide historical sales data demonstrating that similar domains have sold for lower prices. Silent offers submitted without disclosing maximum budgets prevent anchoring at high figures.

Creative deal structures, such as deferred payment agreements or equity components, incentivize sellers to accept fairer terms. Knowing when to walk away helps prevent price wars from spiraling out of control. A well-timed pause in negotiations can encourage sellers to accept reasonable offers instead of losing the deal.

When to walk away from overpriced domains

Red flags include sellers who demand all-cash upfront, substantial price hikes during the escrow period or refusal to share domain history records. Brokers should set clear acceptable price ranges and focus on domains that match value expectations.

If a broker encourages brands to exceed their budget, it signals potential misalignment. Walking away from a domain now prevents draining funds and allows redirecting resources to other options.

Persistence pays off, especially if brokers scout multiple candidates instead of fixating on a single prized address.

Balancing time versus money

DIY methods require substantial effort in researching WHOIS records, monitoring expiry dates and drafting outreach emails. Hybrid models cut down time commitments to negotiation stages only.

The good news is that full-service brokers completely relieve brands of administrative tasks, but they often charge high fees. Brands comparing options should evaluate the value of internal hours against broker costs to find the optimal balance.

Best practices for smooth domain transfers

Once a price point is agreed upon, escrow holds the funds until the ownership transfer is completed successfully. Brokers should coordinate with registrars to update WHOIS records and verify the domain status.

Brands need to confirm transfer lock statuses and obtain authorization codes. Multi-step verification ensures trademarks transfer smoothly without legal issues. A seamless transfer prevents downtime and maintains SEO authority.

Auditing current domain acquisition strategies

Brands already using brokers should review past invoices by comparing estimated fees with actual charges. Analyzing negotiation results helps identify broker performance trends and possible overcharges.

Regular audits can uncover hidden recurring fees, allowing for renegotiation of fee structures or broker replacement. Consistent reviews help keep costs under control over time.

Owning your domain purchases with smart strategies

Understanding how this process and the associated fees work can help you reduce costs. Negotiate costs upfront, walk away if prices skyrocket and combine DIY tools with broker support to secure domains at fair rates.

Audit your current approach, match acquisition methods to your resources and demand transparent pricing from any broker you hire. Balance time versus money, explore hybrid options and conduct a fee audit before you buy.

This way, you can secure a great domain name for your business that feels predictable, affordable, and perfectly aligned with your brand goals.

The right domain is essential in 2025 and beyond. Brands need that perfect web address to establish credibility and attract traffic. In practice, domain brokerage firms act as intermediaries between buyers and sellers, often negotiating opaque fees that can increase the final costs.

Join me as I reveal the reality of domain brokers, highlighting common fees and negotiation strategies that help keep budgets under control. Fellow entrepreneurs will learn what questions to ask when hiring a broker, which hidden costs to watch for and how to challenge price tags. Ultimately, I’ll demonstrate how to prepare for acquiring high-value domains without overspending.

What is a domain brokerage?

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/growing-a-business/domain-costs-can-spiral-take-these-steps-to-stay-in/494770


He Went From Delivering Pizza As a Side Hustle to Owning 270 Pizza Shops. Here’s How He Did It: ‘[At First] It Was Chaos’

In a little over three decades, Nadeem Bajwa went from being a college student struggling to pay the bills to the owner of a fast food empire, owning 270 Papa John’s locations in North America.

The 58-year-old told CNBC that he immigrated to the U.S. in 1991 from Pakistan. He attended a college in Fort Wayne, Indiana, and worked side hustles to make ends meet. One of his side jobs was delivering pizza for a local Papa John’s chain, making $4.25 an hour. His first summer in the U.S., he would wash dishes during breakfast time, deliver pizzas for Papa John’s in the afternoon, and then work at Taco Bell at night.

“I just started delivering for Papa John’s when they came in town, and from there, just started loving it, and tips were good, so that helped,” Bajwa told CNBC.

Related: Want to Start a Business? This Franchise Will Give You Up to $100,000 to Do It.

When Bajwa graduated from college in 1996, he had already worked his way up the ranks at Papa John’s, going from delivery driver to area manager. He submitted applications to corporate roles at other companies, but found that he couldn’t get a job that would pay more than what he was making at Papa John’s. He decided to stick with the pizza shop for that reason.

Bajwa’s experience running a Papa John’s store helped when he eventually decided to become a franchisee and open his own location. In 2002, he opened his own Papa John’s restaurant in East Liverpool, Ohio, saving money on startup expenses by doing most of the labor himself.

The store took $150,000 to build out and was an instant success, with more customers showing up than expected. However, the crew was undertrained and overwhelmed, and half of them walked out that first day alone.

“[At first] it was chaos,” Bajwa told CNBC. “I learned how important it is to be ready before [opening].”

Related: This Entrepreneur Turned a Weekend Side Hustle Into a Business That Doubled Margins — And Is on Track for $7 Million

That one restaurant led to another, then another. Bajwa’s goal now is to open 500 Papa John’s locations in the coming years.

Papa John’s, which was founded in 1985, has over 3,000 locations in the U.S. It usually takes an initial investment of at least $272,915 to get a Papa John’s restaurant off the ground.

In a little over three decades, Nadeem Bajwa went from being a college student struggling to pay the bills to the owner of a fast food empire, owning 270 Papa John’s locations in North America.

The 58-year-old told CNBC that he immigrated to the U.S. in 1991 from Pakistan. He attended a college in Fort Wayne, Indiana, and worked side hustles to make ends meet. One of his side jobs was delivering pizza for a local Papa John’s chain, making $4.25 an hour. His first summer in the U.S., he would wash dishes during breakfast time, deliver pizzas for Papa John’s in the afternoon, and then work at Taco Bell at night.

“I just started delivering for Papa John’s when they came in town, and from there, just started loving it, and tips were good, so that helped,” Bajwa told CNBC.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/business-news/he-started-delivering-pizza-in-1991-and-now-owns-270-shops/496534


Scammers Can Deepfake Your CEO in Just 3 Minutes for $15 — Here’s How to Stop Them

Opinions expressed by Entrepreneur contributors are their own.

In 2024, a scammer used deepfake audio and video to impersonate Ferrari CEO Benedetto Vigna and attempted to authorize a wire transfer, reportedly tied to an acquisition. Ferrari never confirmed the amount, which rumors placed in the millions of euros.

The scheme failed when an executive assistant stopped it by asking a security question only the real CEO could answer.

This isn’t sci-fi. Deepfakes have jumped from political misinformation to corporate fraud. Ferrari foiled this one — but other companies haven’t been so lucky.

Executive deepfake attacks are no longer rare outliers. They’re strategic, scalable and surging. If your company hasn’t faced one yet, odds are it’s only a matter of time.

Related: Hackers Targeted a $12 Billion Cybersecurity Company With a Deepfake of Its CEO. Here’s Why Small Details Made It Unsuccessful.

How AI empowers imposters

You need less than three minutes of a CEO’s public video — and under $15 worth of software — to make a convincing deepfake.

With just a short YouTube clip, AI software can recreate a person’s face and voice in real time. No studio. No Hollywood budget. Just a laptop and someone ready to use it.

In Q1  2025, deepfake fraud cost an estimated $200 million globally, according to Resemble AI’s Q1 2025 Deepfake Incident Report. These are not pranks — they’re targeted heists hitting C‑suite wallets.

The biggest liability isn’t technical infrastructure; it’s trust.

Why the C‑suite is a prime target

Executives make easy targets because:

  • They share earnings calls, webinars and LinkedIn videos that feed training data

  • Their words carry weight — teams obey with little pushback

  • They approve big payments fast, often without red flags

In a Deloitte poll from May 2024, 26% of execs said someone had tried a deepfake scam on their financial data in the past year.

Behind the scenes, these attacks often begin with stolen credentials harvested from malware infections. One criminal group develops the malware, another scours leaks for promising targets — company names, exec titles and email patterns.

Multivector engagement follows: text, email, social media chats — building familiarity and trust before a live video or voice deepfake seals the deal. The final stage? A faked order from the top and a wire transfer to nowhere.

Common attack tactics

Voice cloning:

In 2024, the U.S. saw over 845,000 imposter scams, according to data from the Federal Trade Commission. This shows that seconds of audio can make a convincing clone.

Attackers hide by using encrypted chats — WhatsApp or personal phones — to skirt IT controls.

One notable case: In 2021, a UAE bank manager got a call mimicking the regional director’s voice. He wired $35 million to a fraudster.

Live video deepfakes:

AI now enables real-time video impersonation, as nearly happened in the Ferrari case. The attacker created a synthetic video call of CEO Benedetto Vigna that nearly fooled staff.

Staged, multi-channel social engineering:

Attackers often build pretexts over time — fake recruiter emails, LinkedIn chats, calendar invites — before a call.

These tactics echo other scams like counterfeit ads: Criminals duplicate legitimate brand campaigns, then trick users onto fake landing pages to steal data or sell knockoffs. Users blame the real brand, compounding reputational damage.

Multivector trust-building works the same way in executive impersonation: Familiarity opens the door, and AI walks right through it.

Related: The Deepfake Threat is Real. Here Are 3 Ways to Protect Your Business

What if someone deepfakes the C‑suite

Ferrari came close to wiring funds after a live deepfake of their CEO. Only an assistant’s quick challenge about a personal security question stopped it. While no money was lost in this case, the incident raised concerns about how AI-enabled fraud might exploit executive workflows.

Other companies weren’t so lucky. In the UAE case above, a deepfaked phone call and forged documents led to a $35 million loss. Only $400,000 was later traced to U.S. accounts — the rest vanished. Law enforcement never identified the perpetrators.

A 2023 case involved a Beazley-insured company, where a finance director received a deepfaked WhatsApp video of the CEO. Over two weeks, they transferred $6 million to a bogus account in Hong Kong. While insurance helped recover the financial loss, the incident still disrupted operations and exposed critical vulnerabilities.

The shift from passive misinformation to active manipulation changes the game entirely. Deepfake attacks aren’t just threats to reputation or financial survival anymore — they directly undermine trust and operational integrity.

How to protect the C‑suite

  • Audit public executive content.

  • Limit unnecessary executive exposure in video/audio formats.

  • Ask: Does the CFO need to be in every public webinar?

  • Enforce multi-factor verification.

  • Always verify high-risk requests through secondary channels — not just email or video. Avoid putting full trust in any one medium.

  • Adopt AI-powered detection tools.

  • Use tools that fight fire with fire by leveraging AI features for AI-generated fake content detection:

    • Photo analysis: Detects AI-generated images by spotting facial irregularities, lighting issues or visual inconsistencies

    • Video analysis: Flags deepfakes by examining unnatural movements, frame glitches and facial syncing errors

    • Voice analysis: Identifies synthetic speech by analyzing tone, cadence and voice pattern mismatches

    • Ad monitoring: Detects deepfake ads featuring AI-generated executive likenesses, fake endorsements or manipulated video/audio clips

    • Impersonation detection: Spots deepfakes by identifying mismatched voice, face or behavior patterns used to mimic real people

    • Fake support line detection: Identifies fraudulent customer service channels — including cloned phone numbers, spoofed websites or AI-run chatbots designed to impersonate real brands

But beware: Criminals use AI too and often move faster. At the moment, criminals are using more advanced AI in their attacks than we are using in our defense systems.

Strategies that are all about preventative technology are likely to fail — attackers will always find ways in. Thorough personnel training is just as crucial as technology is to catch deepfakes and social engineering and to thwart attacks.

Train with realistic simulations:

Use simulated phishing and deepfake drills to test your team. For example, some security platforms now simulate deepfake-based attacks to train employees and flag vulnerabilities to AI-generated content.

Just as we train AI using the best data, the same applies to humans: Gather realistic samples, simulate real deepfake attacks and measure responses.

Develop an incident response playbook:

Create an incident response plan with clear roles and escalation steps. Test it regularly — don’t wait until you need it. Data leaks and AI-powered attacks can’t be fully prevented. But with the right tools and training, you can stop impersonation before it becomes infiltration.

Related: Jack Dorsey Says It Will Soon Be ‘Impossible to Tell’ if Deepfakes Are Real: ‘Like You’re in a Simulation’

Trust is the new attack vector

Deepfake fraud isn’t just clever code; it hits where it hurts — your trust.

When an attacker mimics the CEO’s face or voice, they don’t just wear a mask. They seize the very authority that keeps your company running. In an age where voice and video can be forged in seconds, trust must be earned — and verified — every time.

Don’t just upgrade your firewalls and test your systems. Train your people. Review your public-facing content. A trusted voice can still be a threat — pause and confirm.

https://www.entrepreneur.com/science-technology/how-to-protect-your-company-from-deepfake-fraud/495773


Here Are the 10 States Where People Are Most At Risk of Running Out of Their Retirement Savings. Is Your State On the List?

One of the greatest retirement fears Americans face is outliving their savings and investments, according to a June study from the nonprofit Transamerica Center for Retirement Studies.

A new report published earlier this month by the senior living platform Seniorly highlights these concerns by finding that retirees in nearly every state are expected to fall short of enough income to cover their retirement costs.

The study found that in 41 U.S. states and in Washington, D.C., seniors do not have enough financial resources saved up for retirement. Retirees have an average life expectancy of 18.2 years at retirement age (65 years old) and are expected to bring in $762,000 across their retirement lifetime from Social Security, savings, and investments. However, their average living expenses are $877,000, leaving a gap of $115,000.

Related: How Much Money Do You Need to Retire Comfortably in Your State? Here’s the Breakdown.

Seniorly analyzed available data from sources like the U.S. Social Security Administration and the Census Bureau to calculate expected retirement income and expenses.

The study found that New York was the highest risk state for retirees running out of funds. Expenses in the state were $1.1 million, and income was $670,000, leaving a shortfall of $430,000. Washington is the top state where seniors are least likely to outlive their savings, with a surplus of about $146,000.

A Northwestern Mutual report added to the findings by discovering that Americans believe they need $1.26 million to comfortably retire — that’s the magic number for retirement savings. The majority of Americans (51%) said that it is somewhat or very likely that they will not have enough money to cover retirement expenses.

Related: These Are the ‘Wealthiest and Safest’ Places to Retire in the U.S. None of Them Are in Florida — and 2 States Swept the List.

Here are the 10 states where seniors are most at risk of outliving their retirement savings, according to Seniorly, based on average income across a retirement lifetime and average expenses across a retirement lifetime for each state.

1. New York

Expenses Across Retirement Lifetime: $1.1 million

Income Across Retirement Lifetime: $670,000

Shortfall: $430,000

2. Hawaii

Expenses Across Retirement Lifetime: $1.7 million

Income Across Retirement Lifetime: $1.3 million

Shortfall: $400,000

3. District of Columbia

Expenses Across Retirement Lifetime: $1.1 million

Income Across Retirement Lifetime: $736,000

Shortfall: $364,000

4. Alaska

Expenses Across Retirement Lifetime: $1.1 million

Income Across Retirement Lifetime: $712,000

Shortfall: $388,000

5. California

Expenses Across Retirement Lifetime: $1.3 million

Income Across Retirement Lifetime: $926,000

Shortfall: $374,000

6. Massachusetts

Expenses Across Retirement Lifetime: $1.3 million

Income Across Retirement Lifetime: $1 million

Shortfall: $300,000

7. Rhode Island

Expenses Across Retirement Lifetime: $960,000

Income Across Retirement Lifetime: $676,000

Shortfall: $284,000

8. Vermont

Expenses Across Retirement Lifetime: $1 million

Income Across Retirement Lifetime: $771,000

Shortfall: $229,000

9. Louisiana

Expenses Across Retirement Lifetime: $724,000

Income Across Retirement Lifetime: $479,000

Shortfall: $245,000

10. Connecticut

Expenses Across Retirement Lifetime: $1 million

Income Across Retirement Lifetime: $851,000

Approximate shortfall: $149,000

One of the greatest retirement fears Americans face is outliving their savings and investments, according to a June study from the nonprofit Transamerica Center for Retirement Studies.

A new report published earlier this month by the senior living platform Seniorly highlights these concerns by finding that retirees in nearly every state are expected to fall short of enough income to cover their retirement costs.

The study found that in 41 U.S. states and in Washington, D.C., seniors do not have enough financial resources saved up for retirement. Retirees have an average life expectancy of 18.2 years at retirement age (65 years old) and are expected to bring in $762,000 across their retirement lifetime from Social Security, savings, and investments. However, their average living expenses are $877,000, leaving a gap of $115,000.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/business-news/here-are-the-top-states-where-seniors-outlive-retirement/496530


3 Catastrophic Continuity Plan Failures That Toppled Industry Giants — and What You Can Learn From Them

Opinions expressed by Entrepreneur contributors are their own.

A Business Continuity Plan (BCP) is often something that many professionals do not pay close attention to. History has shown us that even industry giants can be humbled and collapse or lose significant income when they overlook critical vulnerabilities in their preparation for crises.

This can range from overconfidence in their abilities and technologies used to geopolitical unawareness. If the blind spots are not managed carefully, severe crises can be escalated, which can even threaten the future of the business.

This article will look at three catastrophic BCP failures that brought down industry titans. Every organization or company can learn lessons from these in order to ensure that they do not make the same mistakes.

Related: The Cost of Unpreparedness: Why Many Businesses Lack a Continuity Strategy

Overconfidence in technology — How Facebook lost brand value

Many leading social networks were a few years ago always confident that their AI and automation would help them to solve crises without the need for human intervention. The overreliance can pose severe problems when complex problems arise.

In 2018, Facebook was dealt severe embarrassment for its overreliance on its automation after an automated network configuration tool misapplied changes, which caused the disruption of its services to millions. The incident exposed a critical flaw in that no manual override was in place to be able to correct the error quickly.

Facebook not only suffered reputational damage as users and advertisers lost trust in its reliability, but it also exposed its slow response as engineers struggled to diagnose the issue due to opaque system dependencies. There was also a lack of redundancy as no backup systems were activated in order to bypass the faulty automation.

The big lesson to be learned from Facebook’s error is that automation is still just a tool and not yet a replacement for human judgment. BCPs must always include fail-safes — i.e., manual overrides for critical systems, scenario testing, which means regular drills for technology failures, and transparency in order to ensure clear communication protocols during outages.

Related: Do You Have a ‘Business Continuity Plan’?

A failure to recognize geopolitical certainty led to Adobe usurping Kodak

It is important for major companies to always pay attention to geopolitical shifts and understand that a company has to regularly adapt depending on what happens in the world. Kodak was guilty of treating geopolitical shifts as distant risks, and this shortsightedness led to its downfall.

It was actually Kodak that invented the digital camera, but rather than further developing it, they opted to bury the technology in order to protect their film business. Upon noticing that humans were migrating to digital systems, Adobe migrated earlier than Kodak, embracing cloud-based tools and recurring revenue models. Kodak paid the price for reacting too late and had to file for bankruptcy in 2012.

Kodak paid the price as their leadership clung to legacy revenue streams, they didn’t have a BCP for disruptive tech adaptation and as they had ignored hard trends such as digital migration, which was inevitable.

Learning from the example of Kodak, it is always important for companies to monitor trends and especially identify hard trends such as demographics and technology evolution in order to predict disruptions. Flexible frameworks should be developed in order to allow rapid pivots, and there should be shareholder alignment to ensure that leadership and teams are prepared enough for transformational change.

The semiconductor shortage crisis was caused by underestimating supply chain vulnerabilities

Many BCPs opt to focus on internal risks, such as cyberattacks, and neglect external dependencies such as global supply chains. The 2020-2022 semiconductor shortage was an example of this, as it crippled industries from automotive to consumer electronics.

The Covid-19 pandemic disrupted most industries — global logistic networks and many companies that rely on “just in time” manufacturing, such as Toyota, faced massive production delays. Companies that did not have diversified suppliers and inventory buffers lost billions in income. Ford is estimated to have lost $2.5B due to chip shortages.

Because of single-point failures and the fact that there was an overreliance on a handful of suppliers, some were toppled. There was also a lack of contingency stock, and the lack of buffer inventory for critical components greatly impacted businesses, while slow adaptation delayed reshoring and supplier diversification.

Related: Your Business Faces More Risks Than Ever — Here’s How to Ensure You’re Prepared For Any Disaster

The lesson from all of this is that for a BCP to be resilient, it must include supplier diversification, stress testing and inventory buffers. There should be partnerships with vendors across regions. Stress testing will stimulate supply chain disruptions in BCP drills, and inventory buffers help to maintain strategic reserves for critical materials.

In today’s day and age, the difference between survival and collapse will often lie in analyzing and recognizing blind spots before they become problems. All businesses should aim to learn from the above scenarios because, in business continuity, complacency is the greatest risk of all, as it can lead to a business’s downfall.

With the world and technology now constantly evolving, a company must embrace change and continuously work on finding ways to be relevant for the far future.

A Business Continuity Plan (BCP) is often something that many professionals do not pay close attention to. History has shown us that even industry giants can be humbled and collapse or lose significant income when they overlook critical vulnerabilities in their preparation for crises.

This can range from overconfidence in their abilities and technologies used to geopolitical unawareness. If the blind spots are not managed carefully, severe crises can be escalated, which can even threaten the future of the business.

This article will look at three catastrophic BCP failures that brought down industry titans. Every organization or company can learn lessons from these in order to ensure that they do not make the same mistakes.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/growing-a-business/3-continuity-plan-failures-that-toppled-industry-giants/495774