Will U.S. Inflation Drop Below 2% Again? Don’t Hold Your Breath — But Don’t Panic Either.

Opinions expressed by Entrepreneur contributors are their own.

As we are in mid-2025 and inflation has cooled off a bit (we’re talking around 2-3%), one question dominates kitchen tables alike: Will U.S. inflation ever return to the Federal Reserve’s cherished target of below 2%?

It’s a fair question. And a complicated one. Having spent 20 years watching economic cycles from both Wall Street and Main Street perspectives, I’m here to untangle this web of monetary forces and offer my take on America’s economic future.

What exactly is inflation, and why does 2% matter?

Before diving into predictions, let’s clarify what we’re discussing. Inflation isn’t just rising prices. It is the rate at which prices for goods and services rise, eroding purchasing power. Formally, it “measures how much more expensive a set of goods and services has become over a certain period, usually a year.” In plain English, if your grocery bill, rent, gas and Netflix subscription are all a bit higher than last year, that’s inflation in action.

Central banks, like the U.S. Federal Reserve, target a 2% inflation rate because it signals a healthy, growing economy — not too hot, not too cold. Too high, and consumers suffer. Too low, and economies risk stagnation.

But this “Goldilocks zone” has been hard to reach lately. Post-pandemic stimulus, supply chain chaos, labor shortages and geopolitical tensions have all pushed inflation up. Even as things stabilize, price growth remains sticky. So, the idea of consistently low inflation feels more like a memory than a forecast.

Related: 3 Strategies To Protect Your Business From Inflation

The upside of low inflation (and why some fear it, too)

Let’s be clear: Low inflation has perks. It creates predictability for businesses, helps consumers save more and keeps interest rates down, which fuels borrowing and investment. When prices rise slowly and steadily, it helps everyone plan. If you know your rent and milk costs are creeping up around 2% a year, you can budget, negotiate salaries and invest confidently. The ECB explains it nicely: “When inflation is low, stable and predictable, it helps people and businesses to better plan their savings, spending and investment. That helps the economy to grow, in turn creating jobs and prosperity.”

But there’s a flip side. Extremely low inflation — or deflation — can stall growth. Companies may delay investment. Consumers might postpone purchases, expecting lower future prices. That’s why central banks don’t aim for 0%, but instead hover around that magic 2%.

Related: ‘Positive Momentum’: Inflation Hit a Four-Year Low in April. Here’s What It Means for Interest Rate Cuts.

What’s at stake for international businesses?

If the U.S. achieves sustained low inflation again, expect a domino effect.

For global companies operating in or exporting to the U.S., this could mean more stable input costs and consumer behavior. Currency values might shift, especially in emerging markets. Investment flows could be redirected, with more capital pouring into the U.S. due to its relative economic calm.

On the flip side, countries reliant on dollar-denominated debt might find themselves navigating a tighter monetary environment for longer. A low-inflation U.S. often means a strong dollar, which isn’t always great news for economies trying to service loans or boost exports.

If U.S. inflation is tamed, the Fed might hold or even cut interest rates sooner. Lower U.S. yields can prompt investors to search for higher returns overseas (say, in emerging markets) or into risk assets (stocks). Indeed, recent news shows soft U.S. inflation helped lift global markets — when April 2025 CPI came in cooler, U.S. stocks jumped and the dollar fell. For foreign companies, that can mean cheaper borrowing costs (since U.S. Treasuries set global rates benchmarks) and more capital flowing their way.

So, will inflation dip below 2% this decade?

Here’s the honest truth: It’s possible — but not likely without serious shifts in our economic situation. After careful analysis, I believe U.S. inflation will occasionally touch below 2% in the coming years, but staying there consistently? That’s a tough sell. We’re more likely looking at a “new normal” of 2.5-3.5% for several years, with occasional dips below 2% followed by rebounds above it.

The structural factors that previously anchored inflation have fundamentally shifted. Several reasons for caution exist. De-globalization, reshoring of manufacturing and energy transitions all introduce new cost pressures that simply didn’t exist in the hyper-globalized pre-2020 economy.

Building resilience into supply chains means sacrificing some efficiency — and efficiency losses translate to higher prices. Labor market tightness persists, with wages rising in ways unlikely to reverse completely. Structural labor shortages in key sectors maintain upward pressure on wages.

We’re also seeing sticky services inflation where prices in healthcare, education and housing continue growing steadily. America’s fiscal trajectory remains concerning, with persistent deficit spending across administrations. The sheer magnitude of government debt may eventually pressure monetary policy in subtle but important ways, making aggressive anti-inflation measures politically difficult. Geopolitical instability introduces additional complications as wars and political tensions continue to shock supply chains and create price volatility in key commodities.

Related: Fed Warns of Rising Unemployment and Inflation Risks

Low inflation isn’t just about cheaper coffee or rent. It’s about confidence — among businesses, investors and consumers. While the Fed and policymakers have tools to push inflation down, the world has changed. Supply chains are shifting, labor markets are transforming, and economic power is becoming more multipolar.

If you’re an international business leader, the best play isn’t waiting for 2% inflation to return. It’s preparing for a new normal — one where resilience, agility and pricing power matter more than ever.

And maybe … ordering that $20 diner breakfast today before it costs $25 tomorrow.

As we are in mid-2025 and inflation has cooled off a bit (we’re talking around 2-3%), one question dominates kitchen tables alike: Will U.S. inflation ever return to the Federal Reserve’s cherished target of below 2%?

It’s a fair question. And a complicated one. Having spent 20 years watching economic cycles from both Wall Street and Main Street perspectives, I’m here to untangle this web of monetary forces and offer my take on America’s economic future.

What exactly is inflation, and why does 2% matter?

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/money-finance/will-us-inflation-drop-below-2-again/492202


Stop Trying to Be a ‘Hero-CEO’ — Here’s Why Building a Strong Team Beats Individual Brilliance

Opinions expressed by Entrepreneur contributors are their own.

In the early days of starting a business, the “do-it-yourself” mindset is a survival skill. You write the code, pitch the client, manage the books and clean the office. There’s pride in wearing every hat, and sometimes, no other option.

But eventually, if you’re still doing everything yourself, you’re the bottleneck, not the solution.

One of the hardest transitions a founder has to make is letting go of being the hero. I’ve been there. I bootstrapped 46 Labs from day one. There were no investors, no parachute, no backup plan. For the first few years, I didn’t take a salary. I handled the technical architecture and the business strategy while working alongside a handful of teammates who also had skin in the game.

But here’s what I learned: scaling a company doesn’t happen when the founder works harder — it happens when the founder learns to trust and build around others. The hero-CEO model doesn’t scale. It burns out. And often, it takes the company down with it.

Related: 7 Steps to Building a Smart, High-Performing Team

Why the hero mentality fails

Being the hero can feel good, especially early on. You close the deal, solve the client issue, squash the bug and feel indispensable. But that “indispensable” feeling is dangerous. Because if you’re the only one who can solve a problem, you’ve just created a fragile system.

I’ve watched brilliant founders build businesses that revolved entirely around their abilities. They made every decision. They approved every hire. They were on every sales call. Eventually, the business outgrew its ability to control it. And instead of delegating, they worked longer hours. They held on tighter.

That works — until it doesn’t. When something breaks, the team doesn’t know how to respond. When you step away, progress stalls. That’s not leadership. That’s dependency.

In aviation (which I’ve done for years), no pilot flies alone for long. You rely on checklists, instruments, copilots and systems. Not because you can’t fly the plane solo, but because flying safely requires redundancy, collaboration and awareness of your own limitations.

Business is the same. You don’t scale by controlling everything — you scale by building systems that work without you.

Related: 5 Long-Term Strategies to Build and Sustain High-Performing Teams

Hiring people you’ll actually trust

One of the best things I ever did as a founder was throw out the traditional hiring playbook. I don’t look at resumes. I don’t care where you went to school. I want to know how you think, how you solve problems and how you communicate under pressure.

We’ve hired people from outside the telecom industry, from outside the U.S., from industries like fashion or finance. They’ve become some of the best team members I’ve worked with. Not because they knew telecom, but because they knew how to think critically, challenge assumptions and own their outcomes.

If you want to stop being the hero, you have to hire people you’ll trust with the keys. That means focusing on mindset and fit, not just experience. It also means giving people the freedom to operate. A strong team isn’t just made of smart people — it’s made of empowered people.

Replace yourself (over and over again)

A lot of founders talk about “working on the business, not in the business.” But few follow through. Why? Because stepping out of a function you once owned feels like giving up control. But in reality, it’s the most strategic move you can make.

I’ve made it a habit to regularly ask myself: “What am I doing today that someone else should own within the next six months?” If I can’t find anything, I either haven’t built the right team—or I haven’t learned to let go.

Replacing yourself isn’t about disappearing. It’s about creating clarity. When everyone knows what they’re responsible for, decisions get made faster. Mistakes become learning moments instead of bottlenecks. And progress scales with or without your direct involvement.

When I handed off key engineering decisions to people I trusted, our product got better. When I stepped back from day-to-day project management, execution improved. When I stopped being the one reviewing every deal, we closed more of them.

Your job isn’t to hold everything together. It’s to build something that holds together without you.

Related: 7 Ways to Build a High-Performing Team

Focus on systems, not heroics

One of the best lessons from flying is that systems outperform instinct. In a crisis, you don’t rely on your gut—you follow the checklist. You troubleshoot systematically. You communicate with the team. You execute the procedure you practiced 100 times before.

Businesses should work the same way. If a deal goes south, a product fails or a system breaks, your company shouldn’t rely on you to dive in and save it every time. That’s not sustainable—and it’s not scalable.

Instead, build systems that catch problems early. Build dashboards that show you where things are headed. Build processes your team can run without hand-holding.

The less your company relies on heroics, the more it can rely on consistency.

Lead from the front, not the center

There’s a difference between leading and doing. I still jump in when needed. But I don’t try to be the center of everything. That’s not leadership — that’s inertia.

Leading from the front means setting direction, making the hard calls and clearing obstacles so your team can execute. It means showing up with clarity, not with your hands on every project.

When your business is small, you have to do a little of everything. But as it grows, your job is to make sure everyone else can do their jobs better.

That starts with letting go of the need to be the hero.

Final thought

If your company falls apart when you take a week off, it’s not a business — it’s a solo act with support staff.

The founders who scale well are the ones who replace themselves again and again, who build teams that make good decisions without them and who see their job as building the system, not being the system.

You don’t need to be the smartest person in the room. You need to build a room full of smart people — and trust them to fly the plane.

In the early days of starting a business, the “do-it-yourself” mindset is a survival skill. You write the code, pitch the client, manage the books and clean the office. There’s pride in wearing every hat, and sometimes, no other option.

But eventually, if you’re still doing everything yourself, you’re the bottleneck, not the solution.

One of the hardest transitions a founder has to make is letting go of being the hero. I’ve been there. I bootstrapped 46 Labs from day one. There were no investors, no parachute, no backup plan. For the first few years, I didn’t take a salary. I handled the technical architecture and the business strategy while working alongside a handful of teammates who also had skin in the game.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/growing-a-business/why-building-a-high-performing-team-beats-individual/491840


Taylor Swift Just Announced a Major Business Deal That No One Was Expecting: ‘My Greatest Dream Come True’

Since 2019, Taylor Swift has been re-recording her albums in an effort to own her life’s work. And for months, Swifties have been not-so-patiently waiting for an announcement about when she would release the “Taylor’s Version” of her 2017 hit album, “Reputation.”

In typical Swift fashion, there was a big announcement this week — but not what everyone was thinking.

Related: Don’t ‘Shake Off’ These 5 Business, Brand, and Legal Lessons From Taylor Swift

On Friday, Swift announced on her website that she purchased her entire catalog, including music videos, concert films, album art and photography, unreleased songs, and the “memories, madness, and magic” of her “entire life’s work.”

“All of the music I’ve ever made now belongs to me,” Swift told fans in a letter.

Swift made the deal with Shamrock Capital, which reportedly bought her masters in 2020 for “more than $300 million.” The New York Times notes Shamrock Capital is an L.A.-based investment firm founded by Roy E. Disney, a nephew of Walt Disney.

It might also inspire some new fan art.

“My first tattoo might be a huge shamrock in the middle of my forehead,” Swift wrote in the announcement, adding that the transaction was “honest, fair, and respectful.”

“This was a business deal to them, but I really felt like they saw it for what it was to me: My memories and my sweat and my handwriting and my decades of dreams,” Swift wrote. “I am endlessly thankful.”

The price tag of the deal was not disclosed. In October 2023, Bloomberg named Swift to its billionaires list for the first time.

As for “Reputation (Taylor’s Version),” Swift says “Rep TV” it isn’t even a “quarter” re-recorded, though now, with the new deal, fans can listen to the original without feeling guilty.

Related: My Name Is Taylor Swift. Sharing a Name with the Pop Superstar Has Helped My Career.

Since 2019, Taylor Swift has been re-recording her albums in an effort to own her life’s work. And for months, Swifties have been not-so-patiently waiting for an announcement about when she would release the “Taylor’s Version” of her 2017 hit album, “Reputation.”

In typical Swift fashion, there was a big announcement this week — but not what everyone was thinking.

Related: Don’t ‘Shake Off’ These 5 Business, Brand, and Legal Lessons From Taylor Swift

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/business-news/taylor-swift-buys-back-her-masters-no-strings-attached/492519


Business Success Isn’t About Great Ideas, Capital or Timing. Here’s What Actually Matters.

Opinions expressed by Entrepreneur contributors are their own.

I’ve been through it all — companies that soared, companies that sank, deals that looked like gold and turned out to be sand and partnerships that either multiplied value or silently killed it. If there’s one brutal truth I’ve learned after decades of building, buying, selling and sometimes burying companies, it’s this:

Relationships — not ideas, capital or even timing — are the ultimate determinant of success.

It’s a lesson that no spreadsheet will teach you and no pitch deck will fully convey. But it’s the one thing every founder, CEO, investor and partner needs to internalize if they want to build something that lasts.

Let me explain through five unfiltered truths I learned the hard way — some through exits, some through bankruptcies.

Related: How to Build and Sustain Deep, Meaningful Business Relationships (and Why It’s the Key to Long-Lasting Success)

1. Bad partnerships are more expensive than bad products

A bad product can be fixed. A misaligned partner? That’s a cancer in the system.

I once co-founded a company with incredible potential — strong unit economics, great early adoption and even some early buzz in the media. But internally, the leadership team was fractured. One partner prioritized short-term revenue. Another obsessed over product perfection. And I, caught between the two, tried to play referee.

Guess what happened?

We burned cash arguing. We stalled decisions. Morale tanked. Ultimately, the company died — not because of the market, but because we couldn’t get out of our own way.

Looking back, I now ask this before every deal: Do I want to be in a foxhole with this person when things go wrong? If the answer isn’t a hell yes, it’s a no.

2. Bankruptcy is a leadership failure, not a market failure

Yes, markets change. Yes, industries shift. But most of the bankruptcies I’ve seen — including my own — weren’t because of the economy. They were because we made poor decisions, delayed hard conversations and ignored red flags.

We had a company that seemed unstoppable — fast-growing, flush with investor interest and scaling quickly. But internally, management was siloed. Sales leadership was misaligned with operations. Decisions were made based on ego instead of data. We ignored tension because things were “good enough.”

Until they weren’t.

When it collapsed, it was easy to point fingers at external market conditions. But the truth? We failed ourselves.

That experience forever changed the way I build. Now, every leadership meeting starts with alignment. If leadership isn’t rowing in the same direction, I don’t care how good the boat is — it’s going nowhere.

Related: Want Strong Business Relationships? Avoid These 3 Mistakes.

3. Buyers don’t buy products — they buy people

When I’ve successfully exited companies, there’s a pattern that shows up every time: We were aligned with the buyer on values, vision and execution style.

One of our best exits came not because we had the best tech, but because the acquiring team said, “We want to work with you guys.” They knew we had strong relationships across departments, high employee retention and a culture of transparency.

Deals get done when there’s trust. Period. It doesn’t matter how great your EBITDA is if the buyer doesn’t believe in your leadership or your people.

If you’re preparing to exit, ask yourself: Would you buy this company if you didn’t know the numbers, but just knew the people running it?

If the answer is no, you’ve got work to do.

4. Decision-making is a muscle — train it or lose it

Poor decision-making doesn’t show up all at once. It’s a slow erosion — a hundred little moments when you defer, delay or delegate decisions you should own.

One business I led started slipping when we over-delegated key choices to mid-management without ensuring those managers were aligned with the company strategy. Over time, execution drifted. Product launches missed the mark. Marketing lost focus. And we didn’t notice until revenue plateaued.

Strong companies don’t just have good leaders — they have good decision-making systems.

Now, in every company I touch, we prioritize decision hygiene. Clear frameworks. Accountability. Retrospectives. You can’t outsource judgment. You have to train it.

Related: 8 Strategies for Building Long-Lasting Business Relationships

5. The exit isn’t the end — it’s the mirror

When you sell a company, the terms of that exit reflect everything you did right — or wrong.

Great exits happen when:

  • You have strong internal processes

  • Your financials are airtight

  • Your leadership team is trusted

  • Your reputation precedes you

Bad exits — or worse, failed exits — happen when:

I’ve lived both sides, and I’ll tell you: Nothing haunts an entrepreneur more than realizing they killed a great business by not focusing on the fundamentals early enough.

So, what’s the takeaway? If I could give one piece of advice to any founder building a startup today, it’s this:

Invest in relationships before you invest in features. Build trust before you build scale. Fix your internal operating model before you chase more revenue.

Money follows alignment. Buyers follow leadership. Teams follow purpose. And if you get those right, the next big thing might just follow you.

I’ve been through it all — companies that soared, companies that sank, deals that looked like gold and turned out to be sand and partnerships that either multiplied value or silently killed it. If there’s one brutal truth I’ve learned after decades of building, buying, selling and sometimes burying companies, it’s this:

Relationships — not ideas, capital or even timing — are the ultimate determinant of success.

It’s a lesson that no spreadsheet will teach you and no pitch deck will fully convey. But it’s the one thing every founder, CEO, investor and partner needs to internalize if they want to build something that lasts.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/growing-a-business/5-lessons-i-learned-the-hard-way-about-business-success/492094


This Former Firefighter’s ‘Hidden’ Side Hustle Turned Full-Time Business Helps Keep Homes Safe — and Saw ‘Explosive Growth’ to $22 Million Revenue

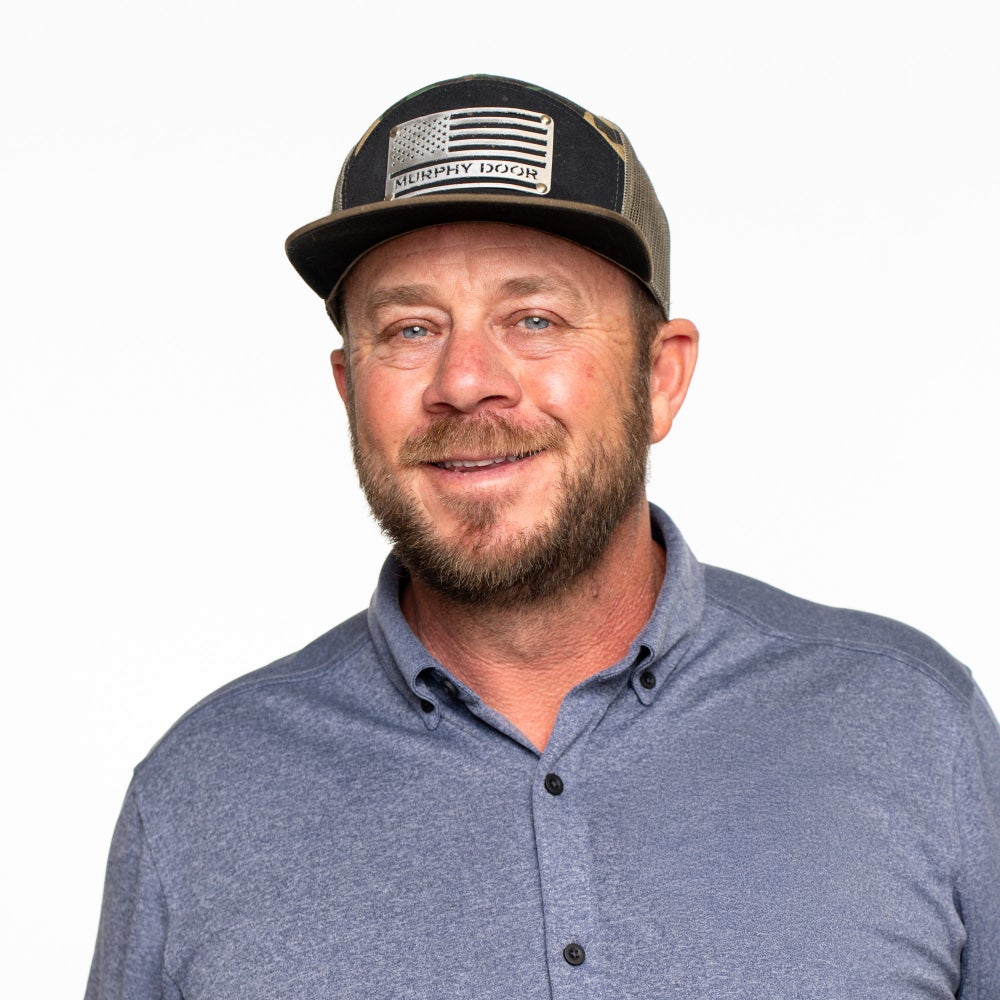
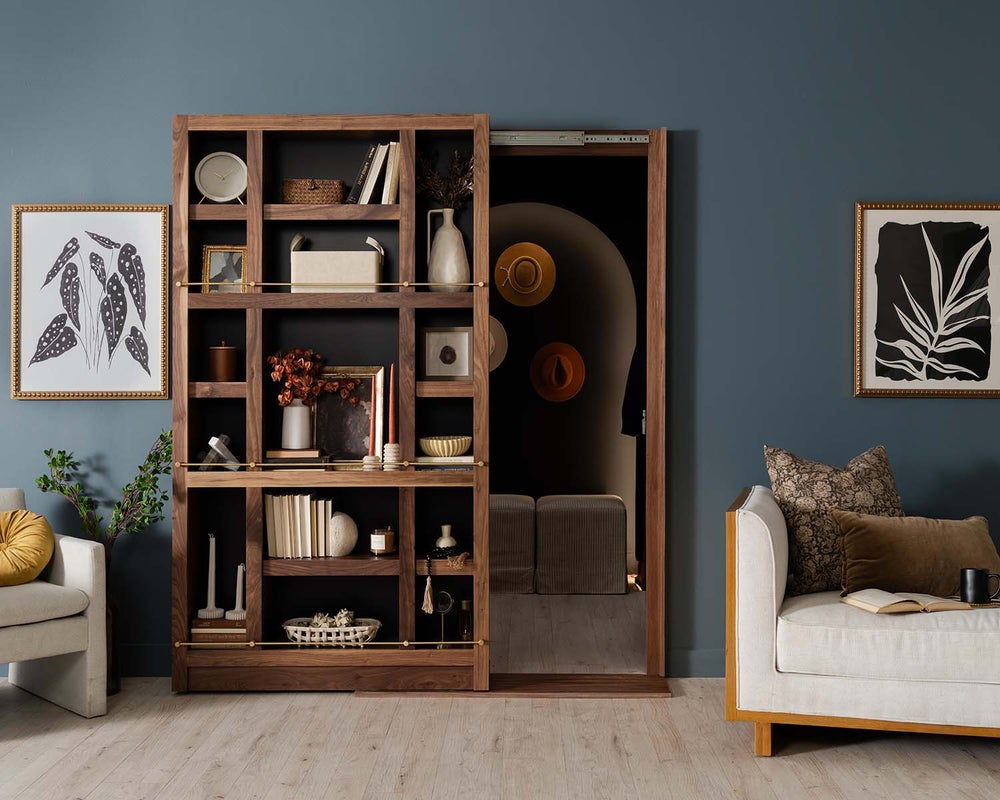
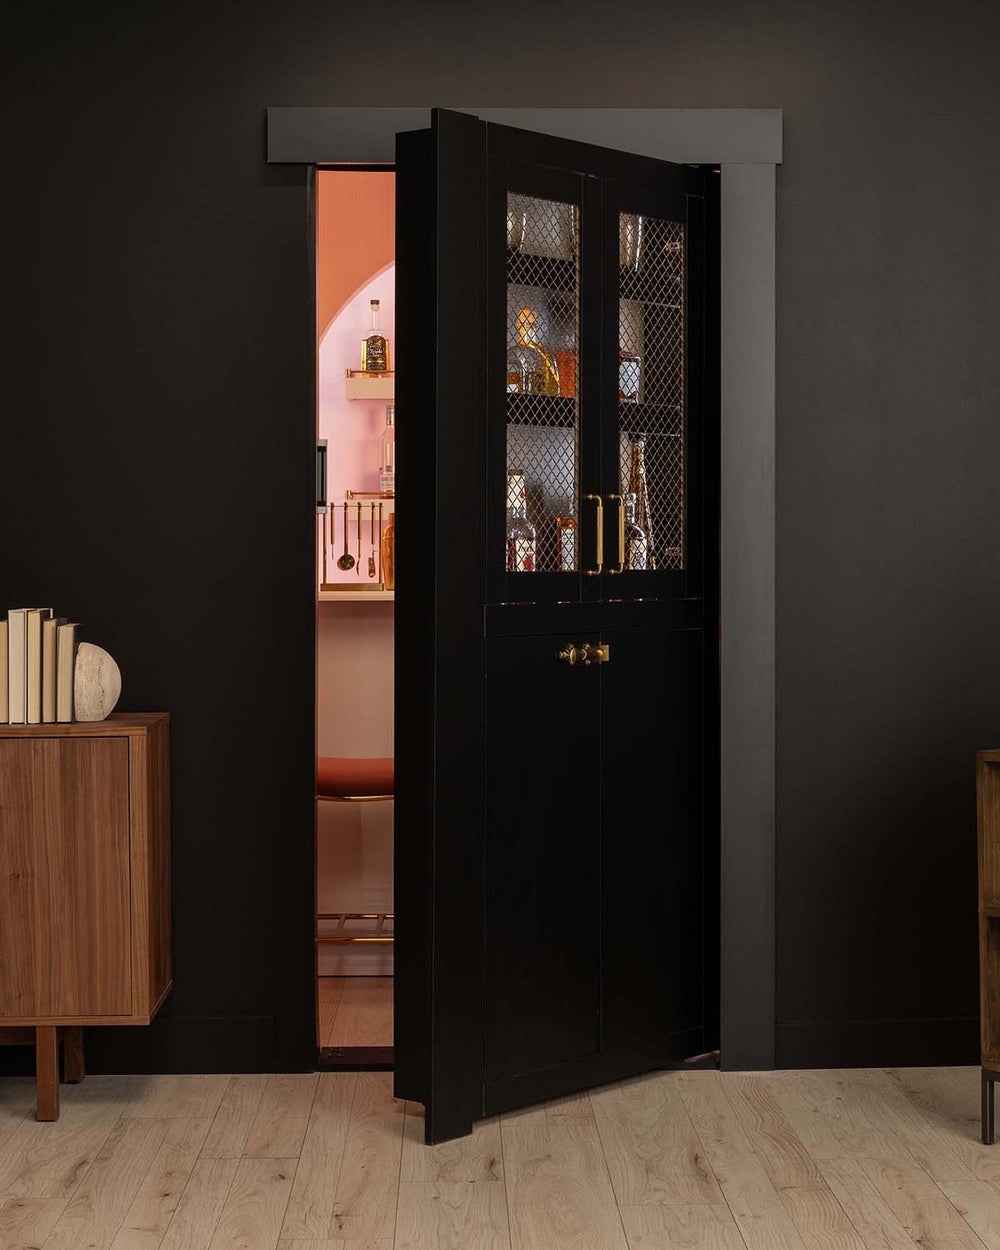
This Side Hustle Spotlight Q&A features Jeremy Barker, 50, of Ogden, Utah. Barker was working as a firefighter and paramedic when he started his company, Murphy Door, which sells “hidden” home furnishings, including bookcase doors and Murphy beds. Responses have been edited for length and clarity.

Image Credit: Courtesy of Murphy Door. Jeremy Barker.

Want to read more stories like this? Subscribe to Money Makers, our free newsletter packed with creative side hustle ideas and successful strategies. Sign up here.

When did you start your side hustle, and where did you find the inspiration for it?
I started Murphy Door in December 2012 while I was still working as a firefighter. The inspiration came from wanting to build a home theater for my kids, which sparked the idea for hidden storage solutions. I believed I could change how the biggest hardware stores approached storage solutions and create a new category in the market.

Related: She Started a Creative Side Hustle While Working ‘Dead-End’ Jobs — Then Grew It From $10,000 to Over $50,000 a Month: ‘[It] Became Magnetic’

What did those early side-hustling days look like?
I kept Murphy Door as a side hustle while working in fire services. In 2012, our first year in business, we only made $30,000, but I kept pushing forward. The real breakthrough came when I took the business online in 2013 and got advice from Architectural Digest to think beyond just hidden doors and focus on multifunctional storage solutions, turning wall space into functional storage rather than just secret compartments.

Image Credit: Courtesy of Murphy Door

Are there any free or paid resources that have been especially helpful for you in starting and running this business?
I have some amazing mentors that I’ve worked with: Don Blohm (operations), John Porter (human capital coach), Brandon Dawson (business systems) and Grant Cardone (sales training). But honestly, the best mentor we could have is our customers. I also believe young entrepreneurs should actively seek out mentors — most successful business people want to help.

If you could go back in your business journey and change one process or approach, what would it be, and how do you wish you’d done it differently?
I wish I had better banking support early on. Utah needs a better banking system — banks are quick to say no, but don’t tell you how to get to yes. I faced bankruptcy twice, once in my early 20s, then the next time in my 30s; better financial guidance could have saved me a lot of headaches.

When it comes to this specific business, what is something you’ve found particularly challenging and/or surprising that people who get into this type of work should be prepared for, but likely aren’t?
Manufacturing equipment lead times can really slow you down. Our German equipment has 6-12 month lead times, which makes the ability to forecast demand with manufacturing capacity accurately a must; it is also why it makes expansion challenging. Balancing creativity with practicality [is also challenging] — you need to ensure innovations are feasible, cost-effective and meet genuine needs.

Can you recall a specific instance when something went very wrong? How did you fix it?
In the early days of Murphy Door, my team showcased our hidden doors for panic rooms at a major trade show. We soon realized that although the product was intriguing, it catered to a limited market. This realization led to the broader concept of hidden storage doors, which had mass appeal. The lesson? Embrace feedback, no matter how unexpected, and be prepared to adapt.

Related: She Quit Her Job at Trader Joe’s After Starting a Side Hustle With $800 — Then She and Her Brother Grew the Business to $20 Million

How long did it take you to see consistent monthly revenue? How much did the side hustle earn?
It took about four years to see consistent revenue that I could rely on. I started Murphy Door in 2012 while still working as a firefighter, and in our first year, we only made $30,000. I kept it as a side hustle, reinvesting everything back into the business.

The real turning point came in 2016 when we hit a $5 million revenue trend: That’s when I finally felt confident enough to leave firefighting and take my first paycheck from the company. So it was a four-year journey of building it nights and weekends while maintaining my day job for financial stability.

Image Credit: Courtesy of Murphy Door

What does growth and revenue look like now?
The growth has been incredible, especially since Covid. We entered Covid with $7 million in revenue and then saw explosive growth: $7 million to $14 million to $22 million. We’re currently maintaining 70% year-over-year growth, which makes us the fastest-growing mill department in the U.S.

We now have 102 employees across multiple manufacturing facilities: our headquarters in Ogden, Utah, a plant in Kentucky, and we’re opening a third plant in Plano, Texas, at the end of the year.

Our reach has been massive — we’ve had over one billion organic views on social media and have completed 200,000 unique installations. We’ve worked on high-profile projects, including for Lionsgate and Only Murders in the Building, done unique build-outs for celebrities and athletes, and collaborated with a Grammy-winning artist.

What do you enjoy most about running this business?
I love the innovation rush of creating something new and watching it succeed. It’s about proving you can build something significant, creating jobs in America and competing with anyone in the world while solving real problems for people. The combination of innovation, impact and building something lasting — that’s what gets me up every morning.

Related: This 34-Year-Old Was ‘Wildly Un-Passionate’ About His Day Job, So He Started a 9-Figure Side Hustle: ‘Be an Animal’

What is your best piece of specific, actionable business advice?
Build fast, break faster, then refine. Too many entrepreneurs wait until something is perfect. That’s a death sentence. I believe in rapid prototyping and getting a version out, then fixing it based on real feedback. With Murphy Ladder, we didn’t wait for perfection — we built a working prototype, then tested it in the real world. What we learned in the field made the final product strong enough to win awards.

This Side Hustle Spotlight Q&A features Jeremy Barker, 50, of Ogden, Utah. Barker was working as a firefighter and paramedic when he started his company, Murphy Door, which sells “hidden” home furnishings, including bookcase doors and Murphy beds. Responses have been edited for length and clarity.

Image Credit: Courtesy of Murphy Door. Jeremy Barker.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/starting-a-business/how-a-firefighters-hidden-side-hustle-led-to-22m-in/492363


How I Turned AI Into a Teammate, Not Just a Tool — and How You Can, Too

Opinions expressed by Entrepreneur contributors are their own.

A few months ago, I was stuck on an email. We were about to announce a delay in releasing a new Jotform product, and I needed to explain the “why” in a way that felt honest, optimistic and clear. Not too corporate. Not too casual. I rewrote the opening five times. Nothing was landing.

Out of frustration more than strategy, I opened up my AI assistant and typed, “Can you help me write a company-wide email about a product delay that’s transparent, reassuring and keeps the team motivated for what’s next?”

What came back was surprisingly decent. Not publish-ready, but good enough to get me moving again. Then I tried something else. “Rewrite this like you’re a product manager talking to power users.” Then again. “Now condense it into an email.” Suddenly, I wasn’t stuck anymore — I had options, tone shifts and plenty of ideas. I wasn’t working alone. I had a co-pilot.

AI has changed the way we work, but the truth is, most of us aren’t actually using it to its full potential. Here’s how to change that.

Related: 7 Ways You Can Use AI to 10x Your Leadership Skills

Shift your perception

Large language models (LLMs) like ChatGPT have been in the mainstream for a few years now, and even the most tech-averse among us have dabbled in their offerings.

According to Harvard Business Review, the most popular use of GPTs is “personal and professional support,” representing a significant shift from last year, when the reigning category was “technical assistance and troubleshooting.” In 2024, users were relying on AI for tasks like generating ideas and looking up the answers to specific questions. Now, their relationship to AI has evolved, with users treating it less like a tool and more like a teammate.

This evolution is key. The more we anthropomorphize AI — not in a sci-fi way, but in a practical, collaborative sense — the more effectively we can leverage it. At this point, I use AI to take a number of tasks off my plate, assigning it roles based on what I need done: If I want to gather stats or summarize articles, I tell it to assume the role of a research assistant. If I want a wireframe copy reviewed, I ask it to act like a UX designer. If I’m refining a pitch or strategy doc, I’ll prompt it to behave like an investor or board member, so I can pressure-test my thinking before presenting it to the real audience.

The more intentional you are about how you “cast” your AI assistant, the more value it can deliver — not just as a helper, but as a genuine extension of your thinking.

Get your prompts on point

AI isn’t magic — it’s responsive. Vague prompts beget vague answers. But with clear direction, including the tone, structure and style you want, you’ll unlock much more powerful results.

Say you want to create a blog post to announce a new feature or product. Instead of simply saying, “Write me a blog post,” make it specific. “You’re the CEO of a tech company who just launched [insert product and description]. Write a 300-500-word blog post that accurately captures the product’s features, includes key details, and explains to users how it will improve their day-to-day workflows. The tone should be confident and enthusiastic, and adhere to the company’s brand voice [examples below].

I’ve found it helpful to treat prompt engineering like managing a junior team member. Rather than scrapping the first draft, offer feedback: “Make this less technical,” “Add a real-world example,” or “Make the first paragraph more engaging.” The more specific the prompt and the revisions, the better the outcome.

Related: Why Smart Entrepreneurs Let AI Do the Heavy Business Lifting

Integrate it into your workflow

One of the biggest missed opportunities of casual AI dabblers is using it sporadically instead of systematically. With just a little bit of upfront time investment, AI has the capacity to streamline nearly every aspect of your daily workflow.

These days, even those without any coding knowledge can easily build customized AI assistants designed to lighten the load of repetitive tasks. From Claude’s “Project” to Gemini’s “Gem,” these platforms enable users to store data like detailed instructions and tone guidelines to keep from having to write the same prompt over and over.

For example, I created a scheduling and email assistant that helps me triage my inbox and prepare meeting follow-ups. It’s loaded with previous email templates, understands my preferred tone and can quickly draft context-aware replies or send a recap with action items after a meeting. Because it’s trained on how I typically communicate and prioritize, it feels less like a chatbot and more like having a highly-responsive personal assistant.

My advice? Start small. Choose one recurring task — something low-lift but time-consuming — and assign it to your AI assistant. Give it structure, test it out and offer feedback as you go. Before long, these automated assistants will start to feel like invisible team members working behind the scenes to keep you focused on what matters most.

A few months ago, I was stuck on an email. We were about to announce a delay in releasing a new Jotform product, and I needed to explain the “why” in a way that felt honest, optimistic and clear. Not too corporate. Not too casual. I rewrote the opening five times. Nothing was landing.

Out of frustration more than strategy, I opened up my AI assistant and typed, “Can you help me write a company-wide email about a product delay that’s transparent, reassuring and keeps the team motivated for what’s next?”

What came back was surprisingly decent. Not publish-ready, but good enough to get me moving again. Then I tried something else. “Rewrite this like you’re a product manager talking to power users.” Then again. “Now condense it into an email.” Suddenly, I wasn’t stuck anymore — I had options, tone shifts and plenty of ideas. I wasn’t working alone. I had a co-pilot.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/science-technology/how-to-turn-ai-into-a-teammate-not-just-a-tool/491096


Starbucks Is Hiring a Pilot to Captain Its Company Aircraft. Here’s How Much the Job Pays.

Starbucks is hiring a “Captain – Pilot-in-Command” for its company Gulfstream aircraft.

According to the job posting, the role pays between $207,000 and $360,300 a year. (Business Insider notes that theaverage airline pilot earned around $250,000 in 2024.)

Related: Starbucks’ New CEO Can Make Up to $113 Million in His First Year

“The captain is one of the company’s most visible representatives to the passengers and serves as a Starbucks ambassador both at home and abroad,” the listing reads. “They model Starbucks’ guiding principles and act with tact and decorum, while providing the utmost in service and safety.”

Starbucks reportedly has at least two Gulfstream G550 jets.

While the job description doesn’t specifically say you’ll be helping the CEO get to the office so he can comply with the company’s return-to-office policy standards, it wouldn’t be a far-fetched idea. It’s been widely reported that Starbucks CEO Brian Niccol commutes over 1,000 miles multiple days a week from Newport Beach, California, to Starbucks’s headquarters in Seattle, Washington.

A Gulfstream G550 from a private company (not Starbucks) lands at Barcelona airport in Barcelona, Spain, on August 30, 2024. Smith Collection/Gado/Getty Images

The pilot role has numerous responsibilities, including managing the flight and crew. Applicants should have a valid Airline Transport Pilot Certificate, a current 1st Class Medical Certificate, an FCC Restricted Radio Operator Certificate, and other FAA-based requirements.

Candidates should also have at least five years of experience operating as a captain with a corporate flight department and at least 5,000 hours of flight time, plus other certificates. See the job listing for the full slate of required items.

Related: ‘We’re Not Effective’: Starbucks CEO Tells Corporate Employees to ‘Own Whether or Not This Place Grows’

https://www.entrepreneur.com/business-news/starbucks-is-hiring-a-pilot-to-captain-its-company-aircraft/492297


Your Resume Might Be Great, But This Is What Makes People Say ‘Hire Them’

Opinions expressed by Entrepreneur contributors are their own.

In today’s unpredictable, hyper-competitive job market, resumes often disappear into a sea of sameness. Even highly qualified candidates struggle to stand out when their accomplishments echo those of countless others. What sets someone apart isn’t always what’s written on paper, but who’s willing to speak up for them.

That’s why your professional network is more valuable than ever. Relationships you’ve cultivated since undergrad, grad school, internships, previous roles, volunteer work and industry groups hold untapped potential. But it’s not as simple as asking a friend for a favor. To truly leverage your network, you need to understand how to earn and give high-engagement referrals — the kind that open doors and drive real results.

Related: You Won’t Find What Makes a Hire ‘Special’ on Their Resume

What is a high-engagement referral?

A high-engagement referral isn’t just a polite nod or a casual mention. It’s a personal, proactive endorsement. It signals a high level of trust and alignment between the recommender, the candidate and the opportunity. When someone offers a high-engagement referral, they’re essentially saying, “I know this person well. I’ve worked with them. I believe in their abilities and character so strongly that I’m willing to put my own reputation on the line.”

This type of referral typically goes beyond a LinkedIn endorsement. It may involve crafting a thoughtful introduction tailored to a specific role, reaching out to a hiring manager directly or guiding the candidate through interview preparation. Some advocates even go as far as recommending the candidate across multiple platforms and internal channels. These extra steps show intention and investment, and hiring teams take notice.

Why these referrals matter for leaders

For business leaders, high-engagement referrals can be transformative. Whether you’re building a startup, leading a team or mentoring rising talent, referrals help you attract and retain high-performing individuals. Candidates who come recommended through trusted sources often prove to be stronger performers and cultural fits. The impact goes beyond recruitment. A culture where referrals are encouraged tends to be one where employees are engaged, invested and proud to bring others into the fold. It also elevates your brand as a place where talent thrives and relationships matter.

So why do high-engagement referrals work so well? First, they cut through the noise. In a landscape where hundreds of resumes might flood a hiring manager’s inbox, a trusted referral can bring a candidate straight to the top of the pile. Second, they offer a signal of trustworthiness, adaptability and cultural fit — qualities that are hard to gauge on paper. And finally, they set a positive tone. Walking into an interview knowing someone has already championed your abilities can create instant rapport, boost your confidence, and even influence the outcome.

Of course, earning such a referral doesn’t happen overnight. It begins with clarity. When you ask for a referral, be specific. Tell your contact what job you’re pursuing, why you’re a strong fit and how they can help. Make their job easier by offering a brief message they can tailor or highlighting shared experiences that make your ask feel relevant and authentic.

Even more important is the groundwork you lay before you need the referral. Stay in touch with mentors, colleagues and collaborators. Check in periodically. Share updates on your work. Offer support when they’re navigating changes. The strongest referrals come from relationships that have been nurtured, not neglected until a favor is needed.

Related: 5 Steps to Hiring the Right People for Your Business

How to earn one

Just as you want to receive high-engagement referrals, you should also look for opportunities to offer them. If a former coworker is job hunting and you can genuinely speak to their strengths, take the time to advocate for them. Write the email. Make the call. The value you offer someone else could have a lasting impact — and it positions you as someone who lifts others as you rise.

At the heart of it all is trust. In today’s evolving professional landscape, trust is the currency of opportunity. It’s not just about credentials or connections. It’s about who will speak up for you with conviction — and who you’re willing to stand behind in return.

Build that kind of network. Invest in it. And when the time comes, you’ll have more than a resume — you’ll have real advocates in your corner.

In today’s unpredictable, hyper-competitive job market, resumes often disappear into a sea of sameness. Even highly qualified candidates struggle to stand out when their accomplishments echo those of countless others. What sets someone apart isn’t always what’s written on paper, but who’s willing to speak up for them.

That’s why your professional network is more valuable than ever. Relationships you’ve cultivated since undergrad, grad school, internships, previous roles, volunteer work and industry groups hold untapped potential. But it’s not as simple as asking a friend for a favor. To truly leverage your network, you need to understand how to earn and give high-engagement referrals — the kind that open doors and drive real results.

Related: You Won’t Find What Makes a Hire ‘Special’ on Their Resume

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/leadership/your-resume-might-be-great-but-this-is-what-makes-people/491332


Here’s What JPMorgan Is Doing With Those First Republic Bank Locations It Acquired Two Years Ago: ‘Expanding Its Affluent Banking’

In May 2023, JPMorgan Chase acquired a “substantial majority of assets and assumed the deposits and certain other liabilities” of First Republic Bank after it collapsed and was seized by regulators. The deal also included First Republic’s brick-and-mortar locations.

Two years later, JPMorgan is announcing what it’s doing with the real estate: opening 14 new “J.P. Morgan Financial Centers” in four states that are “thoughtfully designed to cater to the needs of affluent clients,” according to a company statement.

Related: JPMorgan Chase Says AI Could Cut Headcount By 10% in Some Divisions: ‘We Will Deliver More’

“Through these Financial Centers, we are redefining how affluent clients are served, offering a highly personalized level of service that is backed by the global capabilities of JPMorganChase,” said Jennifer Roberts, CEO of Chase Consumer Banking, in a statement.

Two locations are already open, 14 will open in 2025, and then JPMorgan says it is doubling the total to 31 by the end of 2026. The new branches are opening (mostly) in the former First Republic locations that JPMorgan acquired in May 2023, including Palm Beach, Florida; Napa, California; Madison Avenue, New York; and Cambridge, Massachusetts, according to the release.

“These new Financial Centers offer a highly personalized service model, providing greater flexibility to meet clients’ needs with exceptional attention and care,” Roberts said.

Related: ‘I Defend Your Right to Buy Bitcoin’: JPMorgan Will Let Customers Buy Bitcoin, Though CEO Jamie Dimon Still Thinks It’s Like a ‘Pet Rock’

Clients with more than $750,000 in qualifying deposits and investment balances are welcome at the new, office-based model, which was inspired by First Republic, JPMorgan notes.

Customers who don’t live near a new center can still access the services at their current location or remotely.

Chase also offers a lower-tier called “Private Client,” which is for clients with $150,000 or more in qualifying deposits and investment balances. It is available in all 5,000 Chase branches nationwide, per the release.

Related: ‘This Has to Stop’: JPMorgan CEO Jamie Dimon Outlines How to Run a Successful Meeting

https://www.entrepreneur.com/business-news/jpmorgan-is-opening-affluent-banking-centers-heres/492289


A Record Number of CEOs Stepped Down Last Year. Here’s Why — and How the Rules of Leadership Are Shifting.

Opinions expressed by Entrepreneur contributors are their own.

In 2024, U.S. companies witnessed an unprecedented wave of CEO departures, with 327 executives exiting by November — a level of turnover unseen since 2010. This wave of CEO departures reflects a bigger shift in corporate leadership, as boards and investors are no longer content with big ideas alone; they want leaders who can turn strategy into action.

Consider Intel’s former CEO, Pat Gelsinger. Despite ambitious plans to revitalize the company’s chip manufacturing dominance, Gelsinger’s strategies were deemed too costly and slow, leading to his resignation in late 2024. Such high-profile exits highlight a growing intolerance for leaders who cannot translate vision into tangible results.

This trend signals a broader transformation in leadership expectations. The era of the untethered visionary is fading, replaced by a demand for CEOs who combine strategic foresight with operational excellence.

Related: Are You A Visionary, an Executor or a Processor? Why Your Company Needs All 3 to Succeed.

The execution imperative

Historically, charismatic leaders who could articulate compelling visions were highly sought after. However, recent studies indicate a shift in the traits boards prioritize. According to research from the Harvard Law School Forum on Corporate Governance, there’s an increased demand for CEOs with skills in operations and strategy, and a decreased emphasis on interpersonal or “soft” skills.

Rapid technological change, global instability and evolving customer expectations have raised the bar for leaders, who need to steer the organization through complexity and deliver results.

If you’re serious about building a leadership bench that can execute under pressure, it’s time to stop relying on outdated playbooks. Execution-first leadership doesn’t happen by accident — it’s the result of intentional development, smarter hiring and aligned incentives. Here’s how to make it real inside your company.

1. Revamp leadership development programs

In 2024, leadership development budgets took a significant hit, with average allocations dropping by 70% compared to the previous year. With leadership development budgets slashed, many companies have cut back — or cut out entirely — the programs that prepare mid-level managers for executive roles. As a result, more leaders are stepping into the C-suite without the cross-functional experience or strategic problem-solving skills they need to succeed.

This gap shows up in the numbers. In a recent survey, 45% of managers said their companies aren’t doing enough to develop future leaders. Additionally, only 8% of managers believe their leadership programs actually work. The message is clear: Organizations need to take a hard look at their leadership pipelines and start investing in them again.

Companies can close this gap by creating development programs that give leaders real-world experience, from cross-functional rotations to mentorship with senior executives to high-stakes problem-solving assignments. When these initiatives are built into talent strategies, they help grow leaders who can think big and get things done.

Related: Kevin O’Leary Says This Is the One Skill He Looks For in a Leader — But It’s ‘Almost Impossible to Find’

2. Implement effective succession planning

Even though succession planning is critical, many organizations still aren’t ready when leadership changes happen. Research from the Association for Talent Development (ATD) shows that just 35% of companies have a formal plan in place. Without one, companies often scramble to fill roles, turning to outside hires who might not fit the culture or long-term strategy.

The costs of poor succession planning add up fast. Studies show that external CEO hires not only cost 15% more than internal promotions but are also 84% more likely to leave within three years — often because they’re not the right fit. It’s a clear reminder that ignoring internal talent development can hurt both the bottom line and leadership stability.

The better approach is to focus on your existing bench. That means identifying high-potential employees early and giving them opportunities to stretch their skills, work across teams and learn from seasoned leaders. Companies that invest in their own people don’t just save on recruiting costs — they keep their culture intact and avoid the disruption that comes with an outside hire who might not stick.

3. Broaden talent acquisition strategies

More companies are looking outside their own industries when hiring executives — and for good reason. Leaders with experience in different sectors bring fresh ideas and new ways of thinking that can spark innovation and help businesses handle tough, unfamiliar challenges.

A report by JRG Partners points out that bringing in leaders from other industries can give companies an edge. These executives tend to be adaptable, used to working across different markets and able to apply what they’ve learned in one sector to another. They also know how to get up to speed fast in unfamiliar territory.

LinkedIn research shows that focusing on skills instead of traditional qualifications can completely change the way companies hire — and open the door to a much bigger talent pool. In fact, taking a skills-first approach can expand the number of potential candidates by nearly tenfold worldwide.

Related: How to Develop the Best Leadership Mindset to Execute Your Strategy

To make the most of this, companies can:

  • Hire for skills, not just resumes: Focus on what candidates can do, not just where they’ve worked or what degrees they hold.

  • Use AI and data smartly: Tap into tech tools that help spot transferable skills and uncover talent from outside the usual places.

  • Build a more inclusive hiring culture: Stay open to people with nontraditional backgrounds and career paths — they often bring fresh ideas and perspectives.

Companies that look beyond their own backyard find leaders who can roll with change and push the business forward.

Leadership is changing. Companies that focus on execution, not just vision, will stay in the game. The ones that don’t will fall behind.

In 2024, U.S. companies witnessed an unprecedented wave of CEO departures, with 327 executives exiting by November — a level of turnover unseen since 2010. This wave of CEO departures reflects a bigger shift in corporate leadership, as boards and investors are no longer content with big ideas alone; they want leaders who can turn strategy into action.

Consider Intel’s former CEO, Pat Gelsinger. Despite ambitious plans to revitalize the company’s chip manufacturing dominance, Gelsinger’s strategies were deemed too costly and slow, leading to his resignation in late 2024. Such high-profile exits highlight a growing intolerance for leaders who cannot translate vision into tangible results.

This trend signals a broader transformation in leadership expectations. The era of the untethered visionary is fading, replaced by a demand for CEOs who combine strategic foresight with operational excellence.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/leadership/how-companies-can-develop-leaders-who-actually-deliver/491957