Founders Keep Getting This One Piece of Advice — But It’s Setting Them Up for Failure. Here’s What They Really Need to Hear.

Opinions expressed by Entrepreneur contributors are their own.

There’s a piece of advice that’s been floating around startup circles for years. You’ve probably heard it: “Investors care more about your story than your numbers. Just sell the dream.”

Sometimes, it’s framed as motivational. Other times, it’s passed down from “advisors” who mean well but haven’t actually raised money themselves. Either way, it’s misleading — and for a lot of early-stage founders, it’s exactly what sinks their shot.

The truth? Most serious investors look at both. But if you walk into a room and can’t speak clearly about your numbers, that room closes up fast.

I’ve seen founders with big markets and great pitch decks get passed on, not because the idea wasn’t interesting, but because they couldn’t explain how the business worked underneath.

Related: How to Get Funding: The Dos and Don’ts of Raising Capital From Investors

You don’t need a finance degree, but you do need answers

Investors aren’t expecting perfect models. They know early-stage companies are messy. But they do want to see that you know where your money’s going, how it’s coming in and what your next dollar is supposed to do.

Can you explain your current burn rate? What’s your actual runway — meaning, not just “we raised $1M,” but how long that money lasts at your current pace? How much does it cost to acquire a customer, and are those customers sticking around?

You don’t need ten slides to answer those questions, but you do need to be ready for them. Because when you’re not, it sends a message: You’re still thinking like a product builder, not a company builder.

That’s the gap that kills a lot of deals.

The numbers don’t replace the story — they prove it

The “just focus on the vision” advice sounds good. It flatters the founder’s ego. It tells you your big idea is enough.

However, vision alone doesn’t raise rounds. Numbers give the vision weight. They show how the idea plays out in real-world behavior — what users are doing, how revenue is moving and how the operation scales.

It’s not about spreadsheets for their own sake. It’s about showing that you understand your business like an operator, not just a dreamer.

And the bar has gone up. In a 2023 DocSend report, investors spent the second-most time on the financials section of decks — right after team slides. In other words, once they know who’s behind the company, they want to know how the business actually works.

Being early doesn’t mean you get a pass

It’s easy to think, “We’re pre-revenue, so there’s not much to show yet.” But even pre-revenue businesses should be tracking something — user behavior, early conversion rates, retention from beta users or traction from waitlists. Something that proves demand and shows you’re paying attention to what matters.

Early doesn’t mean immature. In fact, the most investable early-stage teams are the ones that show signs of being operationally sharp from day one.

I’ve sat in meetings where founders with less revenue got further in conversations simply because they spoke clearly about how much they spend, how long it lasts and what specific traction they expect to unlock with more funding.

They weren’t selling perfection; they were showing control.

Investors don’t want potential — they want preparation

A big part of early-stage investing is pattern recognition. And one of the patterns that stands out most — positively or negatively — is how a founder talks about their business under the hood.

Do they dodge financial questions? Do they freeze when asked about margins or CAC? Or do they answer plainly, even if the numbers are small?

The answer says a lot.

Because here’s the truth: Fundraising is emotional for the founder but analytical for the investor. They’re looking at the math, the trajectory and whether the founder knows what levers need to be pulled next.

When someone says, “Investors don’t care about financials,” what they’re really doing is trying to shortcut that process. But there are no shortcuts. Not anymore. And have never been!

Related: The 10 Things You Should Cover in Every Investment Pitch (Infographic)

Raising capital is never easy, and advice is everywhere. Some of it’s useful. A lot of it is noise spread by wannabe advisors.

However, if someone tells you to ignore the numbers and “just pitch the dream and vision,” press pause. That advice might sound motivating, but it’s dangerously incomplete.

You don’t need perfect projections. You don’t need fancy charts. But you do need to own your numbers. You need to understand how your business runs, how it burns and what moves it forward.

That’s not the investor’s job to figure out. It’s yours.

Founders who know their numbers don’t just raise capital — they earn respect in the room. And in this market, that matters more than ever.

https://www.entrepreneur.com/starting-a-business/this-piece-of-advice-keeps-setting-founders-up-for-failure/489267


‘A Great Start to a Big Year’: There’s Been a Surge in Small Businesses Being Sold, According to a New Report

The U.S. business-for-sale market is booming.

According to the latest report from BizBuySell, which hosts a marketplace of businesses for sale, 2,368 businesses were sold in the U.S. in the first quarter of 2025. They represented a total value of $2 billion, a 9% increase in value from the same period a year prior.

“The new year came with a surge of momentum,” Charles Patawaran of Gatsby Advisors Brokerage told BizBuySell. “Overall, Q1 felt more energized and productive, and it’s looking like a great start to a big year.”

Related: ‘Applications Are Surging’: Small Business Administration Reports Significant Growth in Loan Approvals

The report found that the price, cash flow, and revenue of businesses sold were all higher this year than at the same time last year. The median sale price of a business reached $349,000 in the first quarter of the year, a 4% year-over-year increase, while median cash flow grew by 6% to $160,000 and median revenue increased by 3% to $700,000.

It wasn’t all smooth sailing, however. Though business sale transactions grew 4% in January, reflecting optimism for tax cuts and deregulation, they slowed in February and March. Deals took longer to close during the quarter, with businesses lingering for a median of 198 days on the market compared to 172 days a year earlier.

Kinzie Jones of Sunbelt Business Advisors stated in the report that tariff announcements, which added “a layer of uncertainty for buyers and sellers,” were responsible for the longer wait times before a transaction. President Donald Trump has levied tariffs of up to 145% on imports from China, and a tariff of 10% for other countries until July.

“While not halting deal flow, they [tariffs] have increased costs for import-reliant businesses and caused some buyers to scrutinize financials more carefully,” Jones stated.

Related: ‘Strategy All Along’: President Donald Trump Pauses Most Tariffs for 90 Days — Except One. Here’s What We Know.

Nearly two out of five business owners (37%) surveyed by BizBuySell reported increased costs due to tariffs, with 17% facing supply chain disruptions. Meanwhile, the majority of business buyers surveyed by the outlet (75%) are primarily looking for stability in the businesses they purchase.

Some industries are faring better on the market than others. For example, the report notes that sales of manufacturing businesses grew by 3% in Q1, and median sale prices increased by 54% to over $1 million. The growth arrives as the U.S. Small Business Administration approves more manufacturing loans under the Trump administration than in 2021 and launches a Made in America Manufacturing Initiative to create a pipeline of workers for manufacturing jobs.

Meanwhile, retail and restaurant businesses reported fewer buyers for the first quarter of 2025. Restaurant deal volume was down 4%, while retail deals fell 7% year-over-year.

According to the U.S. Chamber of Commerce’s Small Business Index for Q1 2025, small businesses reported being most concerned about inflation and revenue. Over six in ten small businesses said their business was in good financial health during the quarter.

https://www.entrepreneur.com/business-news/sales-of-small-businesses-surged-in-q1-per-new-report/490587


How to Make AI a Core Part of Your Business Strategy

Opinions expressed by Entrepreneur contributors are their own.

Weekly AI integration meetings are an essential part of how our company operates. During these gatherings, team members share their latest discoveries in applying artificial intelligence to game development. I see these events as the culmination of our deliberate strategy to become an “AI-powered entertainment company.” However, just a year ago, it was unimaginable.

Everything changed for us in October 2024. Back then, I saw how AI tools could be personalized to solve specific problems — ones that are unique to each individual. This helped me realize that we weren’t looking at another technology trend that would be forgotten in a year or two. We were witnessing the beginning of a fundamental shift in how businesses operate.

Related: 5 Tactics for Entrepreneurs to Balance AI with Humanity

Strategic skepticism

Like many business leaders, my journey with AI started with a healthy skepticism. Initially, in our company, AI was assumed to be just another buzzword, and we couldn’t see how to apply it meaningfully to our business.

This changed dramatically when I began personally experimenting with AI tools in late 2024. I realized that people don’t operate at their full efficiency, not because they’re lazy, but because they often make the same mistakes others have made before.

Meanwhile, AI gives us access to collective knowledge about successful and unsuccessful methods, allowing us to make new mistakes instead of repeating old ones. This realization led to a strategic pivot for our gaming company. It allowed me to start seeing AI as a fundamental component capable of transforming every aspect of our business.

The personalization revolution

Delivering experiences tailored to each individual’s needs and preferences is at the heart of my AI strategy. AI allows us to achieve much finer personalization than simply targeting cohorts. We can deliver content that feels truly personal, which drives retention.

This approach extends beyond customer-facing applications to internal processes as well. I’ve implemented AI tools that help our employees work more efficiently by adapting to their individual working styles and preferences.

For instance, I’ve noticed that sometimes I prefer to interact with information through voice, and other times through text. AI is the tool that can tailor this interaction to what feels right to me at the moment and transform information into any form I need.

Related: 90% of Your Business Could Be Automated With Just These 4 Tools

Overcoming resistance to change

Implementing AI across an organization doesn’t come without challenges, with human inertia being the primary obstacle. People can be incredibly resistant to change and reluctant even to try new things. They bury themselves in routine tasks and often give up after their first unsuccessful attempt.

To combat the resistance, my company has implemented several strategies:

  • Leading by example. I always start with myself. I show what’s possible with AI tools and demonstrate the results.
  • Creating communities of early adopters. We’ve established a Telegram channel and Slack groups where AI enthusiasts share use cases and success stories.
  • Mentorship programs. Pairing AI-proficient employees with those who are still learning helps provide personalized guidance.
  • Regular challenges and workshops. Structured activities keep employees engaged and motivated to continue exploring AI applications.
  • Celebrating small wins. Recognizing and sharing successes, no matter how small, helps maintain momentum.

The CEO as AI champion

Leadership plays a crucial role in the successful integration of AI. As CEO, it’s my job to inspire and guide people toward adopting an efficient approach to this technology.

It goes beyond simply promoting AI use. It also means helping employees understand how to apply AI to their specific roles. Many people tend to believe that AI can do nothing for their jobs.

To address this, I personally work with employees to identify AI applications in their daily tasks. Sometimes, I have to spend five days in a row asking someone if they’ve tried using AI for a particular task before they finally do and get amazed by the results.

Related: How to Effectively Integrate AI into Your Organizational Strategy

Balancing efficiency and creativity

While AI can dramatically boost efficiency, I still believe that human creativity remains essential. For something to be created, someone needs to want to create it. AI is a tool in the hands of an author. It can make the process faster or slower, but it won’t initiate creation on its own.

This perspective shapes our approach to AI integration as a partnership between human creativity and machine efficiency. It’s an amazing symbiosis: humans direct AI, and AI does what it does best.

An AI-powered future

For businesses looking to make AI a core part of their strategy, my advice is to start small, iterate quickly, and focus on personalization.

Our team is only at the beginning of this journey. But if we move at sufficient speed, we’ll stay ahead. All we need to do is move faster than others. We don’t need to move in exactly the right way. We need to move quickly. I predict that within the next year, we’ll have 30% of our content creation and coding processes transformed to leverage AI significantly.

Making AI a core part of your business strategy is more about fundamentally rethinking how your organization operates than about simply adapting a new technology. In my experience, it requires a combination of visionary leadership, systematic implementation, and a willingness to iterate and learn.

The world has changed. Those who embrace AI now will not only gain a competitive advantage but also participate in reshaping the future of business itself.

https://www.entrepreneur.com/leadership/why-ai-should-be-a-core-part-of-your-business-strategy/488971


‘What’s Your Offer?’: Fyre Festival’s Founder Just Announced He’s Putting the Infamous Brand Up for Sale

After trying (and failing) to relaunch the infamous Fyre Festival a few times, founder Billy McFarland, 33, is selling the brand, he announced in a statement.

The latest event was supposed to take place from May 30 to June 2 in Isla Mujeres, Mexico, but it was announced last week that it was canceled (or never scheduled in the first place, depending on who you ask).

McFarland, the festival’s organizer, was convicted of wire fraud in 2018 for the infamous Fyre Festival disaster in the Bahamas in 2017. The scandal led to numerous documentaries and McFarland spending four years in prison.

In the statement, McFarland said that he is selling the “FYRE Festival brand, including its trademarks, IP, digital assets, media reach, and cultural capital – to an operator that can fully realize its vision.”

He notes that the “brand is bigger than any one person and bigger than what I’m able to lead on my own,” citing the latest cancellation of Fyre Fest 2, “where support quickly turned into public distancing once media attention intensified.”

The website has a slew of documentation available to download, from website traffic to social media reach for prospective buyers, though no estimate of what McFarland is expecting.

In the contact us form, one field asks: “What’s your offer?”

https://www.entrepreneur.com/business-news/fyre-festival-brand-and-assets-are-for-sale-if-you-dare/490578


Make Money on Autopilot With These 5 Smart Passive Income Ideas

Opinions expressed by Entrepreneur contributors are their own.

Are you tired of constantly building, scaling and strategizing to grow your business? As an entrepreneur, your time is your asset, and you spend it delivering service and winning new clients. But what if you could generate more income on autopilot and focus on your main venture?

This secret lies in earning passive income without spending time and energy. Successful business owners sell what they already have in the form of digital products, assets and programs and earn with minimal ongoing effort.

The foundation of passive income is value creation. There’s no shortcut or quick fix to get rich overnight. Money is simply a medium of value exchange. To generate passive income, you must provide value in a way that isn’t directly tied to your time.

Let’s talk about five innovative ways entrepreneurs can do this:

Related: Anyone Can Start a Passive Income Side Hustle For Easy Money — But Only If You Know These 5 Essential Tips First.

1. Investing in stocks and shares

One of the most accessible ways to earn passive income is through investing. You can buy stocks in a company. Investing in dividend-paying stocks means you earn a share of the company’s profits without doing any work. Platforms like M1 Finance or Vanguard make it easy to get started.

In real estate, you buy a property, rent it out and collect monthly income. Another hassle-free way is investing in real estate (REITs) without owning a physical property.

2. Affiliate marketing

Anyone can get started in affiliate marketing without expertise. This is also considered an evergreen business model. It means that it can exist for an extended period of time. You also have the flexibility to be a one-person business or scale your company to have hundreds of employees. But do you know what affiliate marketing is?

You enjoyed a product and told somebody to get it. You give them a code to get that product and earn a commission — that is affiliate marketing.

Some of the best niches for affiliate marketing are:

  • Software and tools: If you use business software like Skool, ConvertKit or ClickFunnels, sign up for their affiliate programs and earn commissions.

  • Online education: Many course platforms have affiliate programs where you earn money by referring students.

  • Ecommerce and physical products: Amazon Associates, Shopify and niche product affiliate programs can generate steady income.

You can automate affiliate income in the following ways:

  • Write SEO-optimized blog posts that rank and bring in traffic over time

  • Review products in YouTube videos and add affiliate links in the description

  • Create an email list and set up automated sequences with affiliate recommendations

If nothing works, you can run paid ads that will bring quick results.

Related: 7 Ways to Make Extra Income Even With a Full-Time Job

3. Monetizing content (YouTube, blogging and podcasts)

Another easy way to earn passive income is by starting a YouTube channel, blogging or starting a podcast. Content creation is a long game, but the potential for passive income is enormous once you build an audience.

You can start a YouTube channel easily and upload videos based on your expertise. You can earn through ads, sponsorships and affiliate links when your channel is monetized.

With the right strategy, blogging can also give you thousands and millions of dollars in passive income. Create a website in a low-competition niche. Write high-quality content and monetize it through ads or affiliate marketing.

Podcasting is another way to get passive income. You can get sponsorship deals, sell premium content or use listener support platforms like Patreon.

You can use different strategies to make content passive. A blog post can become a YouTube script, a podcast episode and a Twitter thread. Use SEO strategies to rank content and drive organic traffic. Generative AI is gradually changing SEO forever, making it easier to generate high-quality content that ranks.

4. Create and sell digital products

Selling digital products is another way to earn passive income. Digital products require no inventory and no shipping, with minimal overhead costs. Need ideas for digital products you can sell?

If you are an expert in a niche (marketing, personal finance, fitness, etc.), package your knowledge into an e-book or guide. You can sell it via Amazon Kindle, Gumroad or your website.

The online education industry is growing at an exceptional rate. Platforms like Udemy, Teachable and Skool make creating and selling courses easy. If you’re an entrepreneur, the valuable lessons you have learned are likely ones that others are willing to pay for.

Business owners love time-saving resources. Selling Canva templates, Notion dashboards or financial planning spreadsheets can also be lucrative.

To make it passive, you can automate the delivery process using platforms like ThriveCart or SendOwl. Set up evergreen sales funnels that bring in leads and convert them automatically. To keep sales steady, continuously update and improve your digital product.

5. Print-on-demand and ecommerce automation

Now, selling physical products doesn’t have to be a time-consuming task. With automation, you can create an ecommerce business that can run itself. You can choose a passive income ecommerce model according to your experience:

  • Print-on-demand (POD): Platforms like Printful or Redbubble can be used to sell T-shirts, mugs or posters. You don’t need to manage inventory.

  • Dropshipping: Find suppliers who can handle fulfillment and run a business without touching a single product.

  • Amazon FBA: Let Amazon store and ship your products while you focus on marketing.

Use AI-powered chatbots to handle customer service. You can also automate email marketing to nurture customers on autopilot. Optimizing product listings can bring organic traffic and minimize ad spending.

Related: How to Make Money While You Sleep

The key to successful passive income as an entrepreneur is selecting income streams that complement your expertise and business model. Instead of spreading yourself too thin, focus on one or two strategies, automate them as much as possible, and reinvest your earnings into scaling your primary business.

Setting up smart passive income streams will create financial stability and give you more time to focus on what truly matters.

https://www.entrepreneur.com/money-finance/make-money-on-autopilot-with-these-passive-income-ideas/489757


If You Bought Gold at Costco, Your Investment Is About to Pay Off Big Time

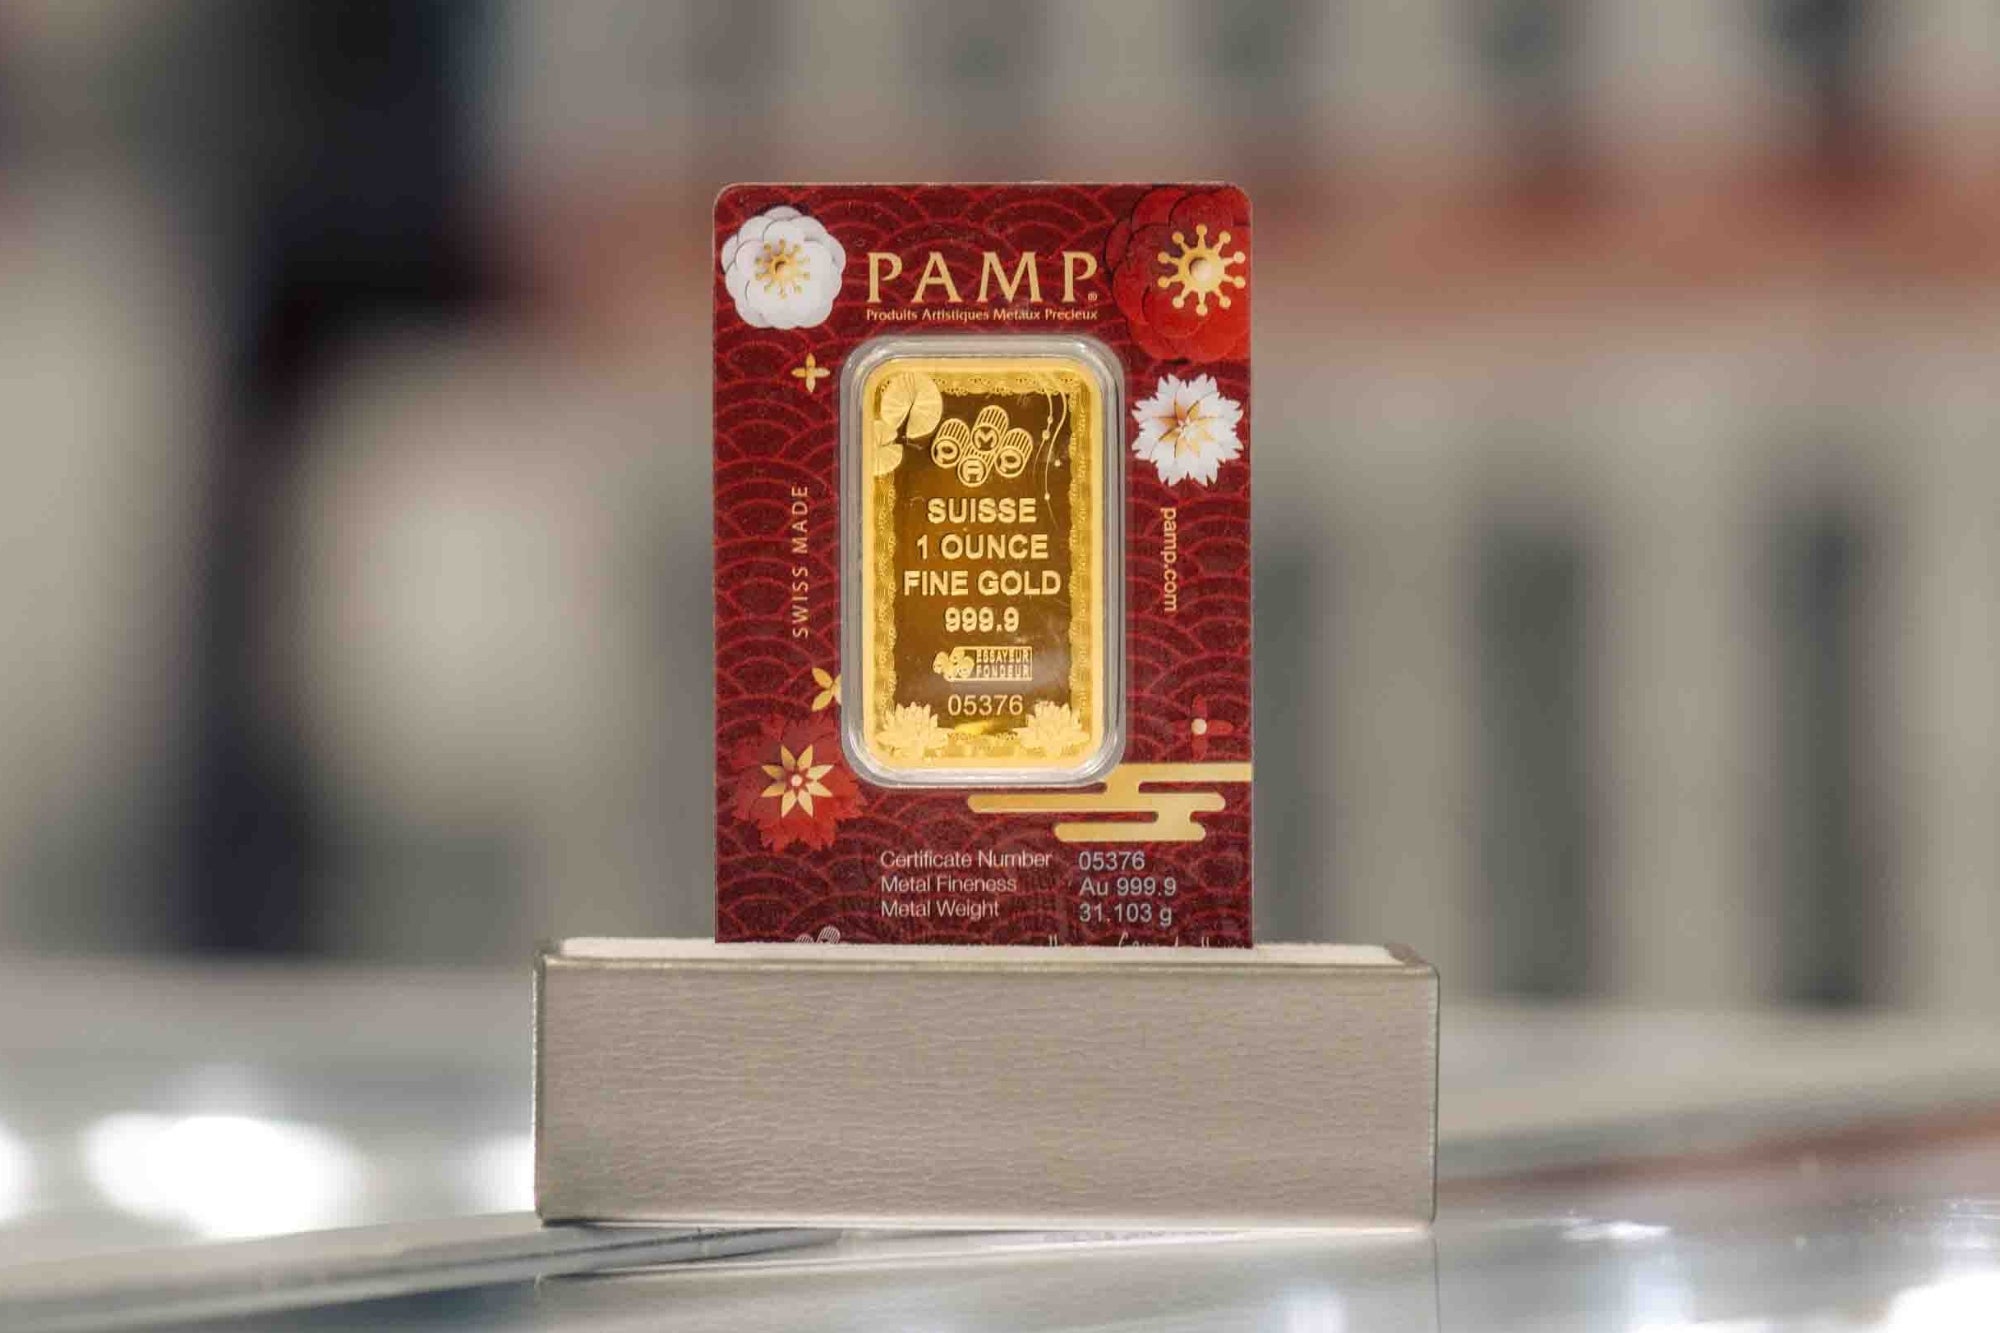
Some people rushed to buy gold bars when Costco first put them on sale, others mocked it. Well, according to JPMorgan, the former group is heading for a pretty big payday.

With recession fears and uncertainty from the U.S.-China trade war, JPMorgan has predicted gold prices rising above $4,000 per ounce in 2026.

Related: This One Costco Item Is Reportedly Generating Up to $200 Million a Month for the Retailer

JPMorgan believes gold prices will reach an average of $3,675 per ounce by the fourth quarter of 2025 and will cross $4,000 per ounce by the second quarter of 2026. The bank also predicts that silver will see a rise in value as well, predicting that prices will hit $39/oz by the end of 2025.

When Costco began selling gold in 2023, the average closing price was $1,943.00 according to Macro Trends.

Wells Fargo analysts estimated last year that Costco could be generating between $100 and $200 million a month from the sales.

Related: Gold is Making All-Time Highs, But So is This Quiet Metal

Meanwhile, Business Insider reports that Costco sells gold at “some of the lowest markups around.”

Oftentimes, the market moves faster than the company can adjust its prices. BI points out that this week, a 1-ounce bar was listed so close to the spot market price that Costco Executive Members who use the Costco Citi credit card (which has cash back rewards on purchases up to $1,250) could essentially turn their money into gold and immediately “see a net reward of 1% to 2% of the purchase price.”

So it might be worth picking up some gold next time you’re in Costco — and buy some shovels in bulk while you’re there. You’re going to need to dig some holes in the backyard to hide your fortune.

Related: Playing Dirty With the Miners of ‘Gold Rush’

https://www.entrepreneur.com/business-news/gold-prices-will-keep-soaring-over-4000-in-2026-jpmorgan/490575


Why the Smartest Entrepreneurs Are Tapping Into This Unexpected Talent Pool

Opinions expressed by Entrepreneur contributors are their own.

If you’re a founder trying to scale without burning out your team or breaking the bank, there’s one strategy you might be overlooking: Hiring offshore talent.

It’s one of the most powerful ways to grow faster, stay lean and increase your team’s capabilities without the overhead of traditional hiring. Yet, so many business owners hesitate to take that step. They worry about time zones, communication or whether the quality of work will match their expectations.

But I’ve seen firsthand how offshore hiring can change the game.

How one offshore hire transformed our business

At SpeakrBrand, we help thought leaders grow their presence and their businesses. One of the biggest levers we pull for our clients is LinkedIn outreach — identifying decision-makers, sending messages, following up and converting that into opportunity.

It’s high-volume, high-touch and requires consistency.

So we brought on Ali, a contractor based in Egypt, to manage this process.

He didn’t just keep up — he leveled us up. Ali restructured our entire outreach system, improved message quality, tracked performance metrics and freed up our internal team to focus on higher-level strategy.

He became so valuable that we started saying, “We need Ali energy on every call.” Ali isn’t an exception. He’s an example of what’s possible when you open the door to global talent.

Offshore work isn’t new, but it’s accelerating

The data backs it up. According to Research and Markets, the global outsourcing services market was valued at $854.6 billion in 2025, and it’s projected to grow to $1.11 trillion by 2030. That’s a compound annual growth rate (CAGR) of 5.46%.

Cost savings don’t just drive this growth — it’s about access, scalability and speed. Businesses are realizing they can find world-class talent without being constrained by local hiring pools.

Whether it’s design, copywriting, operations, sales support or development, the reality is simple: The best person for the job might not be in your zip code.

Related: Why Now Is the Best Time to Consider Offshoring Some Jobs

Why offshore talent is a competitive advantage

Hiring globally isn’t about offloading low-skill tasks. It’s about building a smarter, more agile business.

Here’s what it allows you to do:

  • Access Specialized Skills — Global hiring gives you access to a deeper talent pool. You can find specialists who’ve done the exact thing you need, without paying inflated local rates or waiting through long recruiting cycles.
  • Increase Output Without Increasing Burnout — When your team is stretched thin, you either miss opportunities or burn people out. Offshore talent lets you expand your team’s output without crushing their capacity.
  • Work While You Sleep — Different time zones can be a strategic advantage. Thanks to a team that works while we’re offline, our outreach system now runs almost 24/7. We wake up to progress.
  • Stay Lean and Flexible — You don’t always need full-time hires. Offshore professionals often start part-time or on a project basis. This gives you flexibility to test, learn and scale without long-term risk.

How to hire offshore (and actually do it right)

Hiring offshore can seem daunting if you’ve never done it before, but it doesn’t have to be. Start small with a test project to evaluate fit, communication and work quality without overcommitting. Be extremely clear from the beginning — outline the task, expectations, timelines and tools to avoid confusion later.

Look for someone who takes ownership, not just someone who checks boxes; you want a partner who can improve processes over time. Set communication norms early by sharing your availability, how you want updates and what success looks like.

And when you find a great hire, don’t stop at a contractor relationship. Build trust, offer growth opportunities and treat them as true team members.

Related: Why Remote Work and Offshore Talent Are Becoming Essential for Businesses

Final thoughts

Hiring offshore isn’t a shortcut — it’s a strategy. It’s how you scale smarter. It’s how you stay competitive without adding unnecessary complexity. And it’s how you build a business that’s both efficient and human.

Ali helped us get there.

He didn’t just help us grow pipeline — he helped us protect our team’s energy. He showed us what it looks like when someone shows up with grit, ownership and the mindset to build something great, no matter where they’re located.

And he’s not the exception.

He’s just one of many waiting to be found — if you’re willing to look beyond borders.

https://www.entrepreneur.com/starting-a-business/why-offshore-talent-is-essential-for-all-business-owners/489959


Google Tells Some Remote Staff to Return to the Office: ‘An Important Part of How We Innovate’

Google is tightening its hybrid work policy and telling remote workers in several divisions to return to the office three days a week or risk losing their jobs, per internal documents seen by CNBC on Wednesday.

Google informed some remote staffers that their only option would be accepting a voluntary buyout and leaving the company if they chose not to return to the office on a hybrid schedule.

Related: Google Says It Won’t Follow Amazon’s Lead With a Return-to-Office Mandate — Yet

Remote workers on Google’s human resources People Operations team who live within 50 miles of an office have to return to the office on a hybrid schedule by June, Courtenay Mencini, a Google spokesperson, told CNBC. If they fail to show up, their roles will be eliminated.

Google began offering buyouts to the People Operations team in February, giving mid-to-senior-level employees the option to receive 14 weeks of salary plus one added week for every full year of service if they chose to leave voluntarily.

Remote employees in Google’s Technical Services unit are also affected by the shift to hybrid work. Google has requested that remote staff in the division return to the office three days a week or accept a voluntary exit package. The tech giant is offering to cover relocation costs for remote employees to move within 50 miles of an office.

Mencini told CNBC that the switch to hybrid work only affects remote workers on certain teams and does not impact the whole company. Mencini cited “in-person collaboration” as the reason for the return-to-office push.

Related: Everyone Wants to Buy Google’s Chrome Browser — Including OpenAI, According to a Top ChatGPT Executive

In January, Google gave all employees on its Platforms and Devices unit the option to accept a buyout. Earlier this month, Google laid off hundreds of employees in the division, which works on Chromebooks and Pixel devices.

Google co-founder Sergey Brin wrote in a memo last month to employees on Google’s AI team that staff should spend “at least every weekday” in the office and work “60 hours a week.”

Google’s official policy is hybrid work for most employees. Google stated in 2021 that it was adopting a hybrid work policy, intending to have 60% of Googlers in the office three days a week, 20% in the office full-time, and 20% working completely remotely.

By the end of 2024, Google had 183,323 full-time global employees.

https://www.entrepreneur.com/business-news/google-asks-some-remote-workers-to-return-to-the-office/490577


‘Clock Is Ticking’: Kevin O’Leary Speculates ‘There Won’t Be a Third’ TikTok Ban Extension

Kevin O’Leary is ready for a TikTok to deal to get done.

On Instagram, the long-time “Shark Tank” investor posted a recent television interview (conducted in his signature pajama pants) and told his followers that the TikTok “clock is ticking.”

“We’re on our second 75-day extension,” O’Leary told Fox Business. “I speculate that there will not be a third.”

Related: President Donald Trump Extends TikTok Ban Deadline Again — Here’s What to Know

The deadline for a TikTok deal was April 5, but it was extended for 75 days a second time earlier this month. President Trump wrote on Truth Social the same day that his administration is “working very hard” on a deal to “save” the app.

In the interview, O’Leary added that he doubts any S&P 500 company would want to pay the penalty of $5,000 a user if a ban goes through, and added that any speculation of a possible lease deal was “shut down three weeks ago.” Meanwhile, the 75 days will be up in mid-June.

“Anyone who wants to buy this thing now faces rewriting the algorithm,” O’Leary said, adding that it is all up to President Xi Jinping of China and that he “hasn’t decided if he’s going to sell it or not.”

O’Leary has teamed up with billionaire former Dodgers owner Frank McCourt in “The People’s Bid” for TikTok. Reddit co-founder Alexis Ohanian has also joined the team.

AI startup Perplexity also submitted a bid to merge its business with TikTok’s U.S. division for more than $50 billion.

Amazon and Applovin also recently (separately) submitted bids.

Despite the red tape, O’Leary noted that he is “100% still interested” in buying the social media platform.

“Frank McCourt and I have been working on this for so long, we aren’t giving up,” O’Leary said.

Related: Amazon Just Submitted a Bid to Buy TikTok, as AppLovin and Other Tech Companies Make Offers Before the Looming Deadline

https://www.entrepreneur.com/business-news/kevin-oleary-is-ready-for-a-tiktok-deal-clock-is-ticking/490500


Your ‘Helpful’ Feedback Could Actually Be Crushing Your Team’s Morale. Transform Your Approach With This Step-by-Step Guide.

Opinions expressed by Entrepreneur contributors are their own.

Most leaders believe they’re giving helpful feedback. But too often, what they think is constructive comes across as demoralizing, ineffective or outright damaging. The difference? The best leaders don’t just give feedback — they coach, communicate with care, and create an environment where employees feel seen, heard and valued.

Gallup and Workhuman research shows that employees who receive valuable feedback are five times more engaged and 57% less likely to experience burnout. Yet too many leaders fall into the trap of delivering feedback in a way that crushes morale instead of driving improvement.

The solution? Feedback needs to be an ongoing, trust-based conversation, not a one-time critique. It must be framed as coaching, not criticism, and delivered in a way that accounts for more than just words. Your tone, body language, facial expressions and energy play just as big a role as the message itself.

Here’s how to be more effective at giving feedback — step by step.

Related: Employee Feedback Is Only Effective If It’s Done Right. Here’s How to Make Sure It Lands.

Step 1: Shift your mindset — feedback is a gift, not a gotcha

Leaders often hesitate to give honest feedback for fear of being seen as negative. But avoiding feedback doesn’t create a culture of psychological safety; it creates a culture of guessing and stagnation. The best employees want to grow, and they need clear, constructive input to do so.

Key shift: Move from a criticism mindset to a coaching mindset. Think of your team as business athletes. Just as elite performers rely on coaches to refine their skills, employees need guidance, encouragement and practical ways to improve.

Ask yourself:

When you see feedback as an investment in someone’s success, it changes the way you show up.

Step 2: Presence and delivery matter more than you think

The most overlooked part of feedback? How you show up.

Your body language, vocal range, gaze and facial expressions all send a message before you say a word. To curate a warm and inviting atmosphere conducive to accepting constructive feedback, adopt an open posture, connect visually, show concern and care with facial expressions that are authentic and congruent to what you’re saying, and use a conversational tone and cadence. Otherwise, they may feel tension, judgment or discomfort instead.

You silently communicate to the world all day through your body language and presence. Be intentional about how you are perceived. Convey, instead of betray, your message.

Key shift: Feedback isn’t just about what you say but how you make people feel. You need to be fully present, engaged and emotionally attuned.

What to do:

  • Make eye contact: Remove distractions and see the person in front of you; stay “on gaze!” Not in an intimidating way, but with warmth and attentiveness.

  • Adopt an open posture: To signal partnership as opposed to power, face your employee with open arms and gestures that invite conversation, seated at the same level.

  • Mind your facial expressions: Are you showing genuine curiosity and care or unintentionally conveying frustration?

  • Be intentional with your vocal delivery: Vary your pitch and pace. Speak as you would in conversation. Too fast or too slow, too high-pitched or too low-pitched, and your message may be misunderstood.

Effective leaders don’t only plan what they’ll say; they are also intentional about their presence or how they “show up.”

Ask yourself:

  • Is my nonverbal communication reinforcing my message, or undermining it?

  • Am I making this a safe, productive space for the other person to engage?

Related: Your Words Only Tell a Fraction of the Story — Here’s Why Tone and Body Language Actually Matter More

Step 3: Start with strengths, not weaknesses

Too often, feedback begins with what’s wrong rather than what’s working. But neuroscience shows that people are more open to feedback when they feel seen, valued and capable.

Starting with acknowledgment sets a positive tone and reinforces that feedback is coming from a place of support. “I always like to start conversations by sharing how my team members’ strengths have had a positive effect on our business outcomes,” says Kristi Snyder, Chief People Officer at Enthuse Marketing Group. Framing the conversation around strengths helps both parties enter the discussion with a constructive, growth-oriented mindset.

Key shift: Flip the traditional feedback approach. Start with acknowledgment before diving into areas for improvement.

What to say:

By opening with a question, you create a loop of engagement rather than a top-down critique. Employees get to explain their thinking first, which makes them far more receptive to guidance.

Step 4: Ask more, tell less

Great leaders use feedback as an opportunity to understand before they correct. Instead of leading with here’s what you did wrong, try leading with curiosity.

Key shift: Replace statements with open-ended questions to uncover insights and encourage self-reflection.

What to ask:

  • “What was your thought process behind this approach?”

  • “What challenges did you run into?”

  • “How do you think we could refine this?”

By letting employees talk first, you gather context, acknowledge their thinking and collaborate on solutions rather than dictate them. Approaching situations like this makes sure employees feel heard and increases buy-in.

A reminder: Acknowledgment is NOT agreement. Giving employees space to explain their reasoning allows leaders to correct misunderstandings while still respecting their perspective.

Step 5: Deliver feedback with directness and care

Feedback shouldn’t be sugarcoated, but it also shouldn’t feel like an attack. The secret? Balance directness with care.

Key shift: Avoid vague platitudes (“You did great”) and harsh bluntness (“This was bad”). Instead, use clear, actionable and supportive language.

What to say:

  • Instead of “Your presentation was weak,” try: “I see the effort you put in. Let’s strengthen the data to make it even more compelling.”

  • Instead of “You handled that customer situation poorly,” try: “I appreciate how you followed the process. Let’s explore ways to make it more adaptable.”

Related: How to Give Constructive Feedback That Actually Empowers Others

Step 6: Follow up and reinforce progress

The biggest mistake leaders make? Giving feedback once and never revisiting it. Without reinforcement, even the best feedback fades into the background.

Key shift: Feedback shouldn’t be a one-time event — it should be an ongoing dialogue.

What to do:

  • Circle back in a week to see what’s changed.

  • Recognize progress (even small wins) to reinforce learning.

  • Keep feedback alive in regular conversations, not just performance reviews.

Great leaders don’t go it alone

The most remarkable leaders and elite performers lean on coaches to hone their skills. Many of the most effective leaders actively work with executive coaches to refine their ability to deliver impactful feedback. They recognize that feedback is an art — one that can be mastered with guidance, practice and expert insight.

Feedback is meant to bring people closer and move the organization forward, but it must be delivered expertly. Mastering feedback isn’t just about what you say — it’s about how you say it and how it makes people feel. Whether you’re a seasoned executive or an emerging leader, investing in expert coaching can elevate your ability to guide, inspire and develop your team.

Feedback is your leadership superpower. Use it wisely.

https://www.entrepreneur.com/leadership/6-steps-for-giving-employee-feedback-thats-actually-helpful/490157