I Own a Small Business — and I’d Still Choose a Big Company for This Job
Opinions expressed by Entrepreneur contributors are their own.

This article is part of the America’s Favorite Mom & Pop Shops series. Read more stories

Key Takeaways

  • One routine purchase made me rethink where small businesses shine — and where they don’t.
  • I didn’t expect to side with the bigger player, but the experience left little room for nostalgia.

I own a small business. I write about small businesses. My clients are small businesses. And yet, I would never go to a small business to have my car serviced. Small businesses are great — but not for everything.

I’m not saying this without experience. I’ve owned Hondas all my life. I’ve taken my cars to local repair shops countless times. And the experience has been, well, inconsistent at best. I’ve certainly saved money on repairs. But I’ve paid for it elsewhere.

Take, for example, a recent experience I had at a Honda dealership in Philadelphia. I made my maintenance appointment with an AI receptionist, which understood me flawlessly. I received a text confirmation. I then received a call from a human verifying the details. Professional. Courteous. Efficient.

This stood in stark contrast to all the times I’ve waited on hold, reached busy signals or had my call answered by a mechanic in the garage who would say, “yeah, just bring it in” before hanging up.

I arrived at the dealership at my preferred time — 7:30 a.m. — an important detail so I could still get to work on time. And guess what? The dealership was open. I’ve lost track of the number of times I’ve waited fifteen, twenty, even thirty minutes for the lone guy at the local repair shop to arrive. At a dealership, that behavior simply wouldn’t be tolerated.

Once checked in — by two smiling attendants — I waited in a heated, clean, spacious waiting room with free Wi-Fi, free coffee and work cubicles. Go ahead — find me a small repair shop that provides this kind of accommodation. Rents are high. Space is at a premium.

Related: 73 Small Business Ideas to Start in 2026

The service took under two hours, which is exactly what they told me. I never get this kind of projection from a small repair shop. Not only that, but the dealership sent me a text message with a link to a live video stream of my car as the work was being done. What is this black magic?

Putting aside the seamless reservation, cheery staff and pleasant waiting area, the most important thing, of course, is the actual service. And here, too, I felt confident. The work was performed by a certified technician, trained and re-certified by the national organization and checked by a supervisor. Once the service was complete, I received a confirming email with my invoice. The next day? A check-in email with a survey.

Sometimes, it’s better to go to a larger business than a small business. Larger companies have processes, checklists, procedures and internal controls. They have layers of supervision. They have structures in place to handle complaints or issues that can be escalated regionally and nationally if needed. They are simply more reliable and more consistent.

Do I pay more for all of this? Absolutely. My service at the Honda dealership probably cost three times what I’d pay at some small repair shops. And any actual repairs are also charged at higher rates.

I get it. That’s because there’s a lot of overhead beyond the free coffee and Wi-Fi. Those smiling employees are being paid far more than what a small business could likely afford. There’s also more time involved, since both technicians and supervisors are part of the process. And the parts aren’t being pulled from a local junkyard. But for me, all of that is worth the extra cost. You get what you pay for.

Does Honda try to upsell me on additional services or even a new car? Of course. But good for them — I’m not averse to being given choices as long as I’m not pressured into anything, which I never am. Do dealerships make mistakes? It has happened. But when it has, they’ve made it right — no haggling. Trust me, the dealership manager doesn’t want complaints affecting their performance evaluation. I have a higher level of confidence that they’ll get it right.

Related: The Top 10 Ways Small Businesses Can Make Money This Year

I love small businesses like anyone else. Small businesses make up roughly half of the country’s economy and employ about half of its workers. I’m a fan of the great local restaurant, the parts supplier, the family-owned plumbing business, the pizza shop and the dry cleaner. And I’m sure there are plenty of amazing local repair shops that can do a better job than the Honda dealership.

Maybe. But am I willing to take that chance — particularly when the downside could be a breakdown on the side of a highway in the middle of the night because some unsupervised technician didn’t do what they said they would? I’m not. Going to a dealership is no guarantee that won’t happen. But there’s a better chance that it won’t.

For some things in life, it’s simply worth relying on a larger organization than a small business.

Key Takeaways

  • One routine purchase made me rethink where small businesses shine — and where they don’t.
  • I didn’t expect to side with the bigger player, but the experience left little room for nostalgia.

I own a small business. I write about small businesses. My clients are small businesses. And yet, I would never go to a small business to have my car serviced. Small businesses are great — but not for everything.

I’m not saying this without experience. I’ve owned Hondas all my life. I’ve taken my cars to local repair shops countless times. And the experience has been, well, inconsistent at best. I’ve certainly saved money on repairs. But I’ve paid for it elsewhere.

https://www.entrepreneur.com/growing-a-business/i-own-a-small-business-and-id-still-choose-a-big/501701


Why Investors Are Looking Beyond Silicon Valley for Fintech Opportunities

Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Fintech’s growth is moving beyond Silicon Valley. New markets have emerged and are growing because financial inefficiency is still a daily reality, and tech provides immediate relief.
  • From Latin America to Africa and Southeast Asia, fintechs are thriving by solving structural inefficiencies, leveraging AI and scaling faster in underbanked markets.
  • Investors who understand the local context, study the interaction between regulation and technology and enter these markets early will gain a competitive advantage.

For more than a decade, Silicon Valley shaped the global fintech narrative. It produced the earliest neobanks, pioneered embedded payments and created the infrastructure layers that modern financial platforms still rely on.

But over the last five years, new markets have emerged and are attracting considerable attention. Yes, Silicon Valley remains the center of gravity, but the slowdown in breakthrough innovation, combined with rising operational costs and tighter competition for engineering talent, has prompted many investors to widen their field of view. At the same time, fintech ecosystems across Europe, Latin America, MENA and Southeast Asia have accelerated rapidly.

These markets are not growing because they want the latest trend. They are growing because financial inefficiency is still a daily reality, and technology provides immediate relief.

Related: 4 Emerging Tech Hubs That Are Challenging Silicon Valley’s Dominance

Emerging and frontier regions are producing high-growth fintechs solving local pain points

In the regions where we are most active as investors, the pattern is consistent. High-friction environments produce high-growth fintech companies.

Latin America continues to show how large underbanked populations create a natural runway for digital lenders and mobile-first banks. MENA and African markets are moving from cash-heavy economies to digital payments at a pace that would be difficult to replicate in mature markets. Southeast Asia faces fragmented payment architectures that create opportunities for interoperable wallets, clearing layers and regional rails.

Even in post-Soviet and Central European markets, where banking penetration is relatively high, the dominance of legacy systems leaves room for AI-first financial products that can compete on speed, cost and user experience.

This dynamic has already produced globally significant companies. Nubank in Brazil, M-Pesa in Kenya, Fawry in Egypt, Plata in Mexico, Kuda in Nigeria and Ualá in Argentina all emerged from markets where traditional financial infrastructure could not keep up with user needs. Their growth illustrates the simple reality that structural inefficiency remains one of the strongest predictors of fintech adoption.

Why emerging markets are ripe for fintech disruption

The appeal of emerging markets goes beyond demographic growth. In many countries, the starting point is fundamentally different from that of the United States. Millions of consumers and small businesses still lack access to credit, savings tools, insurance products or reliable payment methods. New entrants build cloud-native systems without needing to migrate away from decades of outdated infrastructure. Consumers who never relied on physical branches move directly to mobile wallets, instant credit scoring and AI-assisted financial services.

As an example, the banking penetration in India was below 17% just 15 years ago. And today, there are 26 local fintech unicorns providing various kinds of services for a huge market, which, even if it is growing rapidly, is still underserved.

Nigeria provides another vivid example of this dynamic. As Africa’s largest economy with over 200 million people, more than 60% of its adult population remains unbanked. This gap in traditional infrastructure created a perfect runway for digital-first challengers like Kuda (which we invested in at a very early stage). Kuda participated in the Startupbootcamp AfriTech accelerator in 2018 and reached a $500 million valuation just two years later, scaling in a market where demand for accessible financial services is structural, not optional.

Governments in several regions have also recognized the economic leverage of modern payment systems and openly support experimentation. Regulatory sandboxes, digital-bank licenses and open frameworks are becoming more common. Brazil’s rollout of PIX, for example, created a nationwide real-time payments layer in under three years and accelerated the entire fintech sector.

These dynamics create meaningful advantages for investors. Customer acquisition costs tend to be lower than in the United States, and the unit economics of digital financial services often improve more quickly because the competition from entrenched incumbents is weaker.

Related: 10 Graphs You Need to See About Fintech in the Middle East

Europe: A model for responsible, scalable fintech growth

Europe provides a different but equally important lesson. Although it is not an emerging market, it has become one of the most structured and strategically relevant ecosystems for building fintech at scale. The PSD2 and Open Banking frameworks established interoperability that remains unmatched globally. The AI Act, despite its complexity, introduces regulatory clarity for AI-enabled financial products and gives founders predictable governance expectations.

This environment has already produced companies with truly global ambitions. Revolut (another company we invested in), founded in London a decade ago, scaled from a regional challenger to one of the world’s most valuable fintechs, now serving more than 40 million customers and valued at over $75 billion. This investment has delivered a 44x return on our initial check in 2018. Its growth illustrates how strong consumer trust, regulatory consistency and seamless access to the European single market enable fintech innovations to scale rapidly and responsibly.

Some observers argue that Europe is overregulated, yet the consistency of the framework has produced meaningful benefits. Consumer trust is higher in some European nations, which, combined with the fact that compliance pathways are clearer, helps founders build long-term infrastructure without fearing sudden changes in regulatory posture. Cities such as London, Berlin, Warsaw and Vilnius show that responsible innovation does not slow companies down. It creates an environment where scalable fintech can grow with less volatility.

Related: How Europe Became the Stage for a Fintech Revolution

California is no longer the sole main value driver for the fintech industry

Taken together, these developments explain why the next generation of category-defining fintech companies could emerge from places such as Cairo, São Paulo, Lagos, Mexico City, Warsaw, Jakarta or Istanbul.

As generative AI becomes a core component of risk scoring, onboarding, fraud detection and advisory services, markets that are still building their financial systems have an advantage. They can integrate AI from the beginning rather than retrofitting it onto systems built decades ago.

The global fintech landscape has expanded far beyond Silicon Valley. Some of the most promising opportunities now arise in markets where digital financial services solve essential problems rather than incrementally improving existing products.

Regions such as Egypt, Nigeria, Mexico and Indonesia combine unmet demand with regulatory momentum and AI-native infrastructure.

For investors, broadening their geographic focus is no longer a contrarian strategy. It is a competitive advantage. Those who understand the local context, study the interaction between regulation and technology and enter these markets early will be the ones backing the next generation of global fintech leaders.

Key Takeaways

  • Fintech’s growth is moving beyond Silicon Valley. New markets have emerged and are growing because financial inefficiency is still a daily reality, and tech provides immediate relief.
  • From Latin America to Africa and Southeast Asia, fintechs are thriving by solving structural inefficiencies, leveraging AI and scaling faster in underbanked markets.
  • Investors who understand the local context, study the interaction between regulation and technology and enter these markets early will gain a competitive advantage.

For more than a decade, Silicon Valley shaped the global fintech narrative. It produced the earliest neobanks, pioneered embedded payments and created the infrastructure layers that modern financial platforms still rely on.

But over the last five years, new markets have emerged and are attracting considerable attention. Yes, Silicon Valley remains the center of gravity, but the slowdown in breakthrough innovation, combined with rising operational costs and tighter competition for engineering talent, has prompted many investors to widen their field of view. At the same time, fintech ecosystems across Europe, Latin America, MENA and Southeast Asia have accelerated rapidly.

https://www.entrepreneur.com/science-technology/fintech-is-evolving-and-investors-should-pay-attention/500854


Why Startups Stall After Product-Market Fit — And How to Fix It

Opinions expressed by Entrepreneur contributors are their own.

This article is part of the America’s Favorite Mom & Pop Shops series. Read more stories

Key Takeaways

  • Even great products stall when founders confuse demand with scalability — real growth only begins once product-market fit evolves into go-to-market fit, where value, acquisition and customer behavior finally align.

Did you know that in 2012, Canva’s founder faced 100+ rejections from investors? When Canva launched, it didn’t immediately achieve the right product market fit. But its founding team understood that most people wanted to create professional-quality designs, but with complex tools.

Melanie Perkins saw this firsthand while building Fusion Books, the yearbook platform that grew into Australia’s largest of its kind. But this experience didn’t guarantee growth for Canva.

Canva’s insight was strong, but the product had to meet the market in a way that felt accessible to even non-designers. Early growth remained slow because the go-to-market engine wasn’t aligned with how users discovered, evaluated and adopted design tools.

Canva’s eventual acceleration came from building unified alignment across:

  • A radically simplified onboarding experience
  • A freemium model that lowered risk
  • A template-driven SEO strategy that met users at moments of intent.

These go-to-market (GTM) strategy foundations gave way to growth that insight alone couldn’t.

This is the point at which many startups stall. Identifying demand is only the first milestone. In fact, research from McKinsey & Company shows that 78% of companies that successfully build a product and achieve product-market fit still fail to scale.

Scalable growth requires a second key element: GTM-market fit, the point where product value, acquisition motion and user behavior finally align.

Related: A Great Idea Means Nothing Without the Right Market — Here’s How to Find It

Clarifying two milestones: Product-market fit and go-to-market fit

Think of your product market fit as the moment your solution solves a tangible problem for a specific group of customers. PMF alone doesn’t explain how customers arrived, whether similar ones exist in predictable volume, or whether you can acquire them at sustainable economics — all core parts of the foundational steps to scaling successfully.

This is where the GTM strategy becomes essential. A go-to-market fit is the point at which product value, acquisition channels and unit economics synchronize. Here, your funnel becomes predictable, your Ideal Customer Profile (ICP) stands clear and growth isn’t dependent on founder hustle or mere luck.

If PMF answers “Do people want this?”, GTM-market fit answers “Can we consistently grow this?”. Confusing the two leads to premature scaling and that’s when growth starts to stall.

How the gap between PMF and GTM-market fit shows up

Bridging product–market fit and GTM–market fit starts with sharpening your Ideal Customer Profile. Early adopters may love the product, but they’re not always the customers who help you scale. Focus on segments that convert quickly, activate reliably and produce healthy economics — they reveal patterns worth repeating.

From there, build a repeatable GTM motion around how those customers actually buy: simplify onboarding, clarify messaging and remove friction to first value.

You reach GTM–market fit when acquisition costs stay stable as you scale spend, and finding, converting and retaining the right customers becomes consistent, not accidental.

Related: Your Business Will Never Succeed If You Overlook This Key Step

Common mistakes founders make when they scale too early

When founders move beyond product market fit, the most consistent misread is assuming that strong user enthusiasm will naturally translate into scalable demand. Early engagement often reflects the severity of the problem, rather than the reliability of the acquisition path. Without a clear pattern in how new users discover and adopt the product, attempts to scale simply magnify noise.

Another frequent mistake is expanding commercial teams before the company understands who they should be selling to. Headcount cannot compensate for the absence of a defined Ideal Customer Profile or a repeatable conversion narrative.

The third misread is treating feature velocity as a proxy for growth readiness. More functionality rarely resolves the underlying issue: the market has not yet demonstrated a predictable response to the product.

Premature scaling doesn’t just slow momentum — it obscures the signals required to reach true GTM fit.

What GTM fit looks like in practice

Companies approaching the go-to-market fit begin to show a level of consistency that wasn’t present at earlier stages. The same type of customer appears repeatedly, exhibiting a consistent pattern in how they search, evaluate and adopt the product. Their path to value becomes more uniform, which is often the first sign that the market understands the offering in a predictable way.

A simple way to set this practice is to identify key actions taken by high-retention customers and redesign onboarding that guides new users to complete those same steps early in their journey.

Commercial efforts also begin to scale proportionally. Modest increases in spending or outreach produce steady returns rather than volatility, suggesting the company is no longer dependent on founder-led intuition to drive momentum.

Perhaps most telling, retention stabilizes because customers experience the product’s value in the way the business intended — not through exceptional support or workaround workflows, but through the strength of the core experience itself.

When these signals converge, a company is operating much closer to GTM-market fit than product enthusiasm alone would ever reveal.

Related: 6 Reasons Your Perfect Product Isn’t Selling — and How to Avoid the Marketing Mistakes Behind Them

What founders should carry forward about PMF and GTM

The shift from product market fit to GTM-market fit is less about adding volume and more about changing the questions you ask of the business. PMF tells you why customers care; GTM-market fit reveals how the market wants to engage with you. One is discovered; the other is engineered.

What ultimately separates companies that scale from those that stall is the ability to recognize when the problem changes. After PMF, the work is no longer about improving the product — it’s about shaping the pathways through which customers find, understand and experience it at scale.

Founders who embrace this transition early build organizations that grow with intention, not intensity. And that shift often becomes the difference between short-lived traction and a business built to endure.

Key Takeaways

  • Even great products stall when founders confuse demand with scalability — real growth only begins once product-market fit evolves into go-to-market fit, where value, acquisition and customer behavior finally align.

Did you know that in 2012, Canva’s founder faced 100+ rejections from investors? When Canva launched, it didn’t immediately achieve the right product market fit. But its founding team understood that most people wanted to create professional-quality designs, but with complex tools.

Melanie Perkins saw this firsthand while building Fusion Books, the yearbook platform that grew into Australia’s largest of its kind. But this experience didn’t guarantee growth for Canva.

https://www.entrepreneur.com/growing-a-business/why-people-love-your-product-wont-make-your-startup/501223


The 1 Question I Ask Every Successful Person I Meet — and How It’s Changed My Life

Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • When I was a young entrepreneur, I set out on a mission to meet successful people and ask them one question: “What is the best advice you ever received in your life?”
  • The answers I received have not only moved my career forward, but they’ve also given me invaluable lessons about how to live a meaningful life.

I’ve always been inspired by the success of others. But I’ve also been curious about where that success comes from. What sets a person on the pathway to becoming a visionary? What sparks their belief that they can go out and change the world?

Today, I run one of the world’s most successful dialing software companies. But many years ago, I was a young entrepreneur who needed some direction. So I turned my curiosity into a sort of mission to meet successful people and ask them one simple question:

“What is the best advice you ever received in your life?”

Here are two of the most memorable answers I’ve ever received. I hope they inspire you the way they continue to inspire me.

Related: 10 Entrepreneurs Share the Best Advice They’ve Ever Received

Steve Forbes on seizing opportunities

In my early 20s, one of the people I admired most in life was Steve Forbes. He had launched countless successful publications and business ventures. I figured that whatever advice had set him on that path would also hold real value for my life. So I committed myself to finding an opportunity to meet him.

This was back in the early 2000s, and Google search was not yet sophisticated enough to help me figure out how to connect with such a prominent individual. But I eventually came across a small event in Santa Monica where Forbes was scheduled to speak.

I lived in Seattle at the time. It took every spare dollar I had in the bank to buy a plane ticket down there. But that’s what I did.

When I arrived, the room had about 100 people in it. Forbes began by speaking to the group about a book he had recently written called How Capitalism Will Save Us. I spent the next few hours listening to his advice and hearing him answer questions from the audience, wondering when, or if, my moment would arrive.

Towards the end of the night, a line formed so people could get him to sign their books. I cued up with my copy and waited my turn. When I finally made it to the signing table, I looked him in the eye and said:

“Mr. Forbes, I flew all the way from Seattle today just to ask you this question.”

Forbes glanced up. “That’s a lot of effort,” he replied.

“Well,” I said with a smile, “I’m expecting a good answer. Can you tell me the best advice you ever got in life?”

He paused for a moment.

“No one’s ever asked me that before.”

I remember thinking he must have been joking. Surely I couldn’t be the first person to ask Steve Forbes about the advice that helped him become one of the most successful people on the planet.

He folded his arms. Then slowly, he said:

“It’s gotta be what my dad told me when I was young: This isn’t a dress rehearsal.”

What he meant, he explained, was that we get one shot in life. You need to put every ounce of your effort into making sure you’re seizing the opportunities that are in front of you now, because you don’t get a second take.

Ironically, I was already following Forbes’s advice when I bought that plane ticket. If I had let the opportunity pass me by, our paths might never have crossed, and he never would have reinforced my belief in the value of taking risks to achieve your goals.

As you can imagine, this belief has served me well throughout my life and career, especially as a CEO, where success demands action and comes down to inspiring others to take their own shot. But the best leaders don’t push people to act; they help them bring their best selves forward. I saw that lesson come to life years later, in a conversation with NFL coach Pete Carroll.

Related: 5 Risk-Taking Lessons From Founders Who Bet Big and Won

Pete Carroll on staying true to yourself

Pete Carroll is a coach, most recently for the Las Vegas Raiders, my all-time favorite football team. Years ago, I decided to sign up for a coaching clinic he was running, despite the fact that I am neither a football player nor a coach. Even at 6’4″ and 220 lbs, I was one of the smallest guys there. Not that it mattered; I wasn’t really there to learn football. I was there for the Q&A.

As soon as the questions started, my arm was up in the air. Everyone around me was asking questions about plays, formations and strategy. But when it was my turn, I asked Carroll the same question I had asked Forbes at his book signing.

This time, I got an answer immediately. Without skipping a beat, Carroll said to me:

“The best advice I ever got in my life was to be myself.”

He continued. “When I try to be someone I’m not, things don’t end up working well for me. You need to know who you are. Obviously, we all want to improve, but you shouldn’t try to be someone else. Try to be the best version of yourself.”

Carroll’s advice stuck with me because it was simple but deeply human: You can’t lead or live effectively if you’re pretending to be something you’re not.

That perspective has shaped how I try to show up as a CEO. The best results come from helping people lean into what makes them great. When people feel free to be themselves, they show up with passion and do their best work. It’s a lesson I still carry with me today.

Related: Training To Be The Best Version Of Yourself: The How-To

How asking for advice has changed me

The advice I got from Forbes, Carroll and others has done more than move my career forward. It’s given me invaluable lessons about how to live a meaningful life.

Forbes’s answer taught me to seize opportunities, even when the path wasn’t certain. Carroll’s answer taught me to stay grounded in who I am while doing it — a mindset that’s shaped everything from PhoneBurner’s Responsible Communications™ initiative to how I approach fatherhood and family.

Those lessons have a way of resurfacing, often at moments that remind you what really matters.

A few months ago, I found myself writing my mother’s obituary. As I reflected on her life, I realized that a eulogy is not a LinkedIn profile. It’s not a summary of titles, milestones and accomplishments. It’s a story about the things you love most and the risks you’re willing to take for them.

In other words, life isn’t a dress rehearsal. You only get to do it once, so you’d better do it in a way that honors your passion and your unique gifts. One simple question gave me that perspective — so you’d better believe I’ll keep asking it.

Key Takeaways

  • When I was a young entrepreneur, I set out on a mission to meet successful people and ask them one question: “What is the best advice you ever received in your life?”
  • The answers I received have not only moved my career forward, but they’ve also given me invaluable lessons about how to live a meaningful life.

I’ve always been inspired by the success of others. But I’ve also been curious about where that success comes from. What sets a person on the pathway to becoming a visionary? What sparks their belief that they can go out and change the world?

Today, I run one of the world’s most successful dialing software companies. But many years ago, I was a young entrepreneur who needed some direction. So I turned my curiosity into a sort of mission to meet successful people and ask them one simple question:

https://www.entrepreneur.com/leadership/the-1-question-i-ask-every-successful-person-i-meet/500953


Heineken’s CEO Steps Down After Six Years of Flat Performance

Beer is a brutal business, and Dolf van den Brink learned the hard way. Heineken announced that its CEO will step down May 31 after nearly six years leading the world’s second-largest beer maker. Van den Brink “arrived with high expectations, but Heineken has not delivered on them,” RBC Capital Markets analyst James Edwardes Jones told Reuters.

Van den Brink took the job in June 2020 during the Covid-19 pandemic and presided over a turbulent period marked by massive cost inflation, falling sales, declining margins and a battered share price.

Van den Brink is the latest CEO casualty. Brewers have struggled to sell more beer, with hopes of a sales revival repeatedly knocked off course by bad weather, political uncertainty and shifting attitudes toward drinking among younger people. The rise of weight-loss drugs like Ozempic could further dampen food and drink sales. Heineken’s board will now search for a successor.

Read more

Beer is a brutal business, and Dolf van den Brink learned the hard way. Heineken announced that its CEO will step down May 31 after nearly six years leading the world’s second-largest beer maker. Van den Brink “arrived with high expectations, but Heineken has not delivered on them,” RBC Capital Markets analyst James Edwardes Jones told Reuters.

Van den Brink took the job in June 2020 during the Covid-19 pandemic and presided over a turbulent period marked by massive cost inflation, falling sales, declining margins and a battered share price.

Van den Brink is the latest CEO casualty. Brewers have struggled to sell more beer, with hopes of a sales revival repeatedly knocked off course by bad weather, political uncertainty and shifting attitudes toward drinking among younger people. The rise of weight-loss drugs like Ozempic could further dampen food and drink sales. Heineken’s board will now search for a successor.

Read more

https://www.entrepreneur.com/business-news/heinekens-ceo-is-out-after-six-years-of-declining-sales/501848


Not Everyone Feels Optimistic About the New Year. Here’s the Reality Many Are Facing.

Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • While some feel motivated and energized by the new year, many experience stress, dread or mental health challenges as the post-holiday reality sets in.
  • Resolutions, routine restarts, seasonal factors and financial pressure can make the start of the year particularly difficult.
  • Focusing on your mental health, breaking the year into manageable segments, prioritizing physical activity and being kind to yourself can help you navigate these challenges.

You’re back at work in the new year, and LinkedIn is doing what LinkedIn does best. Your feed is awash in exclamation points and recycled optimism: “LFG!” “New year, let’s go!” “Best year yet.”

And look — optimism matters. Excitement can be fuel. Momentum is real. For many people, a new year genuinely feels like a clean slate full of opportunity.

But there’s another side to this moment that rarely makes it into the feed. For every person who feels energized by the calendar flipping, there’s someone else who feels a knot in their stomach. For them, January doesn’t signal renewal — it signals the clock restarting. And that can be heavy.

Related: Happy New Year’s Eve? Many Business Owners Think It’s The Worst Night of The Year. Here’s Why — And What I Told My Clients to Change Their Minds.

Here’s why

First, the holidays are often a desperately needed pause after 11.5 months of nonstop “go, go, go.” A few weeks of reduced pace, family time or simply not being on the grind can feel like oxygen. The problem is that a short break is rarely enough to fully reset a burned-out system. And when the holidays end, what’s waiting on the other side isn’t relief — it’s another 11.5 months of the same pace. For people who live with depression, anxiety or other mental health challenges, that realization can feel overwhelming and trigger serious distress.

Second, January is resolution season. In theory, resolutions are about self-improvement. In practice, they’re often about pressure. “Dry January,” new fitness regimens, productivity overhauls — these goals are usually set with good intentions. But resolutions are hard to sustain. And when they slip (or crash headfirst into a very wet February), that sense of failure can quietly chip away at your mental health.

Third, the holidays disrupt routine — and that disruption is often healthy. Stepping away from work, loosening schedules and breaking patterns can be a necessary reset. But restarting the routine can be daunting. Returning to the grind forces you to confront the idea that this cycle might just repeat itself indefinitely. When the year ahead feels like a long, unbroken loop with no clear finish line, motivation can give way to dread.

Fourth, there’s the weather. In much of the United States, January and February mean colder temperatures and fewer hours of daylight. November and December bring some of the same conditions, but they’re softened by holiday lights, gatherings and built-in cheer.

January and February don’t offer the same buffer. I’m fortunate to live in Colorado now, where even winter brings abundant sunlight. That wasn’t my experience living in the Midwest, where gray skies, dirty snow and limited outdoor options were the norm. Seasonal Affective Disorder is real, and without coping mechanisms, it can be dangerous.

Finally, there’s money. The holidays are a season of spending — and, if we’re honest, often of fiscal irresponsibility. January is when those decisions show up on credit card statements. Bills are higher. Utilities cost more. Groceries, pantries and bars need restocking. In short, all the metaphorical (and literal) checks you wrote in December start getting cashed. According to the American Psychological Association, financial pressure is the number one cause of stress among adults. Coming off the holidays, that stress can feel amplified.

This list isn’t exhaustive. Everyone carries their own individualized challenges — some visible, many not. But the point remains: The start of a new year isn’t universally energizing.

Related: Don’t Set a New Year’s Resolution. There’s a Better Way to Achieve Your Goals in 2026.

So, what’s the takeaway?

First, let’s stop assuming that everyone around us is as excited as we might be. For many people, January doesn’t feel like a launch — it feels like lining up for another marathon, knowing another one waits at the finish line. That doesn’t mean you need to stop posting optimistic updates or celebrating fresh starts. It just means being mindful that your enthusiasm may not be shared by everyone.

Second, if you’re struggling, prioritize your mental health in simple, practical ways. I’m not a mental health professional, but I do live with depression and have never been particularly excited about the new year. Over time, I’ve developed coping strategies that work for me:

  • I don’t treat the new year as a moment for total reinvention. Some things work and should stay. Some things need adjusting. Wholesale lifestyle overhauls are often just a setup for disappointment.

  • I prioritize physical activity. There’s no real substitute. It’s the one part of my day where my focus is entirely on what I’m doing — not work, not stress, not the noise.

  • I try to be kind to myself. If I need time off, I take it.

  • I break the year into smaller segments. I love St. Patrick’s Day, so my first goal is simply getting from January 1 to March 17. Then it’s St. Patrick’s Day to Memorial Day, Memorial Day to the Fourth of July, and so on. Smaller horizons make the journey manageable.

  • Most importantly, I ask for help. Whether it’s a professional resource or simply telling someone you trust what’s going on, asking for help can be the hardest — and most important — step.

The new year can bring optimism and opportunity. For many people, it does. But for others, the end of the holidays marks the hardest stretch of the calendar. We can all do a little better by recognizing that reality and leading with understanding, patience and kindness.

Related: 4 Ways to Overcome Post-Holiday Blues

Key Takeaways

  • While some feel motivated and energized by the new year, many experience stress, dread or mental health challenges as the post-holiday reality sets in.
  • Resolutions, routine restarts, seasonal factors and financial pressure can make the start of the year particularly difficult.
  • Focusing on your mental health, breaking the year into manageable segments, prioritizing physical activity and being kind to yourself can help you navigate these challenges.

You’re back at work in the new year, and LinkedIn is doing what LinkedIn does best. Your feed is awash in exclamation points and recycled optimism: “LFG!” “New year, let’s go!” “Best year yet.”

And look — optimism matters. Excitement can be fuel. Momentum is real. For many people, a new year genuinely feels like a clean slate full of opportunity.

https://www.entrepreneur.com/living/the-dark-side-of-new-year-optimism-that-no-one-talks-about/501618


This German Grocer Is Opening 180 Stores in the U.S. — Should Walmart Be Worried?

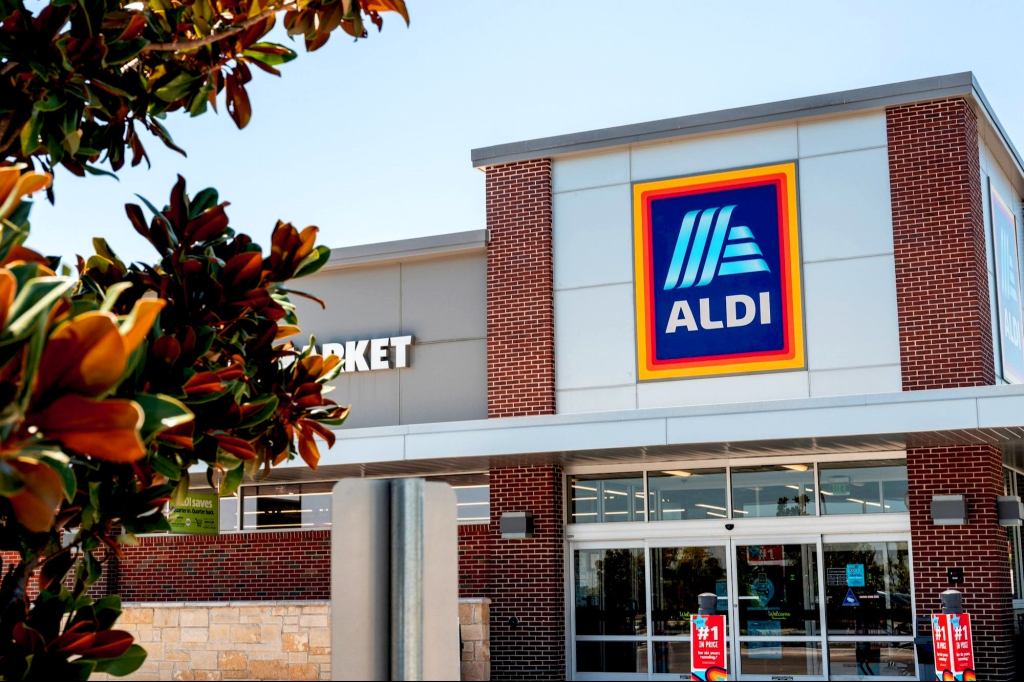
Aldi plans to open more than 180 stores in the U.S. this year, expanding onto the traditional turf of rival supermarkets. The German grocery chain is now the third-largest grocer in the country by store count with 2,614 locations as of December 31, trailing only Walmart and Kroger. Last year was its biggest expansion since opening its first U.S. store in Iowa in 1976, with nearly 200 new locations.

Aldi’s growth comes as shoppers are ditching traditional grocery stores for discounters. Store traffic at Aldi rose 8% in 2025 compared to Costco’s 5.9%, Kroger’s 0.8% and Walmart’s 0.5%, according to Placer.ai. Even wealthy households are choosing cheaper options. The percentage of shoppers earning over $100,000 annually who spend most of their grocery budget at traditional stores dropped 7% year over year.

Aldi’s strategy is all about efficiency: Stores average just 10,000 square feet compared to Walmart’s 178,000, over 90% of products are private label, and items have multiple bar codes for faster checkout. Even the quarter deposit for shopping carts saves labor costs since customers return them to get their money back.

Read more

Aldi plans to open more than 180 stores in the U.S. this year, expanding onto the traditional turf of rival supermarkets. The German grocery chain is now the third-largest grocer in the country by store count with 2,614 locations as of December 31, trailing only Walmart and Kroger. Last year was its biggest expansion since opening its first U.S. store in Iowa in 1976, with nearly 200 new locations.

Aldi’s growth comes as shoppers are ditching traditional grocery stores for discounters. Store traffic at Aldi rose 8% in 2025 compared to Costco’s 5.9%, Kroger’s 0.8% and Walmart’s 0.5%, according to Placer.ai. Even wealthy households are choosing cheaper options. The percentage of shoppers earning over $100,000 annually who spend most of their grocery budget at traditional stores dropped 7% year over year.

Aldi’s strategy is all about efficiency: Stores average just 10,000 square feet compared to Walmart’s 178,000, over 90% of products are private label, and items have multiple bar codes for faster checkout. Even the quarter deposit for shopping carts saves labor costs since customers return them to get their money back.

Read more

https://www.entrepreneur.com/business-news/german-grocer-aldi-opens-180-stores-should-walmart/501847


I Built a 60-Million-User Company by Obsessing Over My Team — Here’s Why It Worked.

Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Hire for problem-solving and values alignment, not logos, titles or perfect past experience.
  • Design a culture that removes ceilings so talent compounds faster than competitors can copy.

Most founders focus too much on technology or marketing ads, while 23% of startups fail because they have built the wrong team. Realizing it’s important not only what you do but also with whom, I made my team my competitive advantage.

Over the past five years, my co-founder Anatolii Kasianov and I have been building HOLYWATER, an AI-first entertainment network reaching 60 million users globally. Each of our products is a breakthrough. My Drama dominates vertical video streaming with 40 million users. My Passion is the world’s #1 independent publishing platform outside China with 1,000+ titles. My Muse pioneered AI-generated vertical series.

Our technology stack, IP portfolio and distribution channels are extensive. But when I was asked in an interview what our startup’s moat was, I said the team. We have 285 talented people committed to building something that no competitor can replicate.

Here are my main principles for hiring and managing a team.

Related: Why You Need to Prioritize Second-Chance Hiring to Compete for Top-Tier Talent

Look beyond the CV

When reviewing candidates, most hiring managers see CVs as a set of rare data, such as years of experience, degrees and previous employers, searching for big names. However, the last one is definitely not worth chasing. Typically, people who have worked in a hot tub at a large corporation cannot get into the startup pace. This is even confirmed by research — former startup employees have more preferences for challenge, independence and responsibility. Therefore, it is certainly not worth hiring someone just because they worked for a large, well-known company. Instead, look beyond that — at their ability to solve challenges. That’s what’s significant in a startup.

At my company, we probe for three things that CVs can’t capture:

  • Problem-solving speed. I’m looking for someone with a “Let me figure this out” mindset. We give candidates real challenges during interviews, not theoretical algorithm questions, but actual problems we’re facing. I want to understand if they can get from confusion to hypothesis to test within hours, not weeks. The pace and curiosity matter more than perfection.
  • Value alignment. At HOLYWATER, we believe that imagination is the only limit. So we seek people who don’t see obstacles as stop signs.
  • Generalist instinct. The best performers don’t say, “That’s not my job.” They say, “I haven’t done this before, but here’s my plan.” This isn’t about hiring people without expertise but about hiring experts who refuse to be limited only by it.

Set a high bar for talent

On the one hand, you need to find the right person fast to build momentum, but on the other, it’s crucial to go slow to build quality. We don’t pick one or the other; instead, we go all in.

We have a lot of recruitment steps, and this rigorous selection process can make some candidates uncomfortable. But it helps us find our people faster, the ones who can navigate uncertainty and stay resilient.

Important: High bar is not about rejecting people who haven’t done the exact job before. It’s about finding people who are willing to move fast and take responsibility for their decisions.

When selecting employees, think about the future, not the past. Focus not on the candidate’s past achievements, but on their potential and how they can unlock it in your startup.

Related: The Dangerous Lie Leaders Tell Themselves About Company Culture

Build an ecosystem that supports creativity and growth

Hiring talented people is only half the battle. The other half is creating an environment where their potential can truly be realized.

Most companies cap people’s growth through invisible ceilings: rigid role definitions, hierarchical approval chains and cultures that punish experimentation. You end up with talented people operating at 60% capacity because the system won’t let them run faster.

We designed HOLYWATER differently. When someone joins our team, they enter an ecosystem where the concentration of exceptional people is extremely high. Each team member is an inspiration and a reference for others. The question shifts from “Am I capable of this?” to “How can I do what they just did?”

Each team member receives the opportunity to express themselves, take responsibility and implement their ideas, regardless of age or skill set. For example, our writers can pitch product ideas, and designers can challenge technical assumptions. This approach does not create chaos; on the contrary, it allows us to see things through a different lens and find new opportunities.

And finally, learning happens through immersion, not training programs. We don’t run formal courses or mandatory workshops. Instead, we make it normal to approach anyone and ask: How did you solve that? What tools accelerated your process? Why did you make that decision? Knowledge transfer happens organically because curiosity is rewarded and gatekeeping is rejected.

The environment you build either multiplies your team’s capabilities or divides them. Choose multiplication.

Related: 3 Reasons Why a Hiring Pause Is the Best Time to Recruit Top Talent

What you can do today

Stop searching for the perfect specialist to solve your next challenge. Start looking for curious minds who solve problems creatively using any tool available.

Treat building a team culture as seriously as building a product. While some founders are afraid to invest in their employees because they will “outgrow” the company and leave, be the ones who show that it is impossible to “outgrow” — because there is no ceiling. Raise the bar, inspire by example, allow them to prove themselves, give honest feedback and grow.

At that point, your competitors won’t be able to replicate your product. Even with access to the same tools, they’ll never catch up on years of learning, adapting and combining talent.

That’s a moat no amount of capital can cross.

Key Takeaways

  • Hire for problem-solving and values alignment, not logos, titles or perfect past experience.
  • Design a culture that removes ceilings so talent compounds faster than competitors can copy.

Most founders focus too much on technology or marketing ads, while 23% of startups fail because they have built the wrong team. Realizing it’s important not only what you do but also with whom, I made my team my competitive advantage.

Over the past five years, my co-founder Anatolii Kasianov and I have been building HOLYWATER, an AI-first entertainment network reaching 60 million users globally. Each of our products is a breakthrough. My Drama dominates vertical video streaming with 40 million users. My Passion is the world’s #1 independent publishing platform outside China with 1,000+ titles. My Muse pioneered AI-generated vertical series.

https://www.entrepreneur.com/leadership/how-i-built-a-team-that-became-my-strongest-advantage/501233


AI in Customer Service Is Eroding Trust — Here’s What You Need to Know Before It Derails Your Business

Key Takeaways

  • 51% of U.S. small businesses have now adopted AI for customer service, but 83% would still prefer speaking to a real person rather than an AI.
  • Businesses risk losing trust, sales and customer loyalty when they rely primarily on AI for customer service.
  • When customers contact a business, they want empathy, warmth, understanding and genuine connection — things AI struggles to provide. AI should empower your people, not replace them.

Across industries, from healthcare to real estate, and law to local services, businesses are racing to adopt AI because the pressure to do so is real — fear of being left behind is a serious motivator. Artificial intelligence promises efficiency, increased productivity and cost savings. It can analyze data faster than any human, streamline workflows and optimize processes that once took hours.

And it’s working: 51% of U.S. small businesses have now adopted AI for customer service, chasing the dream of instant replies, lower overheads and “smarter” interactions.

But here’s the uncomfortable truth: Customers aren’t chasing the same dream.

People still want to talk to people. And that’s a non-negotiable.

AI is rising — but trust is falling

According to a recent AnswerConnect and OnePoll survey of 6,000 adults, 83% would still prefer speaking to a real person rather than an AI when contacting a business. That preference climbs even higher in industries where trust matters most — healthcare (89%), law (87%) and local services (85%) like plumbers, electricians, gardeners, etc.

In other words, the very places where empathy is essential are the places people least want to hear a bot.

The same study revealed that a third of people would hang up if they realized they were talking to AI. Every one of those hang-ups represents a lost opportunity — a sale that doesn’t close, a booking that doesn’t happen or a loyal customer who quietly moves on.

And it’s not just a matter of preference, it’s a matter of trust.

  • 53% say they would trust a business less if it relied primarily on AI for customer service.

  • 86% believe businesses should clearly disclose when they’re using AI instead of a person.

  • 89% believe that human oversight is essential to ensure fairness, accuracy and ethical use of AI.

The loss of empathy in the chase for efficiency

AI is incredible at processing, but empathy isn’t a process; it’s a connection. Yet too many businesses confuse efficiency with a good customer experience.

When customers call, they’re looking for a fast response, yes. But they’re also looking to be heard. They want warmth, understanding and genuine connection.

They don’t want a perfect script. They want a real person who understands urgency, frustration or confusion.

The data backs that up:

  • 70% say human agents show more empathy and care than AI.

  • 65% believe customer service would be worse if AI replaced humans.

  • 69% would be more loyal to a company that employs people, not machines, for their service interactions.

Customers don’t just buy products. They buy trust. And trust doesn’t scale through automation — it’s built one genuine conversation at a time.

The empathy gap: AI can’t close it

AI agents can answer questions. But humans answer needs.

When your customer’s heating breaks at midnight, or they’re facing a legal issue, or they’re worried about their health — no one wants to explain their problem to a machine that can’t feel or care about what’s at stake.

AI systems struggle with nuance, emotion and context. They misunderstand tone, miss subtle cues and lack the emotional intelligence that makes customers feel understood.

It’s no surprise then that 51% of people say AI tools fail to understand their needs, and 48% say their issues remain unresolved after dealing with an AI agent.

That frustration has a cost. Every unresolved issue erodes satisfaction, every robotic response weakens loyalty, and every time AI lacks empathy, it chips away at your brand’s credibility.

Humans build trust. AI should support it, not replace it.

AI is an extraordinary tool, but it’s not the solution to every problem. Used wisely, it can empower people, not replace them.

It can assist your team by surfacing insights, automating low-value tasks or streamlining workflows. But when it comes to connection — the heartbeat of business — it’s the human voice that wins every time. Your people are your biggest advantage.

In an age where technology is everywhere, empathy has become the ultimate differentiator.

The future isn’t AI or human. It’s AI + human.

Businesses that thrive in the next decade will be the ones that know where to draw the line. They’ll use AI to empower their people, as a tool to support them, not to silence them.

They’ll automate processes, but never relationships. Because business is still personal. When a customer calls, it’s not just a transaction — it’s a test of trust.

And trust still begins with a voice.

Key Takeaways

  • 51% of U.S. small businesses have now adopted AI for customer service, but 83% would still prefer speaking to a real person rather than an AI.
  • Businesses risk losing trust, sales and customer loyalty when they rely primarily on AI for customer service.
  • When customers contact a business, they want empathy, warmth, understanding and genuine connection — things AI struggles to provide. AI should empower your people, not replace them.

Across industries, from healthcare to real estate, and law to local services, businesses are racing to adopt AI because the pressure to do so is real — fear of being left behind is a serious motivator. Artificial intelligence promises efficiency, increased productivity and cost savings. It can analyze data faster than any human, streamline workflows and optimize processes that once took hours.

And it’s working: 51% of U.S. small businesses have now adopted AI for customer service, chasing the dream of instant replies, lower overheads and “smarter” interactions.

https://www.entrepreneur.com/leadership/ai-could-be-driving-customers-away-heres-how-to-stop-it/500911


The 3 Tax Decisions Quietly Costing Small Business Owners Thousands Each Year

Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Entity structure, clean books and timing deductions correctly have a direct impact on how much you keep after taxes.
  • Get those three right, and tax season becomes one of the strongest financial advantages a small business can have.

Small business owners work hard to build healthy margins, reinvest in their operations and plan for long-term growth. Many unknowingly give up thousands each year because of overlooked tax decisions. With shifting regulations and increasing pressure on profitability, 2026 will amplify the consequences of poor tax planning even further.

Three areas consistently create the biggest financial impact: choosing the right tax entity, maintaining accurate bookkeeping and accounting controls, and taking advantage of major deductions that owners often leave untouched. Getting these components right can lower tax liability and strengthen year-round financial health.

Related: How Trump’s Tariffs Are Reshaping Startups and Venture Capital

1. Your entity type has a price tag

Your tax entity determines:

  • How much you keep after taxes
  • How you pay yourself
  • How much you owe in payroll and compliance
  • What happens as your profit grows

Most owners choose an entity when they start their business and never revisit it. That one decision often costs thousands per year.

For many small businesses, the biggest savings come from switching from an LLC taxed as a sole proprietorship to an S-Corporation once profit reaches the right level. At roughly $30,000+ in annual profit, the S-Corp structure allows an income split between salary and profit distributions. Salary gets payroll taxes. Distributions don’t. That difference often creates significant annual savings.

C-Corporations rarely make sense for small business owners unless they’re raising capital, issuing equity, or preparing for an exit where stock treatment matters. For high-growth companies, though, it can be the right long-term structure.

The takeaway: Your entity isn’t a lifetime decision. Review it every year. Profit levels, hiring plans, long-term goals, and how you pay yourself should all guide the structure you choose.

Related: 7 Advanced Tax Strategies for Self-Employed Professionals

2. Clean books are the foundation of accurate taxes

A tax return is only as accurate as the books behind it. When bookkeeping falls behind, tax outcomes become guesswork.

The most expensive issues come from:

  • Accounts that aren’t reconciled
  • Personal and business expenses are mixed together
  • Wrong or inconsistent categories
  • Missing or outdated financial statements

One of the costliest mistakes I’ve seen came from a business whose team accidentally categorized a loan as income. A single deposit hit the P&L as revenue, inflated profit by $50,000, and triggered an unnecessary tax bill on money the owner never earned. Once the books were corrected, the difference was $16,000.

Clean books eliminate problems and provide owners with the clarity to plan purchases, time deductions, adjust estimates, meet payroll confidently, and avoid surprises during filing season. Without that foundation, tax planning becomes reactive instead of strategic.

3. High-value deductions that often go unused

You can have the right entity and clean books and still overpay if you miss the deductions that move the needle.

Here are the commonly overlooked opportunities:

  1. Section 179 Deduct up to $2.5 million of qualifying equipment, vehicles, machinery, and software in the year of purchase. Many owners lose this simply by waiting until January to buy equipment.
  2. Bonus Depreciation — An additional deduction on qualifying assets with no dollar limit. It can create a loss and reduce taxable income even further. Timing is critical; coordination with an accountant before year-end matters.
  3. The Augusta Rule — Allows owners to rent their home to their business for up to 14 days per year. The business deducts the rental expense, and the owner pockets the income tax-free.
  4. Other opportunities — Retirement contributions, compliant home office deductions, mileage, vehicle usage, and even R&D credits, especially for companies building processes, improving systems, or developing products.

Why 2026 requires better tax planning

Once December 31 passes, most tax-saving opportunities disappear with it. You can still make certain elections, fund retirement accounts, or prepare supporting documentation, but the big levers require action during the year.

A strong tax advisor helps owners:

  • Evaluate their entity annually
  • Plan purchases around tax impact
  • Capture deductions on time
  • Improve bookkeeping and documentation
  • Avoid costly missteps before they happen

Tax planning works best when it’s a year-round rhythm, not a last-minute task.

Related: I Work With High-Earning Entrepreneurs — This Year-End Practice Prevents Money Issues

The bottom line

The most profitable small businesses in 2026 will be the ones that treat taxes as part of running the business, not as an afterthought at filing time.

With the right entity, clean books, and timely use of high-value deductions, owners keep more of what they earn and avoid the preventable costs that drain margins.

Get those three right, and tax season becomes one of the strongest financial advantages a small business can have.

Key Takeaways

  • Entity structure, clean books and timing deductions correctly have a direct impact on how much you keep after taxes.
  • Get those three right, and tax season becomes one of the strongest financial advantages a small business can have.

Small business owners work hard to build healthy margins, reinvest in their operations and plan for long-term growth. Many unknowingly give up thousands each year because of overlooked tax decisions. With shifting regulations and increasing pressure on profitability, 2026 will amplify the consequences of poor tax planning even further.

Three areas consistently create the biggest financial impact: choosing the right tax entity, maintaining accurate bookkeeping and accounting controls, and taking advantage of major deductions that owners often leave untouched. Getting these components right can lower tax liability and strengthen year-round financial health.

https://www.entrepreneur.com/money-finance/the-3-tax-rules-small-business-owners-learn-too-late/501190