‘Taught Me How to Hustle’: 8 Business Leaders Reveal Big Lessons From Their First Jobs

Key Takeaways

  • First jobs can teach valuable customer-service and sales skills and how to own big mistakes.
  • Here’s what eight business veterans learned from their early roles and their advice for young people today.

Every entrepreneur starts somewhere — often with a first job far from the boardroom or venture capital.

From mowing lawns to selling computers, knives and more, some of the most formative early gigs are those that challenge young people to learn new skills, put their customer-service and sales abilities to the test, and give them the autonomy to make — and learn from — their own mistakes.

Related: His Business Made $120K on Kickstarter, Then $2M in 6 Months — And Could Save Your Thanksgiving

This National Entrepreneurship Month, Entrepreneur heard from eight business leaders about the valuable lessons they took away from their first jobs and the best advice they’d give aspiring founders today.

1. Eric LeVine

LeVine, 56, is the Seattle, Washington-based founder and CEO of wine discovery app CellarTracker.

Image Credit: Courtesy of CellarTracker

What was your first job?
I convinced a local Apple dealer in 1984 to let me help them sell Macintosh computers over spring break. Ever since that first glimpse of a Mac, my life changed.

What were some of the biggest lessons learned from that first job that helped you succeed as a founder?
That experience taught me three crucial things: First, great products sell themselves when they solve real problems intuitively. Second, being a user of your own product gives you invaluable insight — I was both selling and using Macs then, just like I actively use CellarTracker today. And finally, genuine passion is contagious. My enthusiasm for the Mac resonated with customers, and later, my love for wine and solving a problem I personally faced connected with other collectors. Those principles have been the foundation of everything I’ve built.

Related: I Attended an Ivy League University’s Most Popular MBA Leadership Class and Learned How Steve Jobs Became a Better Leader in 10 Minutes

What’s your best piece of advice for young people who want to start their own business?
Build something you need yourself. CellarTracker started because I had a wine collection problem that needed solving. I wasn’t trying to capitalize on a market trend or build something for someone else. When you’re solving your own problem, you have a deep understanding of what works and what doesn’t, and your passion will sustain you through the inevitable challenges of building a business.

2. Amir Loloi

Loloi, 66, is the Dallas, Texas-based CEO and founder of rug company Loloi.

Image Credit: Courtesy of Loloi. Amir Loloi and his sons, Steven and Cyrus (left to right).

What was your first job?
I moved to Texas from Iran at 16 years old and spoke very little English. I got my first job at Burger King and learned the language while learning customer service. I sold ice cream in an ice cream truck, and my entrepreneurial instincts encouraged me to go further — eventually buying my own ice cream truck.

You should learn so much about what you like to do and get good at it.

What were some of the biggest lessons learned from that first job that helped you succeed as a founder?
No matter what work was given to me, I always did more. Taking every opportunity and exceeding the expectations of that role helped me rise up throughout the course of my life.

What’s your best piece of advice for young people who want to start their own business?
You should learn so much about what you like to do and get good at it. Know that the only way you can be successful is to surround yourself with people who are smarter and stronger than you are to be able to grow your business. Finally, treat people the way you like to be treated.

Related: He Immigrated to the U.S. and Started a Business. It’s ‘Not the Sexiest’ But Sells Over 6,000 Units Daily — Up to $25,000 Apiece — Anyway.

3. Karen Robinovitz

Robinovitz, 53, is the New York City-based co-founder and co-CEO of slime brand and immersive experience Sloomoo Institute.

Image Credit: Courtesy of Sloomoo Institute

What was your first job?
It was 1994, and I was an assistant at Women’s Wear Daily, the fashion and beauty industry’s original trade newspaper that still exists today online.

What were some of the biggest lessons learned from that first job that helped you succeed as a founder?
Like anyone in their first job, I made mistakes, and I still think about those lessons to this day. I can recall a memory of submitting a photo WWD took of George Marciano to The New York Times for syndication. This was pre-Google, pre-high-speed internet, pre-email. I trusted the photo department and didn’t triple-check that it was the right shot before sending it off to the NYT.

The next day or two, the NYT ran the image in the paper…and it was George’s brother, Paul. The NYT had to retract it, WWD had to refund them — and it all came down to me. I was basically read the riot act — and let me tell you — I never let a detail slip by me again! My lesson was to have a double- or triple-checking system in place for any project.

What’s your best piece of advice for young people who want to start their own business?
No one can do it all. Surround yourself with people who are strong in the areas where you are not — and collaborate.

Related: The Startup World Glamorizes Young Founders, But These 4 Women Started Businesses After Age 40 — Leading to Hundreds of Millions of Dollars. Here’s How.

4. Jake Bullock

Bullock, 37, is the Arizona-based co-founder and CEO of THC-infused beverage brand Cann.

Image Credit: Courtesy of Cann

What was your first job?
My first-ever job was mowing lawns.

What were some of the biggest lessons learned from that first job that helped you succeed as a founder?
Mowing lawns can be a daunting task, one that can seem like it will take forever to complete. I learned to just put one foot in front of the other and focus on the next step, versus thinking about the entire effort. This learning is great advice for founders riding a roller coaster of positives and negatives: You have to just put one foot in front of the other and keep moving forward.

What’s your best piece of advice for young people who want to start their own business?
Just start it. You will learn so much from the experience. So often, there is pressure to have the right idea and the right founding team, but you can solve all of those issues if you are full speed ahead doing the thing. If you’re just thinking about it, then you’ll never actually do it.

Related: Everything Is Now Mockable — How to Understand the Rise of Alcohol Alternatives and Adaptogen Drinks

5. Esther Hallam

Hallam, 46, is the Woodstock, New York-based founder of baby formula brand Nara Organics.

Image Credit: Courtesy of Nara Organics

What was your first job?
My first “real” job was when I was 16. I was an office assistant for a consulting firm headquartered in my small town. Every day after school, I supported five partners with various administrative tasks. I remember their database engineer taught me all about structured query language (SQL) databases, and it was a core learning that had a direct impact on my future career as a product manager (though I didn’t know it then).

What were some of the biggest lessons learned from that first job that helped you succeed as a founder?
Learn by helping. I did all the remedial administration work for this company, and I got to really understand how they ran their business by doing invisible tasks. In the same way, I get to know each function of my business by assisting in the grunt work. For example, when we were researching and developing our formula in a lab, I washed the equipment because I was not a scientist. But by washing the equipment, I got to really understand how the manufacturing process worked.

What’s your best piece of advice for young people who want to start their own business?
Just do it, and especially for young people: You have time on your side. You will never be ready, and there will never be a perfect time, which means you’re always ready, and it’s always a perfect time to start. After that, it’s continuously grounded in your integrity, and you enjoy the journey.

6. David Yeom

Yeom, in his 50s, is the Los Angeles, California-based CEO of online invitation company Evite.

Image Credit: Courtesy of Evite

What was your first job?
My first job out of college was at Arthur Andersen in downtown LA, doing audit and tax consulting. My first client engagement? Three days straight of photocopying stacks of documents. It was humbling, grueling work, especially during peak periods when 100-plus-hour weeks were the norm.

Talk to as many people as possible about your ideas.

What lessons from that first job helped you succeed as a business leader?
Despite the long hours, it was incredibly rewarding. I got to work with talented people and fast-growing companies, which was an amazing learning environment. I was shy and nervous about public speaking, but I had to present often — those experiences pushed me out of my comfort zone and built the confidence and character that set me on the path to entrepreneurship.

What’s your best piece of advice for young people who want to start their own business?
The best advice for aspiring entrepreneurs is to talk to as many people as possible about your ideas — especially those who have walked a similar path. Building a business takes a village, and you never know who might become a co-founder, investor or key team member along the way.

Related: I’ve Interviewed Over 100 Entrepreneurs Who Started Businesses Worth $1 Million to $1 Billion or More. Here’s Some of Their Best Advice.

7. Meenakshi Lala

Lala, 45, is the New York City-based CEO of online flower delivery company UrbanStems.

Image Credit: Courtesy of UrbanStems

What was your first job?
My first job was in fashion, and it shaped everything about how I lead today. It was fast, demanding and deeply creative — you had to think on your feet, make decisions quickly and stay incredibly close to the customer.

What lessons from those early roles helped you succeed as a CEO?
Those initial experiences taught me agility, resilience and the importance of balancing creativity with operational discipline — lessons that have stayed with me ever since.

Fashion taught me to move fast but stay intentional and to lead with both instinct and structure. It also taught me to think brand first — every decision, from product to people, should reflect who you are and what you stand for.

Those lessons made UrbanStems a natural next step — a chance to bring that same mix of speed, creativity and purpose to a completely different world.

8. Ben Witte

Witte, 37, is the Los Angeles, California-based founder and co-CEO of relaxation beverage Recess.

Image Credit: Courtesy of Recess

What was your first job?
My first real job was selling Cutco knives, a job that was laser-focused on in-person sales.

What were some of the biggest lessons learned from that first job that helped you succeed as a founder?
While selling knives was not my calling, it taught me how to hustle and make sales. I learned what rejection felt like early on, and amidst the ups and downs of any startup journey, it’s a feeling entrepreneurs are forced to become comfortable with.

What’s your best piece of advice for young people who want to start their own business?
Being told “no” is inevitable, but it’s not a stop sign. That feeling of rejection I learned in my first job used to seem defeating, but as a startup founder, I quickly learned that every “no” is a valuable piece of feedback. Along Recess’s journey, I followed my vision from day one despite any doubt from investors, consumers, etc. — and now we’ve evolved relaxation beverages into a mainstream category.

https://www.entrepreneur.com/starting-a-business/business-leaders-share-lessons-from-first-jobs-success-tips/499653


If Your Sales Are Falling Flat, Steal This Strategy From Shark Tank’s Robert Herjavec

Years ago, Robert Herjavec hired a young sales guy. The kid was smart, professional, and learned everything about the company’s products. But he couldn’t close a deal.

“This kid’s a loser,” his sales manager told Herjavec. “Let’s get him outta here.”

But Herjavec wanted to join a few calls with the kid first. What he observed was telling: The kid did nothing wrong, but he also did nothing to connect with his clients.

So Herjavec gave him some unusual advice: “On your next sales call, I want you to walk in, sit down, don’t say anything for like a minute,” Herjavec told him. “Then look the client in the eye and say, ‘I’m so thankful for you taking this meeting. But I have to be honest, I am so nervous. This is my first sales call.’”

The results were immediate: The kid started closing major deals.

Why? Because he shocked the narrative. It’s one of Herjavec’s greatest sales strategies.

Here’s the problem, he says: In most professional situations, people think they know exactly how things will go. They’re expecting a standardized, predictable experience. Which means they’re mentally checked out before you even begin.

“People don’t really wanna listen to you,” Robert told me. “When you go on a sales call and you sit down and you’re so excited, the client is thinking: How the hell do I get this person to leave?”

In other words: They already have a narrative about how this will go. So to get their attention, you must shock that narrative — to do something so unexpected and genuine that it forces people to look at you anew.

In the case of his young salesman, the strategy appealed to their clients’ emotions. “We are selling to middle-aged men, typically in IT,” Herjavec says. “As soon as that young salesman said he was nervous, our clients all start thinking: ‘He’s like my son. I want to help him.’”

(To be clear, Herjavec says, the performance wasn’t a total lie. The kid really was young and nervous.)

The next time you’re trying to stand out, think about the narrative you might be stuck in. You can start by asking yourself:

1. What are people expecting?

2. How can I go beyond that?

And it’s worth recognizing: The answer may not be what you expect.

For example, Herjavec’s advice to that kid seemed bad! Sales is supposedly all about confidence; who would admit nervousness? But it worked, which goes to show: Even we have narratives about our own work. Before we shock anyone else’s narrative, we must shock our own.

Good is forgettable. Safe is interchangeable. Expected is nothing short of underwhelming.

Shock those narratives. Then tell a better story.

Related: 10 Traits of Successful Entrepreneurs That Investors Love (Even If They Seem Like Jerks)

Years ago, Robert Herjavec hired a young sales guy. The kid was smart, professional, and learned everything about the company’s products. But he couldn’t close a deal.

“This kid’s a loser,” his sales manager told Herjavec. “Let’s get him outta here.”

But Herjavec wanted to join a few calls with the kid first. What he observed was telling: The kid did nothing wrong, but he also did nothing to connect with his clients.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/growing-a-business/steal-this-sales-strategy-from-shark-tanks-robert-herjavec/499731


Why Founders Outside Silicon Valley Have an Advantage

Whether you’re building outside Silicon Valley or just working on an idea that’s unconventional, there’s something about your story that makes you an outsider. George Rzepecki says that for investors like him, that’s not a red flag — it’s a competitive advantage. Rzepecki leads The Raba Partnership, an investment group focused on early-stage technology companies in emerging markets, especially Africa. Here, he shares how founders can sell an investor on an idea — or even an industry — that no one has imagined until now.

You focus on emerging markets. If a founder is outside of Silicon Valley, they might feel like they have a disadvantage. How can they convince investors that being an outsider is actually a superpower?

The first thing that comes to mind is: competition. There’s incredible talent everywhere, but the depth of capital markets is very different across different ecosystems. In places like Silicon Valley, people and capital are in abundance. In our markets — less obvious markets — there’s often too little capital, and very large incumbents that have never been tested by traditional kinds of venture-backed challengers. They’re very profitable, but they’re stagnant, right?

A great example of that is the U.S. airline industry. There’s demand, there’s growth — no one’s going debate that there will be more people flying — but if you look at the entire industry, it erodes to almost no one earning a profit. If you can raise capital and build a formidable early team and go after these incumbents [in less obvious markets], the field really opens up.

In highly competitive ecosystems, if someone sees a company that’s running away with a particular industry, venture capital firms start to fund competitors very, very quickly. But in emerging markets it’s the inverse of that, which is a powerful thing that’s not widely understood by venture investors.

Related: 5 Daily Habits Investors Look For in Founders — and How to Build Them

There tends to be an expectation that emerging markets are riskier. How should founders address that when talking to investors?

Oftentimes, the “more risk” narrative comes from oversimplification. We love dispelling those narratives with actual examples — real businesses built in these markets. When you can show someone a tangible example of what’s possible, it completely changes the course of the dialogue. I think founders would benefit from doing the same, really highlighting the potential. Because it exists, right? You could pick almost any market, any country, and you can find examples of incredibly large businesses. It’s just telling the story, and telling it with data and a depth of understanding.

When it comes to taking on major incumbents, how do you convince investors that you’re the David to take on that particular Goliath?

Be authentic to who you are and how you do things. This is not performative theater. You don’t need to be a version of some “investor ideal.” Every firm has their views of what they like to track or make decisions on. Just be true to thyself. That means you’re not going to be for everyone. And that’s absolutely okay. Find the person who resonates with you.

We’ve covered unconventional markets. But what about unconventional ideas? Some of the most groundbreaking companies had to make investors believe in something that didn’t exist yet. How would you make that argument today?

I firmly believe that most great businesses are modern takes on models that have existed since the Industrial Revolution. I always say to founders and to fellow investors that a really worthwhile investment of time is just studying business history. You can learn from prior cycles, from prior founders and builders. I would argue what’s changed is the toolkit you have. You have software, internet, and now AI as leverage into the business model. So you can now solve problems at scale that were impossible a few years ago. The principles are timeless. It’s the speed and scale of what you can do that’s new today.

Related: Why Investors Need Emotional Strength Just as Much as a Diversified Portfolio

Whether you’re building outside Silicon Valley or just working on an idea that’s unconventional, there’s something about your story that makes you an outsider. George Rzepecki says that for investors like him, that’s not a red flag — it’s a competitive advantage. Rzepecki leads The Raba Partnership, an investment group focused on early-stage technology companies in emerging markets, especially Africa. Here, he shares how founders can sell an investor on an idea — or even an industry — that no one has imagined until now.

You focus on emerging markets. If a founder is outside of Silicon Valley, they might feel like they have a disadvantage. How can they convince investors that being an outsider is actually a superpower?

The first thing that comes to mind is: competition. There’s incredible talent everywhere, but the depth of capital markets is very different across different ecosystems. In places like Silicon Valley, people and capital are in abundance. In our markets — less obvious markets — there’s often too little capital, and very large incumbents that have never been tested by traditional kinds of venture-backed challengers. They’re very profitable, but they’re stagnant, right?

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/growing-a-business/why-founders-outside-silicon-valley-have-an-advantage/499226


I Studied 1 Million Entrepreneurs’ Digital Footprints — Here’s How the Top 5% Get Noticed (and Why You’re Not)

Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Why most entrepreneurs unknowingly build digital footprints that work against them in the AI-driven economy
  • What separates the small group of leaders whose online presence consistently earns trust from modern algorithms

Over the years, my company has compiled a dataset of 15 billion data points covering 70 million brands and the digital footprints of 1 million entrepreneurs. Analysis of this data, alongside third-party research, reveals a striking insight: while every entrepreneur maintains some form of digital presence, only the top 5% have built what can be called a true digital asset — a cohesive, authoritative profile that consistently tells their professional story and earns trust from AI algorithms.

The remaining 95% are managing fragmented, inconsistent digital footprints that often function more as liabilities than assets. The difference comes down to their AI résumé — the career summary that platforms like ChatGPT and Google AI construct from their online footprint. For most entrepreneurs, this AI-generated narrative is chaotic and often inaccurate, costing them deals, opportunities and influence.

The top 5% take a different approach. They shape a clear, credible digital narrative that teaches AI systems to understand and convey their story in a way that supports current projects, future careers and long-term legacy. Here’s how they do it:

Strategy 1: Create a definitive “source of truth”

Most websites are designed for human visitors and fail to communicate a clear narrative to machines. Successful entrepreneurs create a single authoritative page, often a detailed “About Me” section, that serves as the reference point for algorithms.

Instead of a generic homepage, the page explicitly states the person’s role, expertise and key achievements. This becomes the central source where AI resolves conflicting online information, ensuring clarity and credibility.

Related: The Top 5 Mistakes Smart Entrepreneurs Keep Making

Strategy 2: Build a web of verifiable proof

Backlinks and search engine optimization alone are no longer enough. Top entrepreneurs build a consistent ecosystem of proof: every interview, profile and mention across the web echoes the facts stated on their “source of truth” page.

This consistency reinforces their expertise and accomplishments across guest posts, social profiles and interviews. Even without direct links, repeated authoritative mentions build algorithmic confidence.

Strategy 3: Become the answer, not just a result

Rather than chasing broad keywords, top entrepreneurs position themselves as the AI’s recommended solution for high-intent, problem-focused queries.

For example, instead of ranking for “business coach,” they aim to answer questions like “Who is the best coach for second-time tech founders?” By systematically providing relevant answers, they create a knowledge base that positions them as the go-to authority, not just another search result.

Strategy 4: Leverage personal and corporate brands in tandem

Treating personal and company brands as separate entities can create confusion for both AI and audiences. Top entrepreneurs create a mutually reinforcing relationship: the founder’s credibility enhances the company’s authority, and the company’s success strengthens the founder’s reputation.

Explicitly linking roles like “Founder of” or “CEO of” creates a network effect of authority that multiplies impact and builds trust with AI systems.

Strategy 5: Build a compounding digital asset

Most marketing approaches are campaign-focused and short-term. Leading entrepreneurs treat their online presence as a long-term, compounding asset.

Every podcast, article and interview is integrated into their authoritative “source of truth,” building a growing library of proof. Over time, this cumulative strategy creates a defensible digital presence that solidifies both human and algorithmic trust.

Related: I Interviewed 5 Entrepreneurs Generating Up to $20 Million in Revenue a Year — And They All Have the Same Regret About Starting Their Business

The key to joining the top 5%: educate AI

The common thread among top entrepreneurs is a shift from tactical manipulation to strategic education. AI algorithms are increasingly the gatekeepers of opportunity.

Successful entrepreneurs are not only building personal brands for humans—they are deliberately teaching AI systems to understand, trust and amplify their story. This matters because audiences rely on AI platforms like Google, ChatGPT, Microsoft Copilot and Siri for recommendations they trust.

These AI platforms engage in trillions of daily interactions, shaping decisions for billions of people. Entrepreneurs who proactively educate these systems gain a decisive advantage.

In today’s economy, controlling how and where you appear in AI systems is one of the most important competitive edges. The top 5% of entrepreneurs are already leveraging this insight. Over time, they will not just be ahead—they will be difficult to catch.

Key Takeaways

  • Why most entrepreneurs unknowingly build digital footprints that work against them in the AI-driven economy
  • What separates the small group of leaders whose online presence consistently earns trust from modern algorithms

Over the years, my company has compiled a dataset of 15 billion data points covering 70 million brands and the digital footprints of 1 million entrepreneurs. Analysis of this data, alongside third-party research, reveals a striking insight: while every entrepreneur maintains some form of digital presence, only the top 5% have built what can be called a true digital asset — a cohesive, authoritative profile that consistently tells their professional story and earns trust from AI algorithms.

The remaining 95% are managing fragmented, inconsistent digital footprints that often function more as liabilities than assets. The difference comes down to their AI résumé — the career summary that platforms like ChatGPT and Google AI construct from their online footprint. For most entrepreneurs, this AI-generated narrative is chaotic and often inaccurate, costing them deals, opportunities and influence.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/starting-a-business/i-studied-1-million-entrepreneurs-digital-footprints/497712


Adopt This Tiny Habit to Turn Your Team Into a Breakthrough Machine

Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Discover why the most successful companies treat curiosity like a system, not just a buzzword.
  • Learn how a simple shift in how your team explores, experiments and tests ideas can change the game.

The most valuable asset in any company isn’t a product, a dataset or even a brilliant strategy — it’s the willingness to stay curious. And I don’t mean curiosity as a vague value. I mean structured, operationalized curiosity. The kind that shapes your roadmap, your culture and your edge in the market.

Several years ago, Harvard Business Review published “The Business Case for Curiosity,” citing that curiosity increased creativity and delivered other workplace improvements exponentially. This hasn’t changed. New data from 2025 reinforces the concept, showing that curiosity isn’t just nice to have; it pays off, especially when it’s baked into how a company works.

Execution speed matters, but it’s your ability to explore, test and adjust (curiously) that keeps you sharp. The reality is, you have to constantly reevaluate everything. Technology is moving so fast it’ll drive you crazy: something you spent $2 million on last year might be offered for free from OpenAI this weekend. That’s why staying curious is now simply a survival mechanism.

Related: Are You Asking the Right Questions as a Leader? How Curiosity and Intelligence Gathering Drive Organizational Success

Why founders need to formalize curiosity

The reality is, most teams are too busy executing to experiment. That’s a problem. You can’t learn anything new if your calendar is wall-to-wall delivery. You can’t innovate if there’s no space to ask “what if?”

If you’re a founder, this means one thing: curiosity has to be designed into your company, not just encouraged. It needs airtime. It needs ownership. And it needs to be safe to fail.

Take a page from Google’s old playbook. At one point, they allowed employees to dedicate 20% of their time to side projects. No immediate ROI required. Just space to chase an idea. Some of Google’s biggest products came out of that structure, not in spite of it.

I’ve talked to too many leaders who claim they want bold thinking but punish anything that doesn’t lead directly to ROI. That’s a great way to kill original thought. The companies that learn fast are the ones that treat curiosity like a system, not a slogan.

What structured experimentation looks like

I’m not talking about a strategy that requires a massive budget or an org-wide operational shift. I’m talking about carving out regular time to explore, test, debrief, and tinker. Run short sprints toward innovation, play out “what if” scenarios, and give your team the freedom to build things just to see what happens.

That might look like a “What We Tried” Slack channel. A recurring “disruption hour” on Fridays. A policy where 10% of the time is protected for side projects. Whatever format works, the important thing is to give curiosity a container—and make it safe to experiment without the pressure of instant ROI.

Some companies formalize this even further. A study in the Global Journal of Business Management found that organizations that track curiosity-based KPIs — things like innovation output, employee engagement and efficiency — see measurable business impact. Formal or informal, the point is the same: make space for experimentation, and build feedback loops so those discoveries plug back into the business.

Why curiosity and AI are now inseparable

Right now, the most powerful curiosity lab in your business is AI.

New tools are launching daily, and the companies that win aren’t the ones with the most AI experts — they’re the ones who stay curious enough to try, test, and adapt fast. You don’t need to be a prompt engineer to experiment. You just need a bias toward exploration.

At my own company, we run monthly “AI Days” — no agenda, no pressure, just hands-on time with new tools. Sometimes we build something brilliant. Sometimes we break stuff. Either way, we learn. That’s the point.

AI is a moving target. A tool you ignore today might disrupt your workflow tomorrow. That’s why structured curiosity matters more than ever — it gives your team permission to poke around, push buttons and find breakthroughs early.

But this isn’t just about tech. Curiosity can spark change across the board: a better onboarding flow, a smarter sales play, a new market insight. AI just happens to be today’s fastest-moving arena for that kind of thinking.

Related: 5 Daily Habits Investors Look For in Founders — and How to Build Them

The mindset that moves the needle

The truth is, this does take extra work. You’re probably going to have to carve out time you don’t really have. You might end up doing all your usual stuff plus making room for experimentation. But it’s worth it. This mindset of staying curious, running little experiments, not gripping the wheel too tight is how you get to the big stuff: operational efficiencies, new ways to serve customers, smarter ways to sell.

This is all about getting real wins. The teams that make space for curiosity are the ones who find better ways to work: automating tasks, uncovering new revenue streams and tightening up operations. They’re the ones who spot an insight early and move faster because of it. You want to make a business case? Start by showing how a few hours of structured exploration led to something tangible: more efficiency, a faster launch, a smarter pitch. That’s what gets noticed and compounds success.

Don’t be curious “just because.” When you have a culture of curiosity, you will uncover the clues to solve the real problems. It’s how you will spot something no one else saw. That only happens when you’re in it: playing around, pushing weird buttons, messing with new tools and seeing what happens.

You’re going to have to sacrifice a little bit. But six, nine months from now, that time you protected is going to pay off, big time. You’ve just got to make space for it now.

Key Takeaways

  • Discover why the most successful companies treat curiosity like a system, not just a buzzword.
  • Learn how a simple shift in how your team explores, experiments and tests ideas can change the game.

The most valuable asset in any company isn’t a product, a dataset or even a brilliant strategy — it’s the willingness to stay curious. And I don’t mean curiosity as a vague value. I mean structured, operationalized curiosity. The kind that shapes your roadmap, your culture and your edge in the market.

Several years ago, Harvard Business Review published “The Business Case for Curiosity,” citing that curiosity increased creativity and delivered other workplace improvements exponentially. This hasn’t changed. New data from 2025 reinforces the concept, showing that curiosity isn’t just nice to have; it pays off, especially when it’s baked into how a company works.

Execution speed matters, but it’s your ability to explore, test and adjust (curiously) that keeps you sharp. The reality is, you have to constantly reevaluate everything. Technology is moving so fast it’ll drive you crazy: something you spent $2 million on last year might be offered for free from OpenAI this weekend. That’s why staying curious is now simply a survival mechanism.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/leadership/adopt-this-tiny-habit-to-turn-your-team-into-a-breakthrough/496740


The ‘Godmother of AI’ Says Young Workers Are Making a Common Career Mistake

Key Takeaways

  • Dr. Fei-Fei Li is widely recognized as the “godmother of AI” due to her pioneering work in inventing the AI image dataset ImageNet.
  • Li said on a podcast recently that many young people she encounters overthink the small details when they decide on jobs.
  • She encouraged young people to focus on the fundamentals, like their passion and belief in a company, when deciding where to work.

Young professionals are making a common mistake by overthinking every detail when they decide on jobs, says the “godmother of AI.”

Dr. Fei-Fei Li, a Stanford computer science professor, is widely regarded as the godmother of AI due to her pioneering work in inventing the AI image dataset ImageNet. Li started developing ImageNet in 2006 based on the idea that teaching machines to recognize images would require large amounts of data. The ImageNet database now holds more than 14 million annotated images and has been used to train countless computer vision models.

On an episode of Lenny’s Podcast released on Sunday, Li said that many young people she encounters “think about every single aspect of an equation when they decide on jobs.” These early-career professionals get trapped in the small details of a job instead of making decisions based on their passion and belief in a company.

“Sometimes I do want to encourage young people to focus on what’s important,” Li said on the podcast.

Related: Looking for a Job? Mark Cuban Has Some Simple Advice for You.

She said that she sees young people “overfocusing on every minute decision” instead of letting themselves be guided by the answers to more fundamental questions, like “Where’s your passion? Do you align with the mission? Do you believe and have faith in this team?”

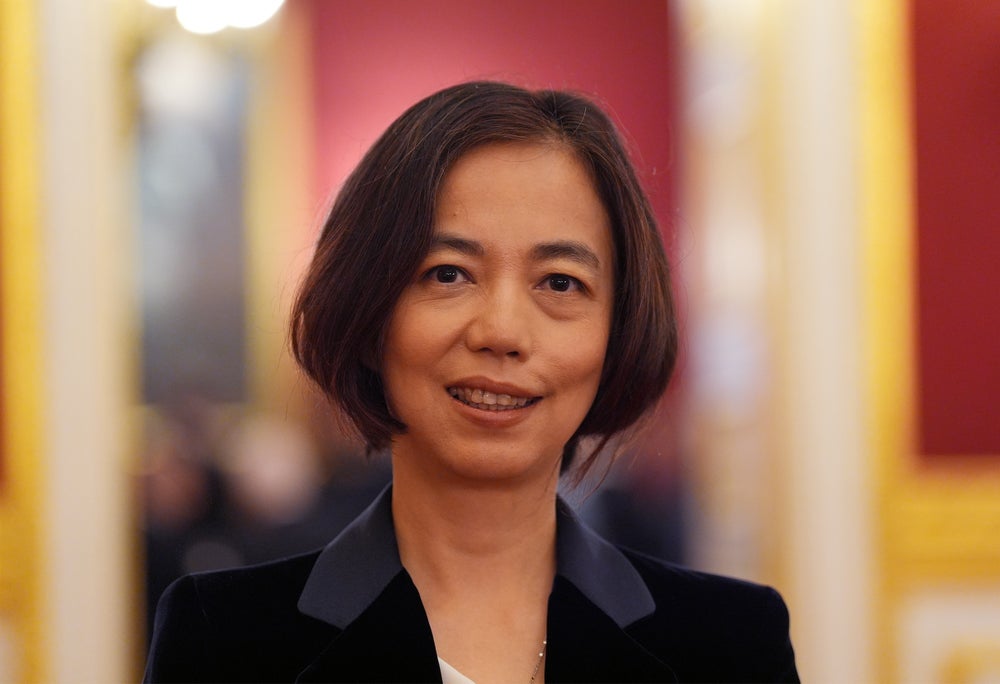
Dr. Fei-Fei Li. Photo by Yui Mok – Pool/Getty Images

Li remains on the cutting-edge of AI. Last year, she co-founded World Labs, a spatial intelligence company building AI models that can generate 3D environments. The startup’s first product is an AI generator called Marble that creates 3D worlds from text prompts.

Li said on the podcast that it is a privilege to receive job applications from workers who want to join World Labs. She urges professionals to “focus on the impact” they can make and the kind of work they will be doing when deciding where to work.

Related: These 3 Common Mistakes Are Holding You Back at Work, According to a Former Meta Engineer Known as the ‘Coding Machine’

Li said that she is fearless when it comes to intellectual pursuits, a quality that she looks for in the people she hires.

“I’m an intellectually very fearless person, and I have to say, when I hire young people, I look for that because I think that’s a very important quality,” she said on the podcast. “You almost have to allow yourself to be fearless and to be courageous.”

She brought up the example of how, early in her career, she was close to obtaining tenure as a professor at Princeton University. However, in 2009, she chose to make the leap from Princeton to Stanford University and restart her tenure clock because she was drawn to the Silicon Valley ecosystem. Li has now been working at Stanford for over 16 years.

“I didn’t spend too much time thinking about all the failure cases,” Li said on the podcast. “I don’t overthink.”

Key Takeaways

  • Dr. Fei-Fei Li is widely recognized as the “godmother of AI” due to her pioneering work in inventing the AI image dataset ImageNet.
  • Li said on a podcast recently that many young people she encounters overthink the small details when they decide on jobs.
  • She encouraged young people to focus on the fundamentals, like their passion and belief in a company, when deciding where to work.

Young professionals are making a common mistake by overthinking every detail when they decide on jobs, says the “godmother of AI.”

Dr. Fei-Fei Li, a Stanford computer science professor, is widely regarded as the godmother of AI due to her pioneering work in inventing the AI image dataset ImageNet. Li started developing ImageNet in 2006 based on the idea that teaching machines to recognize images would require large amounts of data. The ImageNet database now holds more than 14 million annotated images and has been used to train countless computer vision models.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/business-news/godmother-of-ai-young-workers-are-making-a-common-mistake/499728


5 Ways You Can Lower Your Company’s Healthcare Costs in 2026

Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Small business owners are facing rapidly rising healthcare costs and need creative strategies to stay competitive without breaking the bank.
  • Navigating healthcare options is more complex than ever, and understanding the system can make a major difference for both employers and employees.

According to a recent study from Aon, the average employer health insurance cost is expected to surpass $17,000 per employee in 2026, a 9.5% jump from 2025.

There’s no debate that healthcare costs are dramatically increasing. And yet, as small business owners, you and I need to provide some sort of healthcare benefit in order to remain competitive with our larger competitors so that we can attract and retain the best talent possible. How to do this? Here are five strategies.

Related: Employee Benefit Costs Are Increasing. It’s Time for Employers to Fight Back.

1. Level-funded plans

Self-insuring was once only a choice for the largest of companies. But newer arrangements are beginning to filter down to small and mid-sized businesses. One of these options is a level-funded (or benefit) plan. Simply stated, this type of plan means your business funds the cost of health insurance at the lowest level — out-of-pocket costs, doctor’s visits, routine treatments — up to a certain amount, and then a stop-loss plan kicks in to cover any catastrophic costs like surgery or expensive treatments.

These plans are on the rise. Another report from Kaiser Family Foundation indicated that among small employers, the share of offering level-funded plans jumped from about 13% in 2020 to roughly 40% in 2023. The reason why is that many business owners have realized that not all of their employees — particularly younger or healthier workers — are fully using the group insurance plans they’re helping to pay. With a plan like this, you’re only paying for when healthcare is needed. These plans do come with risks, such as the potential for unpredictable claims, continued renewals from insurance companies and administrative complexity. But administered properly, they can go a long way towards better controlling healthcare costs.

2. Health Reimbursement Arrangements (HRAs)

These types of plans come in various forms, like a Qualified Small Employer HRA (QSEHRA) or the Individual Coverage HRA (ICHRA). You can have an HRA in addition to or instead of your existing healthcare plans. With an HRA, you’re contributing money (that is not taxed) to your employees’ accounts and basically telling them to use these funds to buy their own healthcare. They can go to the healthcare exchanges or to a list of brokers that you provide. Your business also gets a tax deduction for this contribution.

Employers like these plans because they give them more control over their costs (you contribute what you can afford, rather than what the health insurance company is demanding), reduce your administrative time (these plans are generally administered by an outside party) and take you out of the healthcare conversation, where you risk potential liabilities over privacy concerns. HRA plans have been very popular. A recent report found that ICHRA adoption alone grew approximately 29% from 2023 to 2024.

3. Health Savings Accounts (HSA)

If you already have a high deductible plan, you can stick with it — or even increase the deductible to make it more affordable — but couple it with an HSA. Assets in HSA plans have reached nearly $147 billion across over 39 million accounts at the end of 2024.

With an HSA, employees can contribute up to $4,400 ($8,750 for families) in 2026 of their pre-tax income, thereby lowering their tax liabilities. Then they can take the money out to use for unreimbursed healthcare costs, including doctors’ visits, fertility treatments and physical therapy. Amounts can be invested with various options and also grow tax-free. Distributions are also not taxed, and there’s no minimum distribution requirement like a retirement plan.

Different than a “use-it-or-lose-it” plan — balances rollover every year, and if an employee leaves your company, they can take their HSA money with them. HSAs are like a 401(K) retirement plan for your healthcare. Used the right way, these accounts can build up a significant nest egg with funds that would be used in the future for healthcare expenses at a time when they’re needed the most.

Related: 90% of Execs Say Providing Employee Health Benefits Will Be Unsustainable By 2030 — Here’s One Solution Businesses Need to Consider

4. SHOP

I don’t mean shop around. I mean SHOP — the Small Business Health Options Program. If your business qualifies (generally you have less than 50 full time employees, offer healthcare and dental care, contribute to your employees plan and have a minimum participation rate, among other rules), then you can get access to healthcare plans on a special marketplace setup on your state’s (or the federal) healthcare exchange with potentially more competitive rates than what you’re getting elsewhere. There are also tax credits available for certain eligible small businesses. More information about the SHOP exchange is here.

5. Education

Level Funded Plans. Captive Programs. Deductibles. In-network. Out of network. Concierge medical services. Out-of-pocket expenses. Co-payment. Co-insurance. Benefit advisors. Insurance brokers. Healthcare consultants. ACA. HMO. PPO. EPO. POS. HDHP. HSA. FSA. HRA. EOB. COBRA. SHOP. Single Coverage. Dependent Coverage. Premium tax credits.

Do you truly understand all of this? If you do, good for you. But you’re in the minority. Most business owners I know (myself included) find it very challenging to get our arms around all the complexities (and craziness) of the American healthcare system. Our employees are no different, which is why we all need continuous education. Some of my smarter clients partner with competent benefit advisors and require them to come in quarterly – yes, quarterly, not just at renewal time- to discuss healthcare options and strategies with their employees.

Why? Because the more people know, the better decisions they make. Maybe some can go on Medicare. Or others will find it more cost-effective to get their insurance from a healthcare exchange. At the very least, they’ll be able to be smarter about their healthcare choices and options. These decisions can ultimately lower their healthcare costs. And perhaps yours too.

Yes, healthcare costs are increasing, and there’s no silver bullet for saving money on healthcare. It’s usually by doing a number of things. But implementing some of the above strategies will absolutely help.

Key Takeaways

  • Small business owners are facing rapidly rising healthcare costs and need creative strategies to stay competitive without breaking the bank.
  • Navigating healthcare options is more complex than ever, and understanding the system can make a major difference for both employers and employees.

According to a recent study from Aon, the average employer health insurance cost is expected to surpass $17,000 per employee in 2026, a 9.5% jump from 2025.

There’s no debate that healthcare costs are dramatically increasing. And yet, as small business owners, you and I need to provide some sort of healthcare benefit in order to remain competitive with our larger competitors so that we can attract and retain the best talent possible. How to do this? Here are five strategies.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/growing-a-business/5-ways-you-can-lower-your-companys-healthcare-costs-in-2026/499276


Built to Last: Why Human-Centered Businesses Will Flourish in the Age of AI

As artificial intelligence (AI) transforms industries and disrupts traditional business models, a crucial question arises: Which franchise opportunities and small-business investments are built to endure?

Join us for an insightful discussion with Nick Friedman, co-founder and president of College Hunks Hauling Junk & Moving®, as we explore why human-centered, service-based, and labor-intensive businesses are thriving in the AI era — and how franchise investors can position themselves for long-term success.

What you’ll learn

Current AI disruptions: Identify which industries are being affected by AI today and which ones remain strong. Explore where automation is creating risks — and which recession-resistant franchise models remain profitable.

Resilience of service-based businesses: Understand why hands-on services like junk hauling and moving are less susceptible to automation. These essential, people-powered, automation-resistant franchises represent some of the best low-tech business opportunities to own in the next decade.

Integrating AI with a human touch: Discover practical methods successful franchises use to incorporate technology without losing the authenticity and personal connection that drive loyalty. Learn how smart franchise owners leverage AI tools while protecting the customer relationships that create repeat business and referrals.

Franchise benefits in an AI economy: Learn what sets labor-focused, purpose-driven franchise models apart for long-term prosperity compared to digital-only or tech-heavy ventures. Understand how investing in a scalable, service-based franchise can outperform purely online business concepts in today’s marketplace.

Culture as a competitive advantage: Delve into how emotional intelligence, empathy, and people-first leadership create cultures that technology cannot replicate. See how College Hunks Hauling Junk & Moving combines strong values with high-growth potential in a rapidly changing world.

“Four Fs” framework for franchise success: Friedman will also share his effective roadmap for investors evaluating franchise ownership options and provide insight into new legislation shaping the future of work.

Who should attend

This live webinar is ideal for:

  • Entrepreneurs exploring AI-resistant franchise opportunities
  • Business leaders adapting to technological disruption
  • Corporate professionals seeking to transition into purpose-driven business ownership
  • Investors looking for sustainable, human-centered, community-focused business models

If you’re evaluating franchise opportunities that align profit with purpose, this session will help you understand why people-first brands continue to outperform in an AI-driven economy.

Reserve your spot today

Find out why the most resilient businesses in the age of AI prioritize humanity. The Built to Last: Why Human-Centered Businesses Will Flourish in the Age of AI webinar will take place live on Tuesday January 20 at 12 p.m. ET | 9 a.m. PT.

Reserve your spot today to discover why service-based franchises like College Hunks Hauling Junk & Moving are proving to be among the most recession-resistant, high-demand investments for the years ahead.

The session will be moderated by Business Development Consultant Terry Rice, ensuring there’s ample time to address your questions live.

As artificial intelligence (AI) transforms industries and disrupts traditional business models, a crucial question arises: Which franchise opportunities and small-business investments are built to endure?

Join us for an insightful discussion with Nick Friedman, co-founder and president of College Hunks Hauling Junk & Moving®, as we explore why human-centered, service-based, and labor-intensive businesses are thriving in the AI era — and how franchise investors can position themselves for long-term success.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/franchises/built-to-last-why-human-centered-businesses-will-flourish/499601


The Unbeatable Power of Storytelling in Today’s AI-Driven World

Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Storytelling translates data into meaning. Leaders must translate analytics, forecasts and projections into a narrative that team members, investors and partners can believe in.
  • Empathy and trust-building remain irreplaceable. The trust that closes deals emerges from emotional cues like tone, eye contact, listening, follow-up and authenticity.
  • Vision, culture and relationships are your domain. Block weekly time in your calendar to revisit your story, shape culture and invest in relationships only humans can sustain.
  • Balance tech fluency with human authenticity. When deploying AI tools or releasing content, always clarify who is behind it.

In January 2025, McKinsey & Company found that almost all companies are investing in AI, but only 1% believe they have reached maturity in using it meaningfully. That gap between adoption and impact captures the tension at the heart of leadership today: Automation can handle many tasks, but the human skills of persuasion, trust-building and narrative still decide who wins the deal.

AI may write the first draft, summarize the report or optimize workflow. But it can’t feel the room, tell a compelling story or crack open a narrative that connects to shared values. For entrepreneurs and executives, the mission is clear: Use AI to free capacity, not hollow your role.

Below are five ways storytelling remains indispensable and how leaders can wield it in an AI-enabled world.

Related: 10 Storytelling Strategies That Make Startups Impossible to Ignore

1. Storytelling translates data into meaning

Raw numbers impress, but stories persuade. Even in boardrooms, decisions aren’t made by SQL outputs alone. Leaders must translate analytics, forecasts and projections into a narrative that team members, investors and partners can follow and believe in.

Research from MIT’s Sloan Review highlights that generative AI can surface insights, but real power lies in crafting nuanced data stories that address skepticism, complexity and context — something algorithms can’t fully automate.

LTV.ai, a marketing startup, recently raised $5.2 million in Series A by combining AI’s personalization data with a narrative about empathy, retention and the long game. They didn’t just show churn graphs; they told how that churn represented real people slipping away.

Tip: Whenever you present numbers, wrap them in human stakes or tension. Who is affected? What’s the trade-off? That emotional anchor helps people remember and rally.

2. Empathy and trust-building remain irreplaceable

People buy from people they feel. AI can automate outreach, draft emails or personalize pitches — but the trust that closes deals emerges from emotional cues: tone, eye contact, listening, follow-up, apologies, authenticity.

A 2024 study by IDC found that 92% of AI users surveyed use it to improve productivity, yet the main barrier to adoption is a lack of soft skills to communicate AI’s value to organizations.

A recent Business Insider piece revealed that Perplexity’s CEO has abandoned slide decks altogether, choosing instead to pitch investors via AI-generated memos supplemented by live Q&A.

That shift signals a broader reality: AI can streamline processes, but humans still close the deal. Technology handles the mechanical. Leaders must still persuade, build trust and tell stories that unite vision and meaning.

Tip: Don’t let AI handle your investor-facing communications end to end. Add handwritten notes, ask patient questions and follow up in ways that humans notice. The credibility compound is real.

Related: Why Storytelling (Not Selling) Is Your Most Powerful Branding Tool

3. Vision, culture and relationships are your domain

AI handles tasks; leaders handle meaning. Automation frees executives from repetitive work — scheduling, summarization, first drafts — but it also frees up headspace to cultivate the intangible elements that define legacy: vision, culture, loyalty, reputation.

McKinsey’s State of AI 2025 finds that companies achieving bottom-line impact align AI investment with governance, change management and senior-level oversight, not just technical deployments. While the aforementioned Perplexity leans on its AI core, it’s simultaneously striking deals with media firms such as Le Monde to integrate legitimate content and build trust in its storytelling. That’s not data engineering — it’s narrative engineering.

Tip: Block weekly “narrative time” in your calendar. Use it to revisit your story, proactively shape culture and invest in relationships that only humans can sustain.

4. Storytelling wins in high-ambiguity arenas (fundraising, negotiations)

When facts fall short, narrative fills the gap. In high-stakes negotiations or fundraising, parties look for belief, commitment and credibility (not just spreadsheets). The story you tell about your future trajectory, how you’ll respond to threats and who you are behind the plan often decides success.

A September 2025 report by Boston Consulting Group revealed that across 1,250 global firms, only 5% are generating measurable value from their AI investments, meaning most are still early in the maturity curve. In that uncertain zone, narrative becomes the bridge between what’s known and what’s possible.

In 2025, Alice.Tech, an AI-driven edtech startup based in Copenhagen, raised $4.8 million in a seed round by pairing its algorithmic promise with a powerful narrative about accessibility and personalized learning. Investors responded not just to the AI backend but to the story of students overcoming educational inequity through tech.

Tip: Prepare your “why narrative” alongside the business model. Practice telling your story in 60 seconds and in five minutes, each suited for different conversational contexts.

Related: How to Harness the Power of Authentic Storytelling to Become a More Effective and Inspiring Leader

5. Balance tech fluency with human authenticity

In the AI era, fluency in models, APIs and prompt engineering is table stakes. But what separates leaders who thrive is the ability to connect that fluency with emotional truth and human voice.

A Harvard Business Review study from 2024 revealed something revealing: Employees, even when mistaken, rated CEO messages as less credible if they thought they were AI-generated. That perception gap shows how powerful human authenticity still is.

Vimeo offers a real-world example. CEO Philip Moyer has emphasized that as Vimeo builds AI tools for content and editing, the company will continue to highlight “human creator credits” so that every piece of content signals “yes, a person made this.” That narrative positioning helps Vimeo stand out in a landscape crowded with generative noise.

Tip: When deploying AI tools or releasing content, always clarify who is behind it. That extra layer of human context preserves trust and keeps your voice distinct even when machines are doing the heavy lifting.

Undoubtedly, AI is transforming how business is done. But it won’t outperform the “why” behind what you do. Algorithmic efficiency may create opportunity, but only humans craft stories that inspire, empathize and move people. The machines can build the scaffolding, but leaders must build the architecture of belief.

In the age of AI, mastery of narrative, trust and emotional authority will define not just who survives, but who thrives.

Key Takeaways

  • Storytelling translates data into meaning. Leaders must translate analytics, forecasts and projections into a narrative that team members, investors and partners can believe in.
  • Empathy and trust-building remain irreplaceable. The trust that closes deals emerges from emotional cues like tone, eye contact, listening, follow-up and authenticity.
  • Vision, culture and relationships are your domain. Block weekly time in your calendar to revisit your story, shape culture and invest in relationships only humans can sustain.
  • Balance tech fluency with human authenticity. When deploying AI tools or releasing content, always clarify who is behind it.

In January 2025, McKinsey & Company found that almost all companies are investing in AI, but only 1% believe they have reached maturity in using it meaningfully. That gap between adoption and impact captures the tension at the heart of leadership today: Automation can handle many tasks, but the human skills of persuasion, trust-building and narrative still decide who wins the deal.

AI may write the first draft, summarize the report or optimize workflow. But it can’t feel the room, tell a compelling story or crack open a narrative that connects to shared values. For entrepreneurs and executives, the mission is clear: Use AI to free capacity, not hollow your role.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/science-technology/why-storytelling-matters-more-than-ever-in-the-age-of-ai/499240


This Animal-Lover’s Side Hustle Led to $10 Million a Year: ‘Stars Aligned’

Key Takeaways

  • Sternlieb spent nights and weekends researching the business idea that would become her pet wellness brand.
  • Meeting with other business owners and asking questions was an invaluable part of the process.
  • Now, Under the Weather is seeing $10 million in annual sales and “generating significant growth.”

This Side Hustle Spotlight Q&A features Kyla Sternlieb, 52, of Williston, Vermont. Sterlieb is the founder of pet wellness brand Under the Weather. Responses have been edited for length and clarity.

Image Credit: Courtesy of Under the Weather. Kyla Sternlieb.

Want to read more stories like this? Subscribe to Money Makers, our free newsletter packed with creative side hustle ideas and successful strategies. Sign up here.

What was your day job or primary occupation when you started your side hustle?
I was a founder/partner at a fundraising firm called Giving Tree. We helped nonprofits achieve their fundraising and board management goals.

Related: This Rapper’s Non-Musical Side Hustle Led to $100k a Month — Then 8 Figures

When did you start your side hustle, and where did you find the inspiration for it?
Entrepreneurship is like a piece of sand in an oyster. Once an idea takes form inside your mind, it will irritate you endlessly until you wake up one day and decide your life is about to take a drastic turn. For me, that idea hatched one very hot August day in 2012 when my dog, Ruffy, was sick, and the vet told me I had to cook her the common bland diet of chicken and rice. Knowing it was far too hot to hit the grocery store on my drive home with her in my car, I realized just how often vets tell people to cook this diet and what an inconvenience it is. Especially when you have a sick dog and a busy life. There had to be an easier way!

I enjoyed my job as a fundraiser and working for nonprofits in and around the state of Vermont, but I never truly loved it. There was always something missing. After many months of careful research, I realized I had something special. Suddenly, the stars aligned, and the proverbial pearl was born.

Image Credit: Courtesy of Under the Weather

Nothing is more important than surrounding yourself with people who have been there before.

What were some of the first steps you took to get your side hustle off the ground?
In the very beginning, I spent my nights and weekends carefully researching the pet space and deciding if there was actually a need for what I wanted to create. This entailed reading countless articles, perusing pet products online and on shelves, walking trade shows and studying the competition.

Once I decided there was, in fact, a need, I had to pick a name and design my logo. Aside from the airfare to the trade shows and the lawyer fees to help me find a name that wasn’t already trademarked, the initial costs were very manageable.

Are there any free or paid resources that have been especially helpful for you in starting and running this business?
For me, the best free resource was meeting with other business owners and asking questions. Nothing is more important than surrounding yourself with people who have been there before. Being in Vermont, I feel very lucky. Burlington is a small town, but it has some very famous brands, so there were plenty of talented people I could learn from and eventually hire.

Related: Starbucks Barista’s ‘Stealth Mode’ Side Hustle Now Sees $1 Million Months

If you could go back in your business journey and change one process or approach, what would it be, and how do you wish you’d done it differently?
If you plan on doing your own warehouse and shipping, find a space big enough to grow into. Sublet part of your space if you have to. If your business is successful, you will outgrow your space yearly, and moving is very disruptive.

Image Credit: Courtesy of Under the Weather

When it comes to this specific business, what is something you’ve found particularly challenging and/or surprising that people who get into this type of work should be prepared for, but likely aren’t?
To be a very successful brand, you can’t have just one product. I thought my chicken and rice and other variations of bland diets were actually a business. I was wrong. You need a full health and wellness line across both cat and dog for most larger chains and distributors to partner with you.

These new products must be launched yearly, be innovative and be better than what is currently out there. Under the Weather specializes in bland diets as well as soft chews, powders and gels across all health categories.

With sales doubling year over year comes a whole new set of challenges. Warehousing, trucking, inventory, staff increases and competition! Once your ideas become products and your competitors see your products take off, you have fast followers, and companies, some much bigger than you, will create similar products.

Related: This 29-Year-Old Quit Her Job to Pursue a $13k-a-Month Side Hustle

We put every dollar of revenue back into the business.

Can you recall a specific instance when something went very wrong? How did you fix it?
Over the years, we have faced many supply chain issues. During the pandemic, it was chicken and beef. The war in Ukraine created a shortage of sunflower oil, which is an essential ingredient in soft chews. The tariffs raised our packaging prices. There was a pumpkin blight once along the way that kept me awake at night. You fix these issues by watching the economy closely to help predict these disruptions and calibrate your inventory levels accordingly.

How long did it take you to see consistent monthly revenue?
From the day we officially launched in 2016 at the Global Pet Trade Show in Orlando, Florida, we have been seeing consistent and increasing monthly revenues. That said, we put every dollar of revenue back into the business, which is still true today.

We are at $10 million in annual sales and generating significant growth.

I realized early on that we aren’t just a pet company.

What do you enjoy most about running this business?
I have been an animal-lover my whole life. I have fostered and adopted many dogs and also served on the board of the local humane society. Not only are we helping pets, but we are also helping their owners. Some of our products are designed to help animals that might not be eating, facing cancer or simply growing very old.

Our team at Under the Weather is built of animal-lovers, and we know that having a sick dog or cat can be devastating. Our customer service team doesn’t just deal with product questions. They deal with some people who are very scared and call or email us seeking relief for their beloved pet. I realized early on that we aren’t just a pet company. We know at the end of the day that by helping one pet, we are helping that pet’s human, too. Hence our tagline: Healthy Pet, Happy Home.

Related: My Business Tapped Into a Misunderstood Market and Made $760,000 in Year 1

What is your best piece of specific, actionable business advice?
Find the right manufacturer to grow with — one that will let you place small orders to start. There will be mistakes in the beginning, so always choose the smallest quantities when ordering products or packaging.

If you plan to sell on Amazon, pay attention to the Amazon fees because they are based on weight and dimensions, which should influence your product development and packaging designs.

Key Takeaways

  • Sternlieb spent nights and weekends researching the business idea that would become her pet wellness brand.
  • Meeting with other business owners and asking questions was an invaluable part of the process.
  • Now, Under the Weather is seeing $10 million in annual sales and “generating significant growth.”

This Side Hustle Spotlight Q&A features Kyla Sternlieb, 52, of Williston, Vermont. Sterlieb is the founder of pet wellness brand Under the Weather. Responses have been edited for length and clarity.

Image Credit: Courtesy of Under the Weather. Kyla Sternlieb.

Want to read more stories like this? Subscribe to Money Makers, our free newsletter packed with creative side hustle ideas and successful strategies. Sign up here.

The rest of this article is locked.

Join Entrepreneur+ today for access.

https://www.entrepreneur.com/starting-a-business/this-animal-lovers-side-hustle-now-makes-10-million-a-year/499727