Is Rivian Stock a Bargain for Under $20?

Auto stock Rivian Automotive (RIVN) has recently gained traction. However, the company missed its 2022 production estimates and also announced layoffs. So, let’s find out if RIVN is a bargain for under $20.

Auto stock Rivian Automotive, Inc. (RIVN) missed its vehicle production target for 2022. It produced 24,337 vehicles, down 2.7% from its established target of 25,000. Moreover, the company revoked its plan to make electric vans in Europe with Mercedes-Benz only three months post-agreement.

In addition, RIVN’s CEO RJ Scaringe recently declared the company’s decision to lay off 6% of its workforce to conserve cash. Amid this rough patch, RIVN has lost 71.7% over the past year to close the last trading session at $19.71. It has lost 43.4% over the past three months. However, the stock has gained 7% over the past month.

While its forward Price/Book of 1.25x is 58.7% lower than the industry average of 3.04x, its forward Price/Sales of 10.41x compares with the industry average of 0.97x. Moreover, its forward EV/Sales of 3.81x is 205.1% higher than the industry average of 1.25x.

Here is what could shape RIVN’s performance in the near term:

Increasing Losses and Declining Cash Balance

RIVN’s loss from operations came in at $1.77 billion for the third quarter that ended September 30, 2022, up 128.6% year-over-year. Its adjusted net loss increased 85.2% year-over-year to $1.44 billion.

Moreover, its cash and cash equivalents came in at $13.27 billion for the period ended September 30, 2022, compared to $18.13 billion for the period ended December 31, 2021.

Weak EPS Estimates

RIVN’s EPS is expected to decrease 10.5% year-over-year to negative $1.58 for the quarter ending March 2023. Its EPS is estimated to remain negative in 2023. In addition, its EPS is expected to fall 31.7% per annum for the next five years.

Poor Profitability

RIVN’s trailing-12-month gross profit margin of negative 238.89% is lower than the industry average of 35.41%. Its trailing-12-month ROCE, ROTC, and ROTA of negative 127.71%, 38.22%, and 39.37% compare with the industry averages of 13.00%, 6.38%, and 4.55%, respectively.

POWR Ratings Reflect Bleak Prospects

RIVN has an overall rating of F, equating to a Strong Sell in our proprietary POWR Ratings system. The POWR Ratings are calculated by considering 118 different factors, with each factor weighted to an optimal degree.

Our proprietary rating system also evaluates each stock based on eight distinct categories. RIVN has an F grade for Quality, consistent with its negative profitability margins.

It also has an F grade for Stability, in sync with its 24-month beta of 2.32.

In the 62-stock Auto & Vehicle Manufacturers industry, RIVN is ranked #53. Click here for the additional POWR Ratings for RIVN (Growth, Value, Momentum, and Sentiment).

View all the top stocks in the Auto & Vehicle Manufacturers industry here.

Bottom Line

RIVN’s bottom line is in the red, and its declining cash balance is concerning. Moreover, the stock possesses negative profitability margins. Considering RIVN’s weak fundamentals, it does not look like a bargain at its current prices. Therefore, RIVN might be best avoided now.

How Does Rivian Automotive, Inc. (RIVN) Stack up Against Its Peers?

While RIVN has an overall POWR Rating of F, one might consider looking at its industry peers, Volkswagen AG (VWAGY), Bayerische Motoren Werke Aktiengesellschaft (BMWYY), and Isuzu Motors Limited (ISUZY), which have an overall A (Strong Buy) rating.

What To Do Next?

Get your hands on this special report:

3 Stocks To DOUBLE This Year

What gives these stocks the right stuff to become big winners, even in this brutal stock market?

First, because they are all low-priced companies with the most upside potential in today’s volatile markets.

But even more important is that they are all top Buy rated stocks according to our coveted POWR Ratings system, and they excel in key areas of growth, sentiment and momentum.

Click below now to see these 3 exciting stocks that could double or more in the year ahead.

3 Stocks To DOUBLE This Year


RIVN shares were trading at $20.91 per share on Thursday morning, up $1.20 (+6.09%). Year-to-date, RIVN has gained 13.46%, versus a 7.99% rise in the benchmark S&P 500 index during the same period.


About the Author: Riddhima Chakraborty

Riddhima is a financial journalist with a passion for analyzing financial instruments. With a master’s degree in economics, she helps investors make informed investment decisions through her insightful commentaries.

More…

The post Is Rivian Stock a Bargain for Under $20? appeared first on StockNews.com

https://www.entrepreneur.com/finance/is-rivian-stock-a-bargain-for-under-20/444199


3 Growth Stocks to Buy Now Before They Heat up

The gradual decline in inflation and decelerating wage growth might prompt the Fed to slow the pace of rate hikes this year, which might help growth stocks to stage a recovery. So, fundamentally strong growth stocks Salesforce (CRM), HF Sinclair (DINO), and Box (BOX), which look poised to soar in the near term, might be ideal buys now. Keep reading.

December’s Consumer Price Index (CPI) fell 0.1% for the month, in line with the Dow Jones estimate, marking the largest month-over-month decrease since April 2020. Moreover, the Labor Department reported that employers added 223,000 jobs in December 2022, reflecting a slowdown from the pace of job creation seen earlier in the year.

Also, average hourly pay, which had been increasing at an annual rate of 5% in September, fell to 4.6% in the month.

The sky-high inflation and the Fed’s aggressive interest rate hikes to tame it have affected growth stocks significantly last year. However, the easing inflationary pressures and declining wage growth signals that the Fed’s rate hikes are having their intended effect, which might prompt the Fed to slow its rate hike pace.

The Fed is widely anticipated to deliver a 0.25 bps rate hike in its next meeting, a step back from a 0.50 bps hike last month.

Furthermore, as per Fundstrat Global Advisors co-founder Tom Lee, US stocks will surge back toward record highs in 2023 once the Federal Reserve signals that it’ll ease up on its monetary-tightening campaign. Lee also said that he expects the S&P 500 to steadily climb to hit 4,800 points this year.

Given this backdrop, fundamentally strong growth stocks Salesforce, Inc. (CRM), HF Sinclair Corporation (DINO), and Box, Inc. (BOX) might be ideal buys for solid returns this year.

Salesforce, Inc. (CRM)

CRM provides customer relationship management technology that brings companies and customers together worldwide. The company’s service offerings include Sales, Service, Marketing, and Commerce. The company provides its services through direct sales, consulting firms, systems integrators, and other partners.

The company’s forward Price/Book multiple of 2.79 is 32.8% lower than the industry average of 4.15.

During the third quarter that ended October 31, 2022, CRM’s total revenues increased 14.2% year-over-year to $7.84 billion. The company’s gross profit increased 14.5% year-over-year to $5.75 billion, and non-GAAP income from operations increased 30.9% year-over-year to $1.78 billion.

The consensus EPS estimate of $1.36 for the fiscal fourth quarter ending January 2023 indicates a 62.3% improvement year-over-year. The consensus revenue of $8 billion for the same quarter represents a 9.2% year-over-year growth. CRM has an impressive earnings surprise history as it has surpassed the consensus EPS and revenue estimates in each of the trailing four quarters.

Also, the company’s revenue and levered free cash flow have grown at a CAGR of 24.1% and 21.8%, respectively, over the past three years.

The stock has gained 26.7% over the past month to close the last trading session at $167.97.

CRM’s POWR Ratings reflect its promising outlook. The stock has an overall rating of B, which translates to Buy in our proprietary rating system. The POWR Ratings are calculated by considering 118 different factors, with each factor weighted to an optimal degree.

It has an A grade for Growth and a B for Sentiment. Within the 138-stock Software – Application industry, it is ranked #27.

Beyond the POWR Ratings just highlighted, you can access additional CRM grades for Value, Momentum, Stability, and Quality here.

HF Sinclair Corporation (DINO)

DINO is an independent petroleum refiner that produces and markets high-value light products such as gasoline, diesel fuel, jet fuel, renewable diesel, and other specialty products.

Its forward non-GAAP P/E of 3.80x is 53.8% lower than the industry average of 8.23x. Its 0.27 forward non-GAAP PEG multiple is 59.6% lower than the industry average of 0.68.

The company pays $1.20 annually as dividends, which translates to a yield of 2.81% at the current price. Its four-year average dividend yield is 2.99%.

DINO’s sales and other revenues grew 126.2% year-over-year to $10.60 billion for the third quarter that ended September 30, 2022. Its adjusted EBITDA increased 267.9% year-over-year to $1.50 billion. The company’s adjusted net income increased 368.2% year-over-year to $982.90 million, while its adjusted EPS rose 257.8% year-over-year to $4.58.

Street expects DINO’s revenue to increase 106.6% year-over-year to $37.99 billion for the fiscal year 2022. Its EPS is expected to rise 789% year-over-year to $14.96 for the same year. The company has surpassed the consensus revenue estimates in all of the trailing four quarters.

Moreover, the company’s net income and EPS have grown at a CAGR of 39.1% and 33%, respectively, over the past three years.

The stock has gained 9.7% over the past month and 61.8% over the past year to close the last trading session at $56.90.

It is no surprise that DINO has an overall rating of B, equating to a Buy in our POWR Ratings system.

It has a grade of A for Growth and Momentum and a B for Quality. It is ranked #10 among 93 stocks in the B-rated Energy – Oil & Gas industry.

In addition to the grades stated above, we’ve also rated DINO for Value, Sentiment, and Stability. Get all DINO ratings here.

Box, Inc. (BOX)

BOX provides a cloud content management platform that enables organizations of various sizes to manage and share their content from anywhere on any device.

On January 10, BOX announced that BETC, a global communications, marketing, and advertising agency, have chosen BOX’s secure content management capabilities to power collaboration and accelerate processes around content management.

Sebastien Marotte, President of EMEA at BOX, said, “We’re delighted to support BETC in powering the next generation of creative content for their prestigious clients. We look forward to our continued partnership as BETC continues to expand its use of Box and develop its Content Cloud journey.”

In terms of forward non-GAAP PEG, BOX is currently trading at 1.36x, which is 14.8% lower than the industry average of 1.60x. Its forward Price/Cash flow multiple of 16.32 is 11.2% lower than the industry average of 18.37.

BOX’s revenue increased 11.6% year-over-year to $249.95 million in the third quarter that ended September 30, 2022. Its gross profit rose 15.2% year-over-year to $185.46 million. Also, its EPS came in at $0.03, compared to a loss per share of $0.12 in the year-ago period.

Analysts expect BOX’s revenue to rise 9.9% year-over-year to $256.48 million in the fiscal fourth quarter ended January 2023. Its EPS is estimated to grow 42.6% year-over-year to $0.34 in the same quarter.

Its revenue and levered free cash flow have grown at a CAGR of 15.1% and 29.1% over the past five years.

The stock has gained 22.4% over the past year to close the last trading session at $31.99. It has gained 10.1% over the past month.

BOX’s strong fundamentals are reflected in its POWR Ratings. It has an overall B rating, which equates to a Buy in our proprietary rating system.

It also has an A grade for Growth and Quality and a B for Value. BOX is ranked #6 among the 78 stocks in the Technology – Services industry.

Click here for the additional POWR Ratings for Stability, Momentum, and Sentiment for BOX.

Consider This Before Placing Your Next Trade…

We are still in the midst of a bear market.

Yes, some special stocks may go up. But most will tumble as the bear market claws ever lower.

That is why you need to discover the brand new “Stock Trading Plan for 2023” created by 40-year investment veteran Steve Reitmeister. There he explains:

  • Why it’s still a bear market
  • How low stocks will go
  • 9 simple trades to profit on the way down
  • Bonus: 2 trades with 100%+ upside when the bull market returns

You owe it to yourself to watch this timely presentation before placing your next trade.

Stock Trading Plan for 2023 >


CRM shares were trading at $168.63 per share on Wednesday morning, up $0.66 (+0.39%). Year-to-date, CRM has gained 27.18%, versus a 5.98% rise in the benchmark S&P 500 index during the same period.


About the Author: Kritika Sarmah

Her interest in risky instruments and passion for writing made Kritika an analyst and financial journalist. She earned her bachelor’s degree in commerce and is currently pursuing the CFA program. With her fundamental approach, she aims to help investors identify untapped investment opportunities.

More…

The post 3 Growth Stocks to Buy Now Before They Heat up appeared first on StockNews.com

https://www.entrepreneur.com/finance/3-growth-stocks-to-buy-now-before-they-heat-up/444102


Rev Up Your Portfolio with Honda Motor (HMC) Shares

PE of 9 along with 3.9% dividend yield is a pretty good start to any stock picking conversation. Yet there is a lot more to love about Honda Motor Company (HMC) making it one of our top value picks for 2023. Get the full story below….

shutterstock.com – StockNews

Honda Motor Company (HMC) is one of our 7 favorite value stocks for the year ahead. Having a Value rating of A is a good start, but only part of the story. Let’s start at the beginning to spell it all out.

Honda was originally a motorcycle manufacturer. Now they make everything from motorcycles to automobiles, power products such as boat engines, generators, and lawnmowers. It they also makes robots and private jets and is currently Japan’s third-largest automaker by sales and has the highest exposure to North America out of Japan’s big three.

Honda’s brand and its reputation for quality have certainly helped drive demand for its models. HMC has also been historically known for fuel-efficient cars, which has positioned it to take advantage of the massive consumer demand for more fuel-efficient vehicles.

The popularity of its vehicles has also allowed it to use fewer incentives than other automakers, boosting its profits and improving its cars’ resale value. Like most automakers these days, the company is investing in electric vehicles with its Honda 2030 Vision. It should also benefit from a rebound in auto production as the chip shortage eases.

Now let’s get down to why you are really reading this article. To appreciate the tremendous value story at play.

HMC is one of the top stocks according to the POWR Rating with an A or Strong Buy. Stocks with that rating have beaten the S&P 500 by more than 4X since 1999.

On top of that we have a Value rating of A thanks in large part by a rock-bottom P/E of 9. On top of that you have a very attractive 3.9% dividend yield. This makes for a winning combo, and a major reason that Wall Street analysts expect HMC to greatly outperform in the year ahead.

Want to Discover More Value Stocks?

HMC is just 1 of 7 attractive value stocks found in a new special report we just put together. Click the link below to claim your free copy now:

7 SEVERELY Undervalued Stocks

What To Do Next?

Watch my brand new presentation: “Stock Trading Plan for 2023” covering:

  • Why 2023 is a “Jekyll & Hyde” year for stocks
  • 4 Warnings Signs the Bear Returns in Early 2023
  • 9 Trades to Profit on the Way Down
  • Plan to Bottom Fish @ Market Bottom
  • 2 Trades with 100%+ Upside Potential as New Bull Emerges
  • And Much More!

Watch Now: “Stock Trading Plan for 2023” > 

Wishing you a world of investment success!


Steve Reitmeister…but everyone calls me Reity (pronounced “Righty”)
CEO, Stock News Network and Editor, Reitmeister Total Return


HMC shares were trading at $24.07 per share on Thursday morning, down $0.02 (-0.08%). Year-to-date, HMC has gained 5.29%, versus a 4.69% rise in the benchmark S&P 500 index during the same period.


About the Author: Steve Reitmeister

Steve is better known to the StockNews audience as “Reity”. Not only is he the CEO of the firm, but he also shares his 40 years of investment experience in the Reitmeister Total Return portfolio. Learn more about Reity’s background, along with links to his most recent articles and stock picks.

More…

The post Rev Up Your Portfolio with Honda Motor (HMC) Shares appeared first on StockNews.com

https://www.entrepreneur.com/finance/rev-up-your-portfolio-with-honda-motor-hmc-shares/443862


A Tale of Two Markets

It was the best of times (Visa earnings), it was the worst of times (Intel earnings)…Charles Dickens didn’t actually write those words about our current stock market (SPY) environment… but he might as well have. Read on to find out what this could mean for where the market heads next.

shutterstock.com – StockNews

(Please enjoy this updated version of my weekly commentary originally published January 26th, 2023 in the POWR Stocks Under $10 newsletter).

Market Commentary

For anyone who has been out of middle school for a few decades, here’s the entire opening to Dickens’ “A Tale of Two Cities.”

“It was the best of times, it was the worst of times, it was the age of wisdom, it was the age of foolishness, it was the epoch of belief, it was the epoch of incredulity, it was the season of light, it was the season of darkness, it was the spring of hope, it was the winter of despair.”

And dang, if that doesn’t just sum up our current situation, I don’t know what does.

And depending on who’s talking, we could either be well into our next BULL market or cluelessly heading toward a 20% dropoff.

And while I seem to know analysts that are bearish, neutral, or bullish in equal measure, there’s one thing I’ve noticed that many of them have in common…

Almost no one is excited about a single sector. Nearly everyone is excited about a few particular stocks… but not an entire sector.

And it’s because we’re living in this “tale of two markets.” We’ll get extremely pessimistic forward guidance from Intel or Goldman Sachs on the same day as largely optimistic guidance from Visa or United Airlines.

And each time, the other side will say, “Oh, how foolish those bulls/bears are. They have no idea this is another trap for them to fall into.”

And then we have analysts who are switching to the opposite side! In a recent alert for his Reitmeister’s Total Return service, Editor and StockNews CEO Steve Reitmeister wrote that he was becoming less bearish, which genuinely shocked me to see.

If that’s not a sign of market positivity, I don’t know what is…

And then today, one of my closest friends and a longtime mentor who has been fairly bullish all this time told me she now believes that we’ll have a recession between Q2 and Q3, and that it will feel more like a depression than a recession.

You know what I think? I think I’m actually excited for next week’s Federal Reserve meeting.

There has been a lot of new data and information — some of it bullish, some of it bearish — and now we need Fed Chair Jerome Powell to tell investors what we should think about it.

Because here’s the thing…

Even if the bullish data really is bullish… we’re not going to get any kind of sustained rally until the Fed indicates that they’re potentially considering some kind of policy pivot. There’s essentially a lid on how high stocks can go, thanks to the Fed’s terminal rate projections.

And if the bearish data really is bearish, fresh hawkish comments from the Fed will be enough to tamp down any unwarranted optimism.

Conclusion

Fed Chair Jerome Powell is expected to give us the results of their upcoming meeting on February 1. That’s when we’ll find out which of us have been foolish… and which have been wise.

 What To Do Next?

If you’d like to see more top stocks under $10, then you should check out our free special report:

3 Stocks to DOUBLE This Year

What gives these stocks the right stuff to become big winners, even in this brutal stock market?

First, because they are all low priced companies with the most upside potential in today’s volatile markets.

But even more important, is that they are all top Buy rated stocks according to our coveted POWR Ratings system and they excel in key areas of growth, sentiment and momentum.

Click below now to see these 3 exciting stocks which could double or more in the year ahead.

3 Stocks to DOUBLE This Year

All the Best!

Meredith Margrave
Chief Growth Strategist, StockNews
Editor, POWR Stocks Under $10 Newsletter


SPY shares were trading at $407.00 per share on Friday afternoon, up $2.25 (+0.56%). Year-to-date, SPY has gained 6.42%, versus a % rise in the benchmark S&P 500 index during the same period.


About the Author: Meredith Margrave

Meredith Margrave has been a noted financial expert and market commentator for the past two decades. She is currently the Editor of the POWR Growth and POWR Stocks Under $10 newsletters. Learn more about Meredith’s background, along with links to her most recent articles.

More…

The post A Tale of Two Markets appeared first on StockNews.com

https://www.entrepreneur.com/finance/a-tale-of-two-markets/443861


6 Reasons to Become Bullish Now

40 year investment veteran Steve Reitmeister has been beating the bearish drums since May 2022. However, he is seeing more and more reasons to consider that it might be time to get bullish on stocks (SPY). All 6 of those bullish reasons are shared in the new commentary below including top picks to consider now.

shutterstock.com – StockNews

I was not the first guy to get bearish in 2022, but by May I got the memo just in the nick of time. This led to a major shift in my portfolio that allowed me to profit on the way down. And I have been steadfastly bearish since.

But just like the Fed, my outlook is “data dependent“. And recent data has me becoming less bearish. Note that is not the same thing as becoming bullish.

Why the change of heart? And what does that mean for trading strategy going forward?

Read on below for the full story…

Market Commentary

First, let’s start with some important terminology. Less bearish is quite different than being bullish.

Imagine that I previously saw 80% odds of bear market and lower stock prices in 2023. Thus, only a 20% possibility of bull market.

Given recent information my view has shifted down to about 65% bearish probability versus 35% bullish. That is nearly 2 to 1 in favor of bear market forming…just a notch less bearish than before. The next logical question is…

Why still bearish?

You have already me talk non-stop since last May about all the reasons to be bearish. That is overflowing in my article archive. Plus my most recent presentation puts that all into perspective in a nice concise way: Stock Trading Plan for 2023.

Now we are going to flip over this coin and talk about the bullish view. It is hard for me to say it in a straight forward manner. Instead, I am going to flush out all the individual ideas that point in a bullish direction…the sum total of them is still less likely than the bearish thesis playing out.

Employment is Too Strong: That was on full display Thursday when Jobless Claims went even lower to 186,000 claims. You can not have a recession without job loss. That is why the first half of 2022 was not labeled a recession even though we had 2 straight quarters of negative GDP.

So yes, we all see the headlines about job cuts at some high profile tech firms. But overall there are far too many job openings which is why the unemployment has been going lower…not higher. The trends in jobless claims say that is not going to change anytime soon as you usually need claims over 300,000 to make the unemployment go up.

To put it together, we may very well have an economic contraction coming soon, but it likely will barely effect employment…and thus increases odds of a soft landing for which stocks don’t need to fall further.

Break Above 200 Day Moving Average: For as much as I rely upon the fundamentals, I have learned to pay close attention to the 200 day moving average for the S&P 500 (SPY). We broke above on 1/19 and have only rallied higher since then. 6 straight closes above and 100 points north of the mark seems to confirm the breakout for now.

As January Goes…So Goes the Rest of the Year“: This is another one of those classic investment sayings that does have a bit of truth behind it. Not just the 6% gain for the S&P 500 on the month, but the very Risk On nature of the groups leading the way. So if the saying holds true it means more of the same in 2023.

Less Bad = Good: This notion comes from the idea that expectations are incredibly low for the economy and corporate earnings. Lower hurdles like these make it easier to impress investors where things being less bad than expected is all it takes to bid up stock prices.

Too Many Bears: Have you ever noticed that investor sentiment is a contrary indicator? The more bullish people feel = optimism too high = greater odds of downside to follow.

The same is true in reverse. When folks are too bearish…then too often the opposite happens. And indeed this is the most widely expected recession and bear market that I can remember. That increases the odds that the opposite will play out. This also fits in with the time honored notion that “the market climbs a wall of worry“.

Fed Pivot on 2/1?: The Fed is a slow and deliberate group. And given statements in the past, and all throughout January, they will continue to raise rates into the future.

However, any softening in their language to acknowledge that inflation is moderating and just maybe they do not need to stay hawkish for as long as previously stated could well be the final nail in the bearish coffin with more upside to come. That is because it increases odds of soft landing.

Note that the absolute opposite could happen and that firmly hawkish statements would stop this rally in its tracks with significant downside to follow.

I realize that after reading these 6 reasons to become bullish that it may sound like a convincing argument. Thus, I bring your attention back to the statement at the top where I still see 65% likelihood of continuation of the bear market with new lows later in 2023.

That is because there is at least 6 more months of restrictive Fed policies ahead…plus the 3-6 months of lagged effect of these policies equals a lot more time for a full blow recession to take root. And thus plenty of opportunity for unemployment to finally worsen.

This is the Pandoras Box of the economy. Once that PAIN starts to roll out then everyone becomes more fearful of their job security. This leads to more saving and less spending which further weakens the economy with more job layoffs as a consequence.

If we can truly avoid this vicious cycle, and enjoy a soft landing, then yes, the bull market starts now. The odds of which will keep moving with each new economic fact in hand.

Again, my reading of all of this is still 65% likelihood of recession and deepening bear market. However, am prepared to adjust more bullish if the preponderance of the evidence swings in that direction.

The next key piece of evidence comes on Wednesday 2/1 when the Fed has their rate decision and announcement. That could be incredibly bullish…incredibly bearish…or incredibly uncertain.

I will do my level best to decipher it all for you in next week’s commentary. Just make sure that your mind is open to all new facts as they roll in because the most dangerous thing with investing is to only listen to evidence that proves your point and ignoring the rest.

We are investors. Not bulls or bears.

Yes, there are times we are feeling more bullish or bearish. But that label should never be affixed to you as a point of identity as it could become too permanent stopping you from switching gears for the betterment of your portfolio.

Right now we all need to be flexible to review the facts with as open a mind as possible.

Stay tuned more updates and associated trades as these facts roll in.

What To Do Next?

Watch my brand new presentation: “Stock Trading Plan for 2023” covering:

  • Why 2023 is a “Jekyll & Hyde” year for stocks
  • 4 Warnings Signs the Bear Returns in Early 2023
  • 9 Trades to Profit on the Way Down
  • Plan to Bottom Fish @ Market Bottom
  • 2 Trades with 100%+ Upside Potential as New Bull Emerges
  • And Much More!

Watch “Stock Trading Plan for 2023” Now >

Wishing you a world of investment success!


Steve Reitmeister…but everyone calls me Reity (pronounced “Righty”)
CEO, StockNews.com and Editor, Reitmeister Total Return


SPY shares fell $0.09 (-0.02%) in after-hours trading Friday. Year-to-date, SPY has gained 6.08%, versus a % rise in the benchmark S&P 500 index during the same period.


About the Author: Steve Reitmeister

Steve is better known to the StockNews audience as “Reity”. Not only is he the CEO of the firm, but he also shares his 40 years of investment experience in the Reitmeister Total Return portfolio. Learn more about Reity’s background, along with links to his most recent articles and stock picks.

More…

The post 6 Reasons to Become Bullish Now appeared first on StockNews.com

https://www.entrepreneur.com/finance/6-reasons-to-become-bullish-now/443841


The Best Way to Play Stock Breakouts

No matter market direction there are always stocks ready to break higher. What is the best way to find these timely picks? And how do you maximize profits? 35 year trading veteran Tim Biggam spells it all out in this timely article below.

shutterstock.com – StockNews

The S&P 500 (SPY) has been on the verge of a breakout for several days. It finally overtook the 200-day moving average and the downtrend line that has been in place for nearly 10 months.

The index has closed above the big round resistance level of $4000 each of the past three trading days, but has yet to do it with conviction.

This brings up the question of how do you best play for breakouts, given the difficulty the market has in providing definitive clues.

The answer is comprised of two separate components-fundamental and technical. This is the exact recipe we use at POWR Breakouts to find stocks with the best chance of having a bonafide breakout.

What Exactly Is A Breakout?

Simply put, a breakout is when a stock makes a meaningful move past a well-defined resistance level. The chart of the SPX shown above has a clearly well-defined resistance level which has held previously on several occasions.

Although the SPX did manage to close above the downtrend line, 200-day moving average and round number resistance at $4000, it failed to do so in a meaningful way so far. Whether it ultimately succeeds or not is anyone’s best guess.

But rather than just guessing, it would be wise to use other tools to put the probabilities in your favor. Here are the two best ways to accomplish that goal.

POWR Ratings (Fundamentals)

The POWR ratings are a combination of 118 different fundamental factors that uncover stocks that are ready to outperform. These stocks are then ranked according to all these multitude of factors into a clear and concise ranking system, that’s easy to use and understand.

The very best stocks are A-rated (Strong Buy). The really good stocks receive a B-rating which signifies Buy.

The chart below highlights just how big an advantage this provides. The Strong Buy A-rated stocks (triple the return) and B-rated Buy stocks (double the return) have absolutely crushed the market over the past 20 plus years.

So, when looking for the best breakout candidates, it is always good to start with the best stocks from a fundamental perspective. POWR Ratings gets that done.

Trade Triangles (Technicals)

The Trade Triangles were developed by a renowned trader at the Chicago Merc and a computer engineer to identify meaningful trends in a straight-forward manner across multiple timeframes.

They were looking to uncover stocks with increasing strength that have the potential for outsized moves to the upside.

The illustration below shows how simply, but effectively, the trade triangles work. Note that having two of the triangles match means you can be comfortable taking a position to ride the trend.

POWR Breakouts always makes sure that both the long term and intermediate term triangles are trending up and flashing green.

Taking the top technical stocks to trade a breakout makes sense. It also makes the likelihood of a breakout much greater plus increases the size of a power-packed pop to the upside. Better chance with bigger return using the trade triangles.

We will exit the trade when the original thesis changes. POWR Ratings drop to C or lower, trade triangles have intermediate or long term turn red, or the breakout fails to materialize. Also exit profitably when the stock breakouts too hard for too long and begins to stall out.

Let’s take a walk through a recently closed out trade to see the power of the process-and also see when to exit the trade.

Trade Example:  Adams Resources (AE)

December 19, 2022 (Entry)

Adams Resources was a Strong Buy-A Rated-stock in the Buy Rated Energy- Oil & Gas Industry. Ranked near the very top and number 3 out of 92 in the industry as well. Strong across the board from the fundamental viewpoint.

The trade triangles were also pointing to strength. Long term and intermediate term both trending up and showing green. +85 trend formula score strong as well.

Shares broke out with conviction above the $39 resistance area. Plus had a key reversal day. MACD is poised to generate a fresh buy signal.

Went long AE in the POWR Breakouts portfolio on 12/19/22 at $41.02. Held the long position until the stock got to historically overbought readings and struggled.

9-day RSI went past 80 but began to weaken. MACD reached an extreme above 1 then headed lower. Bollinger Percent B raced past 100 before softening.

Shares were trading at a big premium to the 20-day moving average.  Previous times all these indicators aligned in a similar fashion marked significant short-term top in AE stock.

Exited the long AE position on 1/13/23, for a +18.09% gain in under a month.

Identifying potential breakout points is only the first step in creating a robust and profitable trading system. Making sure you pick the strongest stocks from both a fundamental (POWR Ratings) and technical (Trade Triangles) standpoint is absolutely vital to continued success.

Knowing when to get out with a big profit or when to stop out with a small loss is the final, and sometimes most overlooked, element in the overall equation.

That’s why using POWR Breakouts is key to learning the why, when and how of putting the odds in your favor when looking to bank big bucks with breakouts.

What To Do Next?

If you’d like to discover more top-rated stocks according to our exclusive POWR Ratings, then you should check out our free special report:

3 Stocks to DOUBLE This Year

What gives these stocks the right stuff to become big winners, even in this brutal stock market?

First, because they are all low priced companies with the most upside potential in today’s volatile markets.

But even more important, is that they are all top Buy rated stocks according to our coveted POWR Ratings system and they excel in key areas of growth, sentiment and momentum.

Click below now to see these 3 exciting stocks which could double or more in the year ahead.

3 Stocks to DOUBLE This Year

Here’s to good trading!

Tim Biggam
Editor, POWR Breakouts Newsletter


SPY shares were trading at $407.06 per share on Friday afternoon, up $2.31 (+0.57%). Year-to-date, SPY has gained 6.44%, versus a % rise in the benchmark S&P 500 index during the same period.


About the Author: Tim Biggam

Tim spent 13 years as Chief Options Strategist at Man Securities in Chicago, 4 years as Lead Options Strategist at ThinkorSwim and 3 years as a Market Maker for First Options in Chicago. He makes regular appearances on Bloomberg TV and is a weekly contributor to the TD Ameritrade Network “Morning Trade Live”. His overriding passion is to make the complex world of options more understandable and therefore more useful to the everyday trader. Tim is the editor of the POWR Options newsletter. Learn more about Tim’s background, along with links to his most recent articles.

More…

The post The Best Way to Play Stock Breakouts appeared first on StockNews.com

https://www.entrepreneur.com/finance/the-best-way-to-play-stock-breakouts/443840


BuzzFeed preps AI-written content while CNET fumbles

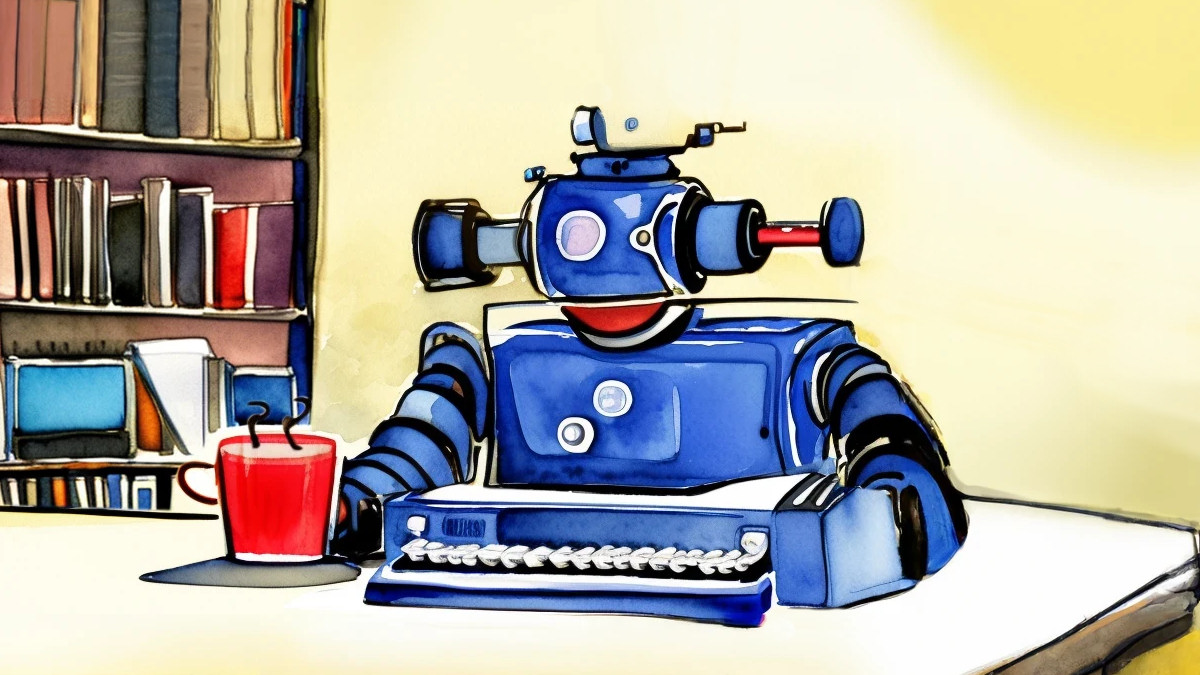
An AI-generated image of a robot typewriter-journalist hard at work.
Enlarge / An AI-generated image of a robot typewriter-journalist hard at work.
Ars Technica

On Thursday, an internal memo obtained by The Wall Street Journal revealed that BuzzFeed is planning to use ChatGPT-style text synthesis technology from OpenAI to create individualized quizzes and potentially other content in the future. After the news hit, BuzzFeed’s stock rose 200 percent. On Friday, BuzzFeed formally announced the move in a post on its site.

“In 2023, you’ll see AI inspired content move from an R&D stage to part of our core business, enhancing the quiz experience, informing our brainstorming, and personalizing our content for our audience,” BuzzFeed CEO Jonah Peretti wrote in a memo to employees, according to Reuters. A similar statement appeared on the BuzzFeed site.

The move comes as the buzz around OpenAI’s ChatGPT language model reaches a fever pitch in the tech sector, inspiring more investment from Microsoft and reactive moves from Google. ChatGPT’s underlying model, GPT-3, uses its statistical “knowledge” of millions of books and articles to generate coherent text in numerous styles, with results that read very close to human writing, depending on the topic. GPT-3 works by attempting to predict the most likely next words in a sequence (called a “prompt”) provided by the user.

In particular, BuzzFeed told Reuters that it will not utilize ChatGPT itself, but instead will craft a custom implementation based on OpenAI’s GPT-3 technology: “We are not using ChatGPT—we are using OpenAI’s publicly available API (application programming interface).”

A handout diagram from BuzzFeed showing how it'll use AI on the site.
Enlarge / A handout diagram from BuzzFeed showing how it’ll use AI on the site.

In light of recent news that CNET has been publishing AI-written articles (causing an ongoing controversy covered well by Futurism and The Verge), some worry that the move from BuzzFeed may signal a new trend in media toward relying on content produced by machines instead of human writers, especially in the wake of a 12 percent cut in BuzzFeed’s staff late last year. The Wall Street Journal reports that “BuzzFeed remains focused on human-generated journalism in its newsroom,” according to a BuzzFeed spokesperson.

Just how serious is BuzzFeed about AI? Peretti laid out his vision, which still leaves a role for humans in the future, albeit in an augmented fashion:

The creative process will increasingly become AI-assisted and technology-enabled. If the past 15 years of the internet have been defined by algorithmic feeds that curate and recommend content, the next 15 years will be defined by AI and data helping create, personalize, and animate the content itself. Our industry will expand beyond AI-powered curation (feeds), to AI-powered creation (content). AI opens up a new era of creativity, where creative humans like us play a key role providing the ideas, cultural currency, inspired prompts, IP, and formats that come to life using the newest technologies.

Not everyone is convinced that AI writing is the future, however. Some already think that the “pivot to ChatGPT” move toward AI-generated content could be a fad in the vein of the “pivot to video” movement that caused so much trouble for media companies between 2015 and 2018. Others compare AI hype to the metaverse, blockchain, and NFT crazes in recent years.

Hype aside, it’s possible that the prospect of AI-powered automation reducing the cost of content creation may be too enticing to ever abandon completely, especially if AI tools improve in quality over time. CNET’s recent misadventure in AI using an internally developed AI engine—the most high-profile AI-authored experiment from a major publication that we know of—has so far been a failure, resulting in articles full of errors and plagiarism. But even after considerable blowback, CNET announced it would “continue embracing” AI-authored content. If the clicks keep coming and it fits its business model, CNET sees no reason to change.

Whether AI tools will ever completely replace human journalists or merely boost their productivity (in the vein of an invention like the typewriter) is an open question that we can’t answer at the moment. Only time will tell as the story of generative AI continues to rapidly unfold.

https://arstechnica.com/?p=1912889


3 Key Points to Watch in Today’s Market

Every Friday, Steve Reitmeister (Reity) and I sit down to chat about the week and how we’re feeling about the stock market (SPY). Normally, the two of us are pretty in sync — we’ve both been pretty bearish for months. However last week, it looked like that was starting to change. “Are you bullish now?”, he asked. I think my answer to his question surprised him. Read on for what I said — and why…I think the results may surprise you too….

shutterstock.com – StockNews

(Please enjoy this updated version of my weekly commentary originally published January 20th, 2023 in the POWR Stocks Under $10 newsletter).

Market Commentary

Now, for those of you who also read my POWR Growth newsletter, this is a bit of a retread, but I thought it nicely summed up my latest thoughts on where the stock market (SPY) currently is, and what we need to see next for things to change.

So, back to Reity’s question: Am I bullish now?

The answer is… it’s complicated.

I’ve been pretty bearish for the past six or seven months.

Fed Chair Jerome Powell made it pretty clear that inflation was Enemy No. 1 and the central bank was going to do anything in its power to get prices under control. I mean, come on; his top buzzword was “pain.” It was not a good time to be long anything.

And as we saw in 2022, Powell meant what he said and he said what he meant. Stocks paid the price, falling nearly 20%.

We finished the year commiserating about our “no show” Santa Claus rally and sighing over the number of analyst predictions for poor earnings and a coming recession.

And then, we flipped over our calendar year and things started looking up. The S&P 500 (SPY) has gained nearly 4% in just a few weeks. And price can’t lie. Clearly someone is buying.

So, what’s the deal? Did someone just forget to send out the memo that we had switched from bear to bull?

Things certainly seem better than we were collectively expecting at the end of December.

So, am actually I bullish now? Not particularly. But I’m not particularly bearish either.

If you ask me, I think we’re somewhere in between. Things aren’t roses and lollipops… but they’re also not on the verge of collapse.

Yes, we still have inflation and a Fed threatening to raise the terminal rate further… but we also have three consecutive months of reports showing that inflation is in a downtrend.

We have an inverted yield curve… but we also have economist Campbell Harvey saying the famed (and highly accurate) recession indicator could be wrong this time. That’s a really big deal; Harvey is the guy who linked inverted yield curves to recessions in the first place.

We have huge earnings misses like this week’s report from Goldman Sachs… and then major earnings beats like this week’s reports from United Airlines and Netflix.

And don’t forget about those bullish green shoots I highlighted in last week’s issue

Things are complicated, y’all!

But I see three potential turning/pivot points that could make things a whole lot less complicated, one way or the other.

1) Things (economic data/earnings/current events) turn negative.

One reason I think people may be buying right now? We set the bar really, really low. Going into the year, we were expecting disaster. But so far, things have been pretty neutral, which means they’ve been great!

But if this is just a bear market rally, I think the first sign of negativity could spoil the party and scare off investors. And then we’re back to everything just being the worst.

But if we get some bad news and investors just shrug it off? Or if we continue to see more of these economic “green shoots” in subsequent reports? Then yeah, I think we could be looking at a new bull.

2) The job market finally snaps.

The “consumer” will keep consuming as long as the jobs picture remains rosy. That’s certainly another factor buoying stock prices right now. A lot of people are arguing that we “can’t” have a recession because the job market is too strong.

Of course, this is a bad “bull market” indicator to rely on, since employment lags behind most other indicators. Sure, if employment stays tight, people will keep spending and the Fed will probably get the “soft landing” they’ve been aiming for.

But we could be well on our way down the next leg lower before we see any weakness in job numbers because employment is a lagging indicator.

That’s why it’s difficult to hang your hat on the jobs data.

(Oh, and we have seen some weakness in job numbers. Just ask anyone you know who works — worked? — in the tech industry, where a number of major companies have laid off several thousand employees. Just this week, Alphabet announced it was laying off 12,000 jobs this quarter.)

3) The S&P 500 breaks above 4,000… and stays there.

This is a major psychological resistance level in the market right now. In the past week, the S&P 500 has managed to get THIS CLOSE to closing above 4,000… only to fall pennies short.

Why does that number matter? It doesn’t, theoretically. What does matter is that we’ve failed to break above it now — multiple times. So now, when stocks start approaching 4,000, buyers ask themselves if they’re buying too high… and then all the buying interest dries up.

If investors had a strong conviction that the S&P 500 would keep climbing above 4,000, they would absolutely buy. The fact that we can’t break that level means there’s not enough bullish conviction. For the market to pick up again, we’ll need to bust that line.

Until we do… or until we see the results from one of these two other potential turning points, things will likely remain complicated.

Even in the best-case scenario — no recession, mixed earnings, a pause in rate hikes — I’m not seeing anything pointing toward a market boom. Prices are still elevated. Supply chain issues are still very real.

Companies are still warning investors that they’re not expecting much growth for the year. It’s probably not going to be a 30%-gain kind of year…

Conclusion

The long and short of it is that we’re in market purgatory. The potential of a recession is hanging over our heads… and over the market. Earlier this week, I even heard an analyst say it would be better to have a recession and just get it over with.

Until we see the market turn one way or the other, we’ll probably still keep about 40% of our capital in cash and the rest in high-quality stocks under $10. That means that in addition to adding a few new picks, I’ll be looking to sell a portion of our positions when they hit big profits.

That way we can continue riding their strength upward, but we’re protected from any major changes in direction.

What To Do Next?

If you’d like to see more top stocks under $10, then you should check out our free special report:

3 Stocks to DOUBLE This Year

What gives these stocks the right stuff to become big winners, even in this brutal stock market?

First, because they are all low priced companies with the most upside potential in today’s volatile markets.

But even more important, is that they are all top Buy rated stocks according to our coveted POWR Ratings system and they excel in key areas of growth, sentiment and momentum.

Click below now to see these 3 exciting stocks which could double or more in the year ahead.

3 Stocks to DOUBLE This Year

All the Best!

Meredith Margrave
Chief Growth Strategist, StockNews
Editor, POWR Stocks Under $10 Newsletter


SPY shares closed at $395.88 on Friday, up $7.24 (+1.86%). Year-to-date, SPY has gained 3.52%, versus a % rise in the benchmark S&P 500 index during the same period.


About the Author: Meredith Margrave

Meredith Margrave has been a noted financial expert and market commentator for the past two decades. She is currently the Editor of the POWR Growth and POWR Stocks Under $10 newsletters. Learn more about Meredith’s background, along with links to her most recent articles.

More…

The post 3 Key Points to Watch in Today’s Market appeared first on StockNews.com

https://www.entrepreneur.com/finance/3-key-points-to-watch-in-todays-market/443421


Stock Trading Plan for 2023

40 year investment veteran Steve Reitmeister shares his most complete and up to the minute analysis of what lies ahead in 2023. First a return of the bear market with the S&P 500 (SPY) making news lows. Yet just at the darkest hour the new bull market will emerge ushering in tremendous gains to investors who time it right. Steve shares his trading plan along with top 9 picks to profit on the way to bear market bottom. Next he shares a plan to buy the market bottom with 2 top picks set to rally 100%+. Get the full story below.

shutterstock.com – StockNews

The new year has gotten off to a bullish start. That is very typical behavior as the act of flipping the calendar over often comes with a fresh round of optimism.

But is being bullish the wisest approach given the ever darkening recessionary storm clouds?

It is for this reason you should watch my brand new presentation:

Stock Trading Plan for 2023 >

Not convinced?

Consider that there are 3 rock solid indicators that are right now SCREAMING recession.

And then realize that the average bear market decline is 34% which equates to 3,180 for the S&P 500…yes, a good deal below where we stand now.

And then consider that I have lined up 9 perfect trades to profit on the way down.

And finally, just for good measure, I tell you how I plan to bottom fish for the next bull market. This includes 2 trades with 100% upside potential as the new bull market emerges.

If these ideas appeal to you, then please click below to access this vital presentation now:

Stock Trading Plan for 2023 >

Wishing you a world of investment success!


Steve Reitmeister…but everyone calls me Reity (pronounced “Righty”)
CEO, Stock News Network and Editor, Reitmeister Total Return


SPY shares were trading at $391.92 per share on Friday afternoon, up $3.28 (+0.84%). Year-to-date, SPY has gained 2.48%, versus a % rise in the benchmark S&P 500 index during the same period.


About the Author: Steve Reitmeister

Steve is better known to the StockNews audience as “Reity”. Not only is he the CEO of the firm, but he also shares his 40 years of investment experience in the Reitmeister Total Return portfolio. Learn more about Reity’s background, along with links to his most recent articles and stock picks.

More…

The post Stock Trading Plan for 2023 appeared first on StockNews.com

https://www.entrepreneur.com/finance/stock-trading-plan-for-2023/443420


Is Dow Inc. (DOW) a Top Value Stock in 2023?

PE of 6.6 + 5% dividend yield is a pretty good equation for an attractive stock. And that is the equation for Dow Incorporated (DOW) at this time. Find out why it is one of our favorite value stocks in 2023 in the article below.

shutterstock.com – StockNews

The answer to the headline is YES!…Dow Inc (DOW) is one of the most attractive value stocks for the year ahead.

Why?

Let me spell it out for you now…

As you know, DOW is a diversified chemical manufacturing company combining science and technology to develop innovative solutions that are essential to human progress. It’s well diversified portfolio includes Packaging & Specialty Plastics, Industrial Intermediates & Infrastructure, and Performance Materials & Coatings.

This selection is in many ways the antithesis of the previous top value pick, Bristol-Myers Squibb (BMY) which was quite conservative. Here we are selecting a leading materials company to enjoy tremendous growth as the economy gets back on track later in 2023. Likely those good times continue for another 5-10 years just like the previous bullish cycle pushing EPS and share price higher.

An interesting part of the DOW story is their surprisingly low-cost structure that has allowed the company to withstand inflationary pressures better than most companies. It’s also in a position to pass on price increases given that its products are essential for so many industries. This combination points to healthy profit margins ahead.

The company has a Value Grade of A, which certainly makes sense with a P/E of only 6.6. It also has a Quality Grade of B which points to superior operational efficiency.

If that was not attractive enough, the company also provides tremendous income thanks to a 5% dividend yield. As rates start to come down later in 2023 it will make income stocks like DOW all the more attractive boosting its already impressive upside potential.

Want to Discover More Value Stocks?

DOW is just 1 of 7 attractive value stocks found in a new special report we just put together. Click the link below to claim your free copy now:

7 SEVERELY Undervalued Stocks

What To Do Next?

Watch my brand new presentation: “2023 Stock Market Outlook” covering:

  • Why 2023 is a “Jekyll & Hyde” year for stocks
  • 5 Warnings Signs the Bear Returns in Early 2023
  • 8 Trades to Profit on the Way Down
  • Plan to Bottom Fish @ Market Bottom
  • 2 Trades with 100%+ Upside Potential as New Bull Emerges
  • And Much More!

Watch Now: “2023 Stock Market Outlook” >

Wishing you a world of investment success!


Steve Reitmeister…but everyone calls me Reity (pronounced “Righty”)
CEO, Stock News Network and Editor, Reitmeister Total Return


DOW shares were trading at $56.01 per share on Thursday morning, down $0.83 (-1.46%). Year-to-date, DOW has gained 11.15%, versus a 1.53% rise in the benchmark S&P 500 index during the same period.


About the Author: Steve Reitmeister

Steve is better known to the StockNews audience as “Reity”. Not only is he the CEO of the firm, but he also shares his 40 years of investment experience in the Reitmeister Total Return portfolio. Learn more about Reity’s background, along with links to his most recent articles and stock picks.

More…

The post Is Dow Inc. (DOW) a Top Value Stock in 2023? appeared first on StockNews.com

https://www.entrepreneur.com/finance/is-dow-inc-dow-a-top-value-stock-in-2023/443419