Is a Beat in Store for HCA Healthcare’s (HCA) Q4 Earnings?

This story originally appeared on Zacks

HCA Healthcare, Inc. HCA is scheduled to release fourth-quarter 2021 results on Jan 27, before the market opens.
HCA’s third-quarter 2021 adjusted earnings of $4.57 per share beat the Zacks Consensus Estimate of $4.10 by 11.5%. The bottom line also improved 138% year over year on higher revenues.
It witnessed solid patient volumes in the quarter.

– Zacks

Earnings Surprise History

HCA boasts an encouraging earnings surprise record. The bottom line beat estimates in all the last four quarters, the average being 21.67%. This is depicted in the chart below:
Here is what our quantitative model predicts:

Factors to Note

In the to-be-reported quarter, HCA is expected to have witnessed higher patient volume, likely contributing to its revenues. The consensus mark for the same stands at $15.41 billion, indicating an upside of 7.8% from year-ago quarter’s reported figure.
Other factors aiding its top line are increased inpatient admissions, outpatient surgeries, etc.
HCA Healthcare is likely to have gained from better payer mix of its commercial business in the fourth quarter of 2021.
The Zacks Consensus Estimate for fourth-quarter earnings is pegged at $4.55, indicating a rise of 10.2% from the year-earlier quarter’s reported figure. This upside is likely to have been backed by improved revenues.
HCA’s increased number of outpatient facilities might have provided a boost to patient admissions in the to-be-reported quarter. The Zacks Consensus Estimate for admissions implies a 6.3% improvement from the year-ago period’s reported figure.
HCA Healthcare is likely to have continued with its dividend payout and share buyback plan, both of which were resumed earlier this year. This might have lent an extra cushion to its performance.
The consensus estimate for fourth-quarter patient days suggests a 6.4% rise from the year-ago quarter’s actuals.
HCA’s performance is likely to have suffered elevated expenses due to higher operating costs and substantial growth-related investments.

What Our Quantitative Model Predicts

Our proven model predicts an earnings beat for HCA Healthcare this time around. The combination of a positive Earnings ESP  and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat as you can see below.
Earnings ESP: HCA Healthcare has an Earnings ESP of +1.07%. This is because the Most Accurate Estimate of $4.60 is pegged higher than the Zacks Consensus Estimate of $4.55. You can uncover the best stocks to buy or sell before they’re reported with our  Earnings ESP Filter.
Zacks Rank: HCA Healthcare currently carries a Zacks Rank #3. You can see the complete list of today’s Zacks #1 Rank stocks here.

Other Stocks to Consider

Here are some other stocks worth considering from the medical sector with the perfect mix of elements to surpass estimates in their upcoming releases:
Bausch Health Companies Inc. BHC has an Earnings ESP of +3.24% and a Zacks Rank of 3, currently.
Community Health Systems, Inc. CYH has an Earnings ESP of +23.00% and is a #2 Ranked player, presently.
bluebird bio, Inc. BLUE has an Earnings ESP of +26.20% and is Zacks #3 Ranked, presently.
Stay on top of upcoming earnings announcements with the Zacks Earnings Calendar.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Community Health Systems, Inc. (CYH): Free Stock Analysis Report
 
HCA Healthcare, Inc. (HCA): Free Stock Analysis Report
 
bluebird bio, Inc. (BLUE): Free Stock Analysis Report
 
Bausch Health Cos Inc. (BHC): Free Stock Analysis Report
 
To read this article on Zacks.com click here.

https://www.entrepreneur.com/article/414798


Pfizer’s (PFE), OPKO’s BLA for Somatrogon Gets CRL From FDA

This story originally appeared on Zacks

Pfizer Inc. PFE, along with partner OPKO Health, Inc. OPK, announced that the FDA has issued a Complete Response Letter (“CRL”) to the biologics license application (“BLA”) for somatrogon for the treatment of growth hormone deficiency (“GHD”) in pediatric patients.

– Zacks

Shares of both Pfizer and OPKO were down in pre-market trading on Monday following the announcement of the news.

Pfizer and OPKO signed the global deal for somatrogon in 2014, per which OPKO is mainly responsible for clinical development while Pfizer will take care of commercializing the product.

Pfizer is currently evaluating the FDA’s comments and is looking to work with the regulatory body to decide the best path forward for somatrogon.

Per the press release, GHD affects one out of approximately 4,000-10,000 children. Somatrogon is a long-acting recombinant human growth hormone that will be administered once weekly, following approval.

Shares of Pfizer have rallied 41.6% in the past year compared with the industry’s increase of 9.7%.

Zacks Investment ResearchImage Source: Zacks Investment Research

Shares of OPKO have plunged 15.6% in the past year compared with the industry’s decrease of 10.5%.

Zacks Investment ResearchImage Source: Zacks Investment Research

Earlier this month, Japan’s Ministry of Health, Labour and Welfare approved NGENLA (somatrogon) Inj. 24 mg Pens and 60 mg Pens for the indication of short stature resulting from GHD without closed epiphyses (another term for pineal gland).

In January 2021, the FDA accepted the BLA for somatrogon to treat pediatric patients with GHD. A decision from the regulatory body was expected in October 2021.

In September 2021, the review period for the BLA for somatrogon was further extended by three months. A decision from the FDA was then expected in January 2022. The extension of the review period by the FDA is a result of the submission of additional data by Pfizer in addition to the data submitted at the time of the initial BLA filing.

The latest CRL from the FDA is expected to further delay the approval for somatrogon in the United States.

In December 2021, the European Medicines Agency’s Committee for Medicinal Products for Human Use rendered a positive opinion on, and recommended marketing authorization for somatrogon to treat pediatric GHD. A decision from the European Commission (“EC”) is expected shortly.

In January 2022, the EC granted marketing authorization to Ascendis Pharma’s ASND TransCon hGH (Lonapegsomatropin Ascendis Pharma) for treating GHD in children and adolescents aged between three to 18.

In August 2021, Ascendis announced that the FDA approved TransCon hGH (under the trade name of Skytrofa) as a treatment for growth failure due to inadequate secretion of endogenous growth hormone in pediatric patients aged one or above and weighing at least 11.5 kg.

Zacks Rank & Key Pick

Pfizer currently carries a Zacks Rank #1 (Strong Buy) while OPKO currently carries a Zacks Rank #3 (Hold). A top-ranked stock in the drug/biotech sector is Alkermes plc ALKS, which flaunts a Zacks Rank #1 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.

Alkermes’ earnings estimates have been revised 1.4% upward for 2022 over the past 60 days. The stock has increased 5% in the past year.

Alkermes’ earnings have surpassed estimates in each of the trailing four quarters.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Pfizer Inc. (PFE): Free Stock Analysis Report
 
Alkermes plc (ALKS): Free Stock Analysis Report
 
OPKO Health, Inc. (OPK): Free Stock Analysis Report
 
Ascendis Pharma AS (ASND): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/414801


Is AllianceBernstein (AB) a Solid Growth Stock? 3 Reasons to Think ” Yes “

This story originally appeared on Zacks

Growth stocks are attractive to many investors, as above-average financial growth helps these stocks easily grab the market’s attention and produce exceptional returns. However, it isn’t easy to find a great growth stock.

– Zacks

By their very nature, these stocks carry above-average risk and volatility. Moreover, if a company’s growth story is over or nearing its end, betting on it could lead to significant loss.

However, the Zacks Growth Style Score (part of the Zacks Style Scores system), which looks beyond the traditional growth attributes to analyze a company’s real growth prospects, makes it pretty easy to find cutting-edge growth stocks.

Our proprietary system currently recommends AllianceBernstein (AB) as one such stock. This company not only has a favorable Growth Score, but also carries a top Zacks Rank.

Research shows that stocks carrying the best growth features consistently beat the market. And returns are even better for stocks that possess the combination of a Growth Score of A or B and a Zacks Rank #1 (Strong Buy) or 2 (Buy).

While there are numerous reasons why the stock of this investment management company is a great growth pick right now, we have highlighted three of the most important factors below:

Earnings Growth

Earnings growth is arguably the most important factor, as stocks exhibiting exceptionally surging profit levels tend to attract the attention of most investors. For growth investors, double-digit earnings growth is highly preferable, as it is often perceived as an indication of strong prospects (and stock price gains) for the company under consideration.

While the historical EPS growth rate for AllianceBernstein is 10.3%, investors should actually focus on the projected growth. The company’s EPS is expected to grow 9.7% this year, crushing the industry average, which calls for EPS growth of 8.8%.

Impressive Asset Utilization Ratio

Asset utilization ratio — also known as sales-to-total-assets (S/TA) ratio — is often overlooked by investors, but it is an important indicator in growth investing. This metric shows how efficiently a firm is utilizing its assets to generate sales.

Right now, AllianceBernstein has an S/TA ratio of 2.65, which means that the company gets $2.65 in sales for each dollar in assets. Comparing this to the industry average of 0.35, it can be said that the company is more efficient.

In addition to efficiency in generating sales, sales growth plays an important role. And AllianceBernstein is well positioned from a sales growth perspective too. The company’s sales are expected to grow 11% this year versus the industry average of 7.8%.

Promising Earnings Estimate Revisions

Beyond the metrics outlined above, investors should consider the trend in earnings estimate revisions. A positive trend is a plus here. Empirical research shows that there is a strong correlation between trends in earnings estimate revisions and near-term stock price movements.

The current-year earnings estimates for AllianceBernstein have been revising upward. The Zacks Consensus Estimate for the current year has surged 6.5% over the past month.

Bottom Line

While the overall earnings estimate revisions have made AllianceBernstein a Zacks Rank #1 stock, it has earned itself a Growth Score of B based on a number of factors, including the ones discussed above.

You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

This combination indicates that AllianceBernstein is a potential outperformer and a solid choice for growth investors.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
AllianceBernstein Holding L.P. (AB): Free Stock Analysis Report
 
To read this article on Zacks.com click here.

https://www.entrepreneur.com/article/414803


Onto Innovation (ONTO) is an Incredible Growth Stock: 3 Reasons Why

This story originally appeared on Zacks

Growth investors focus on stocks that are seeing above-average financial growth, as this feature helps these securities garner the market’s attention and deliver solid returns. But finding a great growth stock is not easy at all.

– Zacks

That’s because, these stocks usually carry above-average risk and volatility. In fact, betting on a stock for which the growth story is actually over or nearing its end could lead to significant loss.

However, the task of finding cutting-edge growth stocks is made easy with the help of the Zacks Growth Style Score (part of the Zacks Style Scores system), which looks beyond the traditional growth attributes to analyze a company’s real growth prospects.

Onto Innovation (ONTO) is one such stock that our proprietary system currently recommends. The company not only has a favorable Growth Score, but also carries a top Zacks Rank.

Studies have shown that stocks with the best growth features consistently outperform the market. And returns are even better for stocks that possess the combination of a Growth Score of A or B and a Zacks Rank #1 (Strong Buy) or 2 (Buy).

Here are three of the most important factors that make the stock of this maker of semiconductor manufacturing equipment a great growth pick right now.

Earnings Growth

Earnings growth is arguably the most important factor, as stocks exhibiting exceptionally surging profit levels tend to attract the attention of most investors. And for growth investors, double-digit earnings growth is definitely preferable, and often an indication of strong prospects (and stock price gains) for the company under consideration.

While the historical EPS growth rate for Onto Innovation is 15.4%, investors should actually focus on the projected growth. The company’s EPS is expected to grow 19% this year, crushing the industry average, which calls for EPS growth of 15.3%.

Cash Flow Growth

While cash is the lifeblood of any business, higher-than-average cash flow growth is more important and beneficial for growth-oriented companies than for mature companies. That’s because, growth in cash flow enables these companies to expand their businesses without depending on expensive outside funds.

Right now, year-over-year cash flow growth for Onto Innovation is 136.3%, which is higher than many of its peers. In fact, the rate compares to the industry average of -15.7%.

While investors should actually consider the current cash flow growth, it’s worth taking a look at the historical rate too for putting the current reading into proper perspective. The company’s annualized cash flow growth rate has been 62.2% over the past 3-5 years versus the industry average of 55.2%.

Promising Earnings Estimate Revisions

Beyond the metrics outlined above, investors should consider the trend in earnings estimate revisions. A positive trend is a plus here. Empirical research shows that there is a strong correlation between trends in earnings estimate revisions and near-term stock price movements.

The current-year earnings estimates for Onto Innovation have been revising upward. The Zacks Consensus Estimate for the current year has surged 1.1% over the past month.

Bottom Line

While the overall earnings estimate revisions have made Onto Innovation a Zacks Rank #2 stock, it has earned itself a Growth Score of A based on a number of factors, including the ones discussed above.

You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

This combination indicates that Onto Innovation is a potential outperformer and a solid choice for growth investors.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Onto Innovation Inc. (ONTO): Free Stock Analysis Report
 
To read this article on Zacks.com click here.

https://www.entrepreneur.com/article/414802


Is AutoZone (AZO) a Solid Growth Stock? 3 Reasons to Think ” Yes “

This story originally appeared on Zacks

Growth investors focus on stocks that are seeing above-average financial growth, as this feature helps these securities garner the market’s attention and deliver solid returns. However, it isn’t easy to find a great growth stock.

– Zacks

In addition to volatility, these stocks carry above-average risk by their very nature. Also, one could end up losing from a stock whose growth story is actually over or nearing its end.

However, the Zacks Growth Style Score (part of the Zacks Style Scores system), which looks beyond the traditional growth attributes to analyze a company’s real growth prospects, makes it pretty easy to find cutting-edge growth stocks.

AutoZone (AZO) is on the list of such stocks currently recommended by our proprietary system. In addition to a favorable Growth Score, it carries a top Zacks Rank.

Research shows that stocks carrying the best growth features consistently beat the market. And returns are even better for stocks that possess the combination of a Growth Score of A or B and a Zacks Rank #1 (Strong Buy) or 2 (Buy).

Here are three of the most important factors that make the stock of this auto parts retailer a great growth pick right now.

Earnings Growth

Earnings growth is arguably the most important factor, as stocks exhibiting exceptionally surging profit levels tend to attract the attention of most investors. For growth investors, double-digit earnings growth is highly preferable, as it is often perceived as an indication of strong prospects (and stock price gains) for the company under consideration.

While the historical EPS growth rate for AutoZone is 19.8%, investors should actually focus on the projected growth. The company’s EPS is expected to grow 12.7% this year, crushing the industry average, which calls for EPS growth of 12.4%.

Cash Flow Growth

While cash is the lifeblood of any business, higher-than-average cash flow growth is more important and beneficial for growth-oriented companies than for mature companies. That’s because, growth in cash flow enables these companies to expand their businesses without depending on expensive outside funds.

Right now, year-over-year cash flow growth for AutoZone is 21%, which is higher than many of its peers. In fact, the rate compares to the industry average of 11.4%.

While investors should actually consider the current cash flow growth, it’s worth taking a look at the historical rate too for putting the current reading into proper perspective. The company’s annualized cash flow growth rate has been 10.9% over the past 3-5 years versus the industry average of 8.5%.

Promising Earnings Estimate Revisions

Superiority of a stock in terms of the metrics outlined above can be further validated by looking at the trend in earnings estimate revisions. A positive trend is of course favorable here. Empirical research shows that there is a strong correlation between trends in earnings estimate revisions and near-term stock price movements.

The current-year earnings estimates for AutoZone have been revising upward. The Zacks Consensus Estimate for the current year has surged 0.6% over the past month.

Bottom Line

While the overall earnings estimate revisions have made AutoZone a Zacks Rank #1 stock, it has earned itself a Growth Score of A based on a number of factors, including the ones discussed above.

You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

This combination positions AutoZone well for outperformance, so growth investors may want to bet on it.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
AutoZone, Inc. (AZO): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/414804


Is CGI (GIB) a Solid Growth Stock? 3 Reasons to Think ” Yes “

This story originally appeared on Zacks

Growth stocks are attractive to many investors, as above-average financial growth helps these stocks easily grab the market’s attention and produce exceptional returns. But finding a growth stock that can live up to its true potential can be a tough task.

– Zacks

In addition to volatility, these stocks carry above-average risk by their very nature. Also, one could end up losing from a stock whose growth story is actually over or nearing its end.

However, the Zacks Growth Style Score (part of the Zacks Style Scores system), which looks beyond the traditional growth attributes to analyze a company’s real growth prospects, makes it pretty easy to find cutting-edge growth stocks.

Our proprietary system currently recommends CGI Group (GIB) as one such stock. This company not only has a favorable Growth Score, but also carries a top Zacks Rank.

Studies have shown that stocks with the best growth features consistently outperform the market. And returns are even better for stocks that possess the combination of a Growth Score of A or B and a Zacks Rank #1 (Strong Buy) or 2 (Buy).

Here are three of the most important factors that make the stock of this information technology and business process services company a great growth pick right now.

Earnings Growth

Earnings growth is arguably the most important factor, as stocks exhibiting exceptionally surging profit levels tend to attract the attention of most investors. And for growth investors, double-digit earnings growth is definitely preferable, and often an indication of strong prospects (and stock price gains) for the company under consideration.

While the historical EPS growth rate for CGI is 9.8%, investors should actually focus on the projected growth. The company’s EPS is expected to grow 9.3% this year, crushing the industry average, which calls for EPS growth of 8%.

Impressive Asset Utilization Ratio

Growth investors often overlook asset utilization ratio, also known as sales-to-total-assets (S/TA) ratio, but it is an important feature of a real growth stock. This metric shows how efficiently a firm is utilizing its assets to generate sales.

Right now, CGI has an S/TA ratio of 0.81, which means that the company gets $0.81 in sales for each dollar in assets. Comparing this to the industry average of 0.8, it can be said that the company is more efficient.

While the level of efficiency in generating sales matters a lot, so does the sales growth of a company. And CGI looks attractive from a sales growth perspective as well. The company’s sales are expected to grow 5.4% this year versus the industry average of 4.4%.

Promising Earnings Estimate Revisions

Superiority of a stock in terms of the metrics outlined above can be further validated by looking at the trend in earnings estimate revisions. A positive trend is of course favorable here. Empirical research shows that there is a strong correlation between trends in earnings estimate revisions and near-term stock price movements.

The current-year earnings estimates for CGI have been revising upward. The Zacks Consensus Estimate for the current year has surged 0.5% over the past month.

Bottom Line

CGI has not only earned a Growth Score of B based on a number of factors, including the ones discussed above, but it also carries a Zacks Rank #2 because of the positive earnings estimate revisions.

You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

This combination positions CGI well for outperformance, so growth investors may want to bet on it.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
CGI Group, Inc. (GIB): Free Stock Analysis Report
 
To read this article on Zacks.com click here.

https://www.entrepreneur.com/article/414805


Can These Penny Stocks Climb This Week? 4 To Watch Right Now

4 Penny Stocks to Add to Your Watchlist Right Now

After a more than shaky week of trading for both penny stocks and blue chips, investors are excited to get another week up and going. But, to make money with penny stocks, traders need to do two things. First and foremost, investors need to have a thorough and consistent understanding of what is going on in the stock market. This means knowing what events are occurring, how they will impact specific industries, and how your portfolio will be affected. 

PennyStocks.com – PennyStocks

[Read More] 3 Penny Stocks That Investors Are Watching Right Now And Why

The next thing that investors need to understand is how to trade penny stocks. This means knowing your investing strategy and standard methods for making money with penny stocks. While this may seem straightforward, investors need to consider plenty of nuances in this regard. For example, are you looking for penny stocks to buy and hold in the long term? Or, are you looking to make short-term swing trades? 

Regardless, knowing what type of trader you are is crucial to investing. So, while this is in no way a definitive guide on how to trade penny stocks, it should help to put you in the right direction. With all of that in mind, let’s take a look at three penny stocks to add to your watchlist in late January 2022. 

Penny Stocks to Watch This Week 

  1. WiMi Hologram Cloud Inc. (NASDAQ: WIMI)
  2. Aridis Pharmaceuticals (NASDAQ: ARDS)
  3. Baudax Bio Inc. (NASDAQ: BXRX)
  4. Progenity Inc. (NASDAQ: PROG)

WiMi Hologram Cloud Inc. (NASDAQ: WIMI)

In the past few trading days, shares of WIMI stock have climbed by over 10%. It’s worth noting that we’ve covered WIMI stock numerous times in that period for its consistent movement. One of the most significant pieces of news announced by the company came out on January 20th. It stated that the FCC approved its HoloAR Lens to enter the U.S. market. This is big news and puts WIMI in a great position to grow in the AR industry moving forward.

“WIMI HoloAR Lens, an augmented reality (AR) headset display (HMD) product, has been approved by the FEDERAL Communications Commission to enter the US market and will be widely used in virtual social, virtual entertainment, virtual education, virtual communication and other fields. In the first half of 2021, our global operating revenue increased approximately 202.2% year on year, our gross profit increased 189.8% year on year, our net profit increased 40.3% year on year, and our R&D expenses increased 463.6% year on year.”

The CEO of WIMI, Shi Shuo

These numbers are very exciting and are not yet fully reflected in WIMI’s value. So, for this reason, it could be an interesting penny stock to keep an eye on right now. Whether it’s worth adding to your list of penny stocks to buy, however, is up to you.

Penny_Stocks_to_Watch_WiMi Hologram (WIMI Stock Chart)

Aridis Pharmaceuticals (NASDAQ: ARDS)

Despite being beaten down for the last year, Aridis could be one of the top penny stocks to watch at the start of the week. The reason why has everything to do with events that unfolded late last week.

The biotech company sent out a tweet that read: “We are rescheduling our group call, as we have some very exciting #news coming. Stay tuned!”

But here’s the thing, that tweet has since been deleted.

ARDS removed tweet

Regardless, thanks to the uptick in new virus cases, Aridis has been in the spotlight. CEO Vu Truong, Ph.D. was interviewed on Fox Business last month and discussed the company’s pipeline including AR-701. The candidate has shown broad “potent neutralization” against all variants tested. The platform is designed to provide relevant drug levels “for up to 1 year” from prophylactic or therapeutic treatment according to the company. Shares surged in post-market trading on January 21.

In light of the interesting activity last week, the removed tweet, and a recently filed prospectus to raise up to $25 million, there’s a lot to be aware of right now. Whether this bullish trend continues or not is to be seen. But based on late afternoon trading to close the week last week, ARDS could be on the watch list to see how things being this week.

Baudax Bio Inc. (NASDAQ: BXRX)

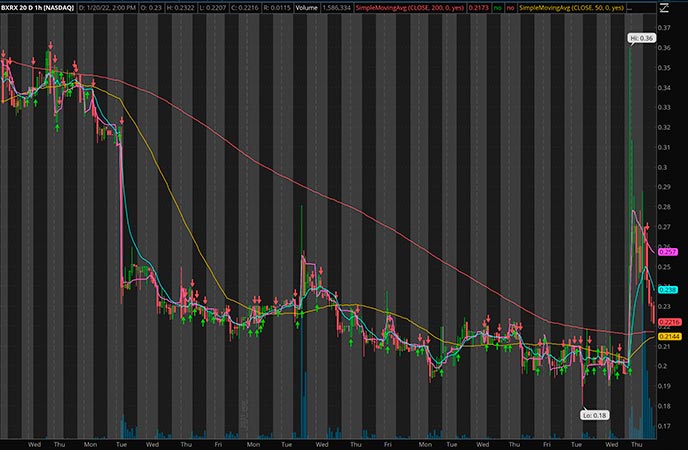
Another penny stock that has been in the news recently is Baudax Bio Inc. Despite shooting down in value by over 85% in the past year, we’ve seen shares of BXRX stock begin to push up recently. If you’re not familiar, Baudax Bio is a pharmaceutical company working on the commercialization and development of innovative products.

[Read More] 5 Hot Meme Stocks To Buy For Pennies Right Now

Additionally, the company states that it produces ANJESO, a 24-hour intravenous NSAID for moderate to severe pain. Additionally, it has a sizable pipeline consisting of other drugs such as neuromuscular blocking agents and a proprietary chemical reversal agent for these NMBAs. A few weeks ago, the company announced a $4.2 million registered direct offering with H.C. Wainwright & Co.

The company plans to use these funds to commercialize ANJESO and develop other drugs in its clinical pipeline. Right now, there is a significant emphasis on biotech penny stocks. So, with that in mind, will BXRX be on your penny stocks watchlist moving forward?

Penny_Stocks_to_Watch_Baudax

Progenity Inc. (NASDAQ: PROG)

Progenity is another penny stock that we’ve covered numerous times in the past few months. If you’re not familiar, it is a biotech penny stock that develops products for use in gastrointestinal disorders and much more. Additionally, the company is developing molecular testing products as well as ingestible devices for diagnostic samples, genomics, and more.

The company’s primary focus is on making medicine as precise as possible through treatment personalization and the local delivery of drugs. Progenity also has a strong portfolio of drugs in its pipeline, such as Preecludia. In the past month, shares of PROG stock have dropped by around 40%. But, from the end of September through mid-November, shares jumped by over 200% before correcting.

So while Progenity can be highly volatile, it does look like it could have a lot to offer. As stated earlier, there is a significant emphasis right now on biotech penny stocks. Because of this, investors are watching PROG stock for what it could do in the future. With all of that considered, does PROG deserve a spot on your list of penny stocks to buy or not?

Penny_Stocks_to_Watch_Progenity

Which Penny Stocks Are You Watching Right Now?

If you’re looking for the best penny stocks to buy, there are hundreds of options to choose from. While it can be challenging to pick just a handful for your watchlist, investors can utilize the information they have on hand to do just that. Right now, there are plenty of factors that traders need to consider before investing.

[Read More] 3 Penny Stocks Under $1 For You List This Week

First and foremost, investors should have a well-thought-out trading strategy that adapts to the current stock market. Second, traders need to consider how current events will impact both industries at large and the penny stocks in their portfolios.

So, while it may be challenging to do so, there are many options to make money with penny stocks. But, it takes a commitment to understand the market and never trade with emotion. Considering all of this, which penny stocks are you watching right now?


If you enjoyed this article and you’re interested in learning how to trade so you can have the best chance to profit consistently then you need to checkout this YouTube channel. CLICK HERE RIGHT NOW!


https://www.entrepreneur.com/article/414638


Intel Is the Perfect Stock To Buy When the Chips are Down

Time to use fear to your advantage with a covered call trade on POWR Buy rated value stock INTC.

shutterstock.com – StockNews

To say the market has started the year off on the wrong foot is an understatement. This is especially true in the high beta NASDAQ growth names. The Nazzy is now off to the worst start to a year since 2008.

Nervousness about the markets is evident. Both the VIX and VXN -or VIX of the NASDAQ-  are near the highest levels of the past 12 months. Volatility is at an extreme. Important to remember, however, that volatility begets opportunity. Warren Buffett said as much when he stated “Be Greedy When Others Are Fearful”. Time to get a little greedy and add some lower risk, lower beta exposure names to the portfolio at lower prices.

2022 may finally be the year when value stocks outperform growth. This is especially true given that the Fed will be raising rates for the first time since 2018 plus begin to taper in earnest. Rising rates not only pressure profit margins for corporations but also compress valuation multiples such as P/E and P/S. Stocks like Microsoft will no longer be valued at 13x on a P/S basis.

This is a great time to sift through the recent rubble to uncover value stocks that look poised to be potential outperformers in this market environment. One name that fits the bill is Intel.

INTC has a POWR Rating of B – Buy. It is in the A Rated Semiconductor and Wireless Chip Industry and ranks a solid number 11 within the group of 100. The Value Grade is A while Growth is a D. This is ideal for the value beating growth thesis alluded to earlier.

Valuation View

Intel is certainly cheap from a fundamental perspective. Current P/E is just over 10 and well below the median of 12.73 seen over the past decade. Price/Sales well under 3 and nearing the lowest multiple since 2017.

INTC is also cheap on a comparative basis. A look at the table below shows just how much of a discount Intel is trading at compared to the rest of the peer group.

Technical Take

Shares of INTC are nearing oversold readings on a technical basis. 9-day RSI is approaching 30 while MACD is now negative. Momentum is below zero while Bollinger Percent B is getting to that level as well. The stock is trading at a discount to the 20-day moving average.

Intel did hold the major support area at $52 and was unchanged on Friday while the overall market got clobbered. This further supports the value thesis.

INTC is also looking good on a comparative technical basis. The stock had been on huge underperformer over the past 200 days to the other semiconductor stocks (SMH). That relative performance is beginning to revert to the mean. Look for that reversion to continue and for INTC to be an outperformer over the coming weeks.

Intel is also one of the Dogs of the Dow for 2022. This means it is the top ten for dividend yield of the 30 Dow stocks. The current yield is 2.67% with a low payout ratio of just 27%. This solid dividend payout will help serve to buffer volatility and add to overall return.

Volatility, and especially implied volatility, is at an extreme following the recent market carnage. INTC options are now trading at the 100th percentile. This means option prices in the past year haven’t been more expensive than they are right now. It is also many times a reliable contrarian bullish signal given that the fear is getting to an extreme.

Investors looking to add the POWR Buy INTC to the portfolio may also want to take advantage of the uber-expensive option pricing by using a covered call strategy. This means you sell a call option versus every 100 shares of Intel stock you buy. Selling the call reduces you overall risk by the premium received while capping off upside gains at the strike price sold. It is an effective way to lower downside risk while still leaving upside room for price appreciation.

For example, selling the January 2023 $55 call at $5.45 would reduce the cost of buying INTC stock at $52.04 by 11.5% to roughly $46.60 ($52.04 stock bought less $5.45 option sold). It does cap off the upside at $55 which would equate to an 18% return, plus dividends received along the way, if the stock is above $55 next January.

Earnings are due January 26 with a whisper number of $1.07 EPS on $18.39 billion in revenue.

Intel offers investors the rare combination of a cheap stock with expensive options. It may be time to get a little greedy and look to add INTC along with a covered call to your portfolio. In the words of the immortal Gordon Gekko, “Greed is Good”.


INTC shares closed at $52.04 on Friday, down $0.00 (0.00%). Year-to-date, INTC has gained 1.05%, versus a -7.79% rise in the benchmark S&P 500 index during the same period.


About the Author: Tim Biggam

Tim spent 13 years as Chief Options Strategist at Man Securities in Chicago, 4 years as Lead Options Strategist at ThinkorSwim and 3 years as a Market Maker for First Options in Chicago. He makes regular appearances on Bloomberg TV and is a weekly contributor to the TD Ameritrade Network “Morning Trade Live”. His overriding passion is to make the complex world of options more understandable and therefore more useful to the everyday trader. Tim is the editor of the POWR Options newsletter. Learn more about Tim’s background, along with links to his most recent articles.

More…

The post Intel Is the Perfect Stock To Buy When the Chips are Down appeared first on StockNews.com

https://www.entrepreneur.com/article/414599


Is Bark Inc. Stock a Buy After Announcing a New CEO?

Pet care retailer Bark, Inc. (BARK) announced on January 10 that its co-founder and executive chairman Matt Meeker is resuming his CEO position after a brief hiatus. The stock has gained more than 7% in price since the news broke. However, with bleak earnings growth projections, is BARK an ideal investment now? Read more to find out.

shutterstock.com – StockNews
New York City’s BARK, Inc. (BARK) is a leading global retailer of dog products. On June 2, 2021, the company went public through an SPAC deal. It merged with blank check company Northern Star Acquisition Corp. and raised $427 million in cash proceeds.

On January 10, BARK’s co-founder and Executive Chairman, Matt Meeker, became the company’s CEO. Meeker had previously served as BARK’s CEO for nine years following the company’s inception in 2011. Following his reappointment, Meeker said, “I am eager to resume the role of Chief Executive Officer and build on the momentum that Manish and the talented team at BARK have achieved…I believe that the next few years will be transformative for BARK as we leverage our scale and brand to grow our footprint in areas like food and health—initiatives that I am passionate about personally.”

Shares of BARK have gained 7.7% in price since the appointment news to close yesterday’s trading session at $3.66. However, the stock has declined 13.3% year-to-date.

Here is what could shape BARK’s performance in the near term:

Negative Profit Margins

BARK’s trailing-12-month net income margin stands at negative 11.07%, Its EBITDA margin is negative 11.65%, while its levered free cash flow margin is negative 22.22%. In addition, the company’s trailing-12-month ROE, ROA, and ROTC are negative 82.25%, 11.21%, and 21.69%, respectively.

Bleak Financials

For its fiscal 2022 second quarter, ended Sept. 30, 2021, BARK’s revenues increased 39.1% year-over-year to $120.16 million. Its gross profit came in at $69.89 million, up 35.6% from the same period last year.

However, the company’s loss from operations widened by 2,158.3% from the prior-year quarter to $15.42 million. This can be attributed to a 63.3% rise in its total operating expenses. Its net income amounted to $6.46 million due to a $23.18 million gain from changes in the fair value of warrant liabilities. Excluding such gains, BARK’s net loss stands at $16.72 million.

POWR Ratings Reflect Bleak Prospects

BARK has an overall D rating, which equates to Sell in our proprietary POWR Ratings system. The POWR Ratings are calculated by considering 118 distinct factors, with each factor weighted to an optimal degree.

BARK has a D grade for Quality and Value. The company’s negative profit margins justify the Quality grade. In addition, BARK’s negative forward P/E multiple is in sync with the Value grade.

Of 46 stocks in the Specialty Retailers industry, BARK is ranked #41.

In addition to the grades I have highlighted above, view BARK ratings for Growth, Momentum, Stability, and Sentiment here.

Bottom Line

Since the pandemic, the demand for pet products has skyrocketed because  more people than usual have been keen to adopt pets because they work remotely. While BRK’s revenue growth reflects the industry tailwinds, the company has failed to generate profits. Given the increasing competition in the pet care industry, BARK’s negative profit margins might limit its growth potential over the long run. Analysts expect the company’s EPS to remain negative until at least this year. Thus, we think the stock is best avoided now.

How Does BARK, Inc. (BARK) Stack Up Against its Peers?

While BARK has a D rating in our proprietary rating system, one might want to consider looking at its industry peers, Destination XL Group, Inc. (DXLG), Cato Corporation (CATO), and Tile Shop Holdings, Inc. (TTSH), which have an A (Strong Buy) rating.

Note that DXLG is one of the few stocks handpicked by our Chief Growth Strategist, Jaimini Desai, currently in the POWR Stocks Under $10 portfolio. Learn more here.


BARK shares were trading at $3.45 per share on Friday morning, down $0.21 (-5.74%). Year-to-date, BARK has declined -18.25%, versus a -7.17% rise in the benchmark S&P 500 index during the same period.


About the Author: Aditi Ganguly

Aditi is an experienced content developer and financial writer who is passionate about helping investors understand the do’s and don’ts of investing. She has a keen interest in the stock market and has a fundamental approach when analyzing equities.

More…

The post Is Bark Inc. Stock a Buy After Announcing a New CEO? appeared first on StockNews.com

https://www.entrepreneur.com/article/414455


3 Stocks to Buy if You Think Inflation Will Keep Trending Higher This Year

The chemical industry has experienced a solid rebound from its pandemic-driven travails, fueled by strong demand from industrial and agricultural activities. Amid this environment, we believe investors should bet on companies in this sector that possess sufficiently strong pricing power to weather any demand slump triggered by increasing inflation. So, with this in mind, we think Olin Corporation (OLN), The Chemours (CC), and FMC Corporation (FMC) possess solid growth prospects and are worth adding to one’s portfolio now. Read on.

shutterstock.com – StockNews

Chemical stocks have been witnessing a sharp rebound from the pandemic’s negative effects since last year. Notably, an inflationary environment in the United States and the rapid rebound of global industrial and agricultural activity have been significant factors pushing chemical prices higher.

Though chemical companies are dealing with rising raw material costs and higher supply chain and logistical expenses, steps to raise chemical product selling prices to offset cost inflation and supply chain tightness, productivity improvement measures, and operational efficiency improvements helped the chemical industry to maintain its margins through the second half of 2021.

Therefore, even if inflation keeps trending higher, we think it could be wise to bet on fundamentally-sound chemicals stocks Olin Corporation (OLN), The Chemours Company (CC), and FMC Corporation (FMC). They possess impressive growth attributes.

Olin Corporation (OLN)

OLN in Clayton, Miss., produces and sells chemical products in the United States, Europe, and globally. It operates in three segments: Chlor Alkali Products and Vinyls; Epoxy; and Winchester. The company markets its products through its sales personnel as well as directly to various industrial clients, mass merchants, retailers, wholesalers, other distributors, and the United States Government and its prime contractors.

OLN’s board of directors authorized a new $1.0 billion share buyback program in November. Under the program, shares of the company’s common stock may be repurchased periodically, either on the open market or in privately negotiated deals. This exhibits the company’s robust cash flow generating capabilities.

OLN’s net sales increased 62.8% year-over-year to $2.34 billion in the third quarter, ended Sept. 30, 2021. Its operating income came in at $549 million, versus a $683.8 million operating loss in the prior-year quarter. The company reported $390.7 million in net income, compared to a $736.8 million net loss in the third quarter of 2020. Its EPS was  $2.38 over this period.

The company’s EPS is expected to grow 878.4% year-over-year to $8.64 in its fiscal 2021. Analysts expect OLN’s revenue to increase 53.3% year-over-year to $8.83 billion in fiscal 2021. The stock has gained 89.8% in price over the past year and 27% over the past nine months.

OLN’s POWR Ratings reflect this promising outlook. The company has an overall A rating, which translates to Strong Buy in our proprietary rating system. The POWR Ratings assess stocks by 118 distinct factors, each with its own weighting.

OLN is also rated B  for Growth, Momentum, and Value. Within the A-rated Chemicals industry, it is ranked #11 of 89 stocks. To see additional POWR Ratings for Quality, Stability, and Sentiment for OLN, click here.

Note that OLN is one of the few stocks handpicked currently in the Reitmeister Total Return portfolio. Learn more here.

The Chemours Company (CC)

CC in Wilmington, Del., offers performance chemicals across North America, Asia Pacific, Europe, the Middle East, Africa, and Latin America. Titanium Technologies; Thermal & Specialized Solutions; Advanced Performance Materials; and Chemical Solutions are its four operational segments. The company offers its products both directly and through a network of resellers and distributors.

In November, CC launched GlycleanTM D, a proven broad-spectrum disinfectant and cleaner that has been registered with the U.S. Environmental Protection Agency (EPA) to deactivate the SARS-CoV-2 virus as well as other viruses and bacteria.

During the third quarter, ended Sept. 30, 2021, CC’s net sales increased 36.3% year-over-year to $1.68 billion. Its gross profit grew 66.1% from its year-ago value to $427 million, while its net income surged 181.6% year-over-year to $214 million over this period. The company’s EPS increased 176.1% from its  year-ago value to $1.27.

A $4.11 consensus EPS estimate for its fiscal 2021 represents a 107.6% improvement year-over-year. Analysts expect CC’s revenue to increase 27.6% year-over-year to $6.34 billion in its fiscal 2021. The stock has gained 21.1% in price over the past year and 9.5% over the past month.

CC’s strong fundamentals are reflected in its POWR Ratings. The stock has an overall A rating, which equates to Strong Buy in our POWR Ratings system. The stock also has an A grade for Value and a B for Growth and Quality. In the Chemicals industry, it is ranked #12.

In total, we rate CC on eight distinct levels. Beyond what we have stated above, we have also given CC grades for Stability, Momentum, and Sentiment. Get all the CC ratings here.

FMC Corporation (FMC)

FMC specializes in agricultural sciences and offers crop protection, plant health, precision agriculture, and professional pest and turf management solutions. The Philadelphia, Pa.-based concern provides its products to farmers directly and through individual distributors and co-ops, national and regional distributors, and national and regional distributors.

Last month, FMC signed multi-year agreements with Corteva Agriscience to supply Rynaxypyr and Cyazypyr actives for seed treatment products. These multi-year agreements expand the two companies’ current global relationship.

For the third quarter, ended Sept.30, 2021, FMC’s revenue increased 10.1% year-over-year to $1.19 billion. Its net income grew 41.7% from its year-ago value to $157.9 million, while its EPS increased 43.5% year-over-year to $1.22. In addition, the company’s adjusted EBITDA surged 12%from the prior-year quarter to $293 million.

Analysts expect FMC’s revenue to increase 7.8% year-over-year to $5 billion in fiscal 2021. In addition, the company’s EPS is expected to grow 10% in fiscal 2021. Over the past month, the stock has gained 6.9% in price. Also, it has returned 17.6% over the past three months.

FMC’s POWR Ratings reflect this promising outlook. The company has an overall B, which translates to Buy in our proprietary rating system. FMC is also rated B grade for Quality, Growth, and Sentiment. Within the Chemicals industry, it is ranked #19.

Click here to see additional POWR Ratings for Stability, Value, and Momentum for FMC.


OLN shares were trading at $49.08 per share on Friday morning, down $1.07 (-2.13%). Year-to-date, OLN has declined -14.67%, versus a -6.64% rise in the benchmark S&P 500 index during the same period.


About the Author: Pragya Pandey

Pragya is an equity research analyst and financial journalist with a passion for investing. In college she majored in finance and is currently pursuing the CFA program and is a Level II candidate.

More…

The post 3 Stocks to Buy if You Think Inflation Will Keep Trending Higher This Year appeared first on StockNews.com

https://www.entrepreneur.com/article/414454