Marvell Technology (MRVL) Tops Q3 Earnings and Revenue Estimates

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Marvell Technology (MRVL) came out with quarterly earnings of $0.43 per share, beating the Zacks Consensus Estimate of $0.38 per share. This compares to earnings of $0.25 per share a year ago. These figures are adjusted for non-recurring items.

– Zacks

This quarterly report represents an earnings surprise of 13.16%. A quarter ago, it was expected that this chipmaker would post earnings of $0.31 per share when it actually produced earnings of $0.34, delivering a surprise of 9.68%.

Over the last four quarters, the company has surpassed consensus EPS estimates four times.

Marvell, which belongs to the Zacks Technology Services industry, posted revenues of $1.21 billion for the quarter ended October 2021, surpassing the Zacks Consensus Estimate by 5.53%. This compares to year-ago revenues of $750.14 million. The company has topped consensus revenue estimates times over the last four quarters.

The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.

Marvell shares have added about 49.2% since the beginning of the year versus the S&P 500’s gain of 20.2%.

What’s Next for Marvell?

While Marvell has outperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?

There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.

Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.

Ahead of this earnings release, the estimate revisions trend for Marvell: mixed. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #3 (Hold) for the stock. So, the shares are expected to perform in line with the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $0.43 on $1.21 billion in revenues for the coming quarter and $1.45 on $4.28 billion in revenues for the current fiscal year.

Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Technology Services is currently in the bottom 32% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.

One other stock from the broader Zacks Business Services sector, Paychex (PAYX), is yet to report results for the quarter ended November 2021.

This payroll processor and human-resources services provider is expected to post quarterly earnings of $0.79 per share in its upcoming report, which represents a year-over-year change of +8.2%. The consensus EPS estimate for the quarter has remained unchanged over the last 30 days.

Paychex’s revenues are expected to be $1.06 billion, up 7.7% from the year-ago quarter.

Infrastructure Stock Boom to Sweep America

A massive push to rebuild the crumbling U.S. infrastructure will soon be underway. It’s bipartisan, urgent, and inevitable. Trillions will be spent. Fortunes will be made.

The only question is “Will you get into the right stocks early when their growth potential is greatest?”

Zacks has released a Special Report to help you do just that, and today it’s free. Discover 5 special companies that look to gain the most from construction and repair to roads, bridges, and buildings, plus cargo hauling and energy transformation on an almost unimaginable scale.

Download FREE: How to Profit from Trillions on Spending for Infrastructure >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Marvell Technology, Inc. (MRVL): Free Stock Analysis Report
 
Paychex, Inc. (PAYX): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/400553


Ooma (OOMA) Surpasses Q3 Earnings and Revenue Estimates

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Ooma (OOMA) came out with quarterly earnings of $0.13 per share, beating the Zacks Consensus Estimate of $0.09 per share. This compares to earnings of $0.13 per share a year ago. These figures are adjusted for non-recurring items.

– Zacks

This quarterly report represents an earnings surprise of 44.44%. A quarter ago, it was expected that this internet phone service provider would post earnings of $0.09 per share when it actually produced earnings of $0.13, delivering a surprise of 44.44%.

Over the last four quarters, the company has surpassed consensus EPS estimates four times.

Ooma, which belongs to the Zacks Communication – Components industry, posted revenues of $49.17 million for the quarter ended October 2021, surpassing the Zacks Consensus Estimate by 2.40%. This compares to year-ago revenues of $42.97 million. The company has topped consensus revenue estimates four times over the last four quarters.

The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.

Ooma shares have added about 30.6% since the beginning of the year versus the S&P 500’s gain of 20.2%.

What’s Next for Ooma?

While Ooma has outperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?

There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.

Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.

Ahead of this earnings release, the estimate revisions trend for Ooma: mixed. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #3 (Hold) for the stock. So, the shares are expected to perform in line with the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $0.09 on $48.77 million in revenues for the coming quarter and $0.43 on $189.42 million in revenues for the current fiscal year.

Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Communication – Components is currently in the bottom 17% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.

One other stock from the broader Zacks Computer and Technology sector, Aspen Group Inc. (ASPU), is yet to report results for the quarter ended October 2021. The results are expected to be released on December 14.

This company is expected to post quarterly loss of $0.03 per share in its upcoming report, which represents a year-over-year change of +40%. The consensus EPS estimate for the quarter has remained unchanged over the last 30 days.

Aspen Group Inc.’s revenues are expected to be $20.27 million, up 19.5% from the year-ago quarter.

Infrastructure Stock Boom to Sweep America

A massive push to rebuild the crumbling U.S. infrastructure will soon be underway. It’s bipartisan, urgent, and inevitable. Trillions will be spent. Fortunes will be made.

The only question is “Will you get into the right stocks early when their growth potential is greatest?”

Zacks has released a Special Report to help you do just that, and today it’s free. Discover 5 special companies that look to gain the most from construction and repair to roads, bridges, and buildings, plus cargo hauling and energy transformation on an almost unimaginable scale.

Download FREE: How to Profit from Trillions on Spending for Infrastructure >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Ooma, Inc. (OOMA): Free Stock Analysis Report
 
Aspen Group Inc. (ASPU): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/400554


Bet on Quality ETFs to Combat Omicron and Fed Worries

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Wall Street is again going through a tough phase. The Dow Jones Industrial Average and the S&P 500 indices declined 3.7% and 0.8%, respectively, in November. The Russell 2000 index lost 4.3% in the month, marking its worst since March 2020.

– Zacks

The mood on the bourses seemed tensed on the final trading day of the month on the rising concerns over omicron strain and the possibility of the Federal Reserve increasing the pace of their tapering process. The new variant is feared to be carrying the combined features of previous variants and can have high transmissibility and lower vaccine potency.

Investors willing to sail through the current market turbulences from the latest COVID-19-variant-related concerns can consider iShares MSCI USA Quality Factor ETF QUAL, Invesco S&P 500 Quality ETF SPHQ, FlexShares Quality Dividend Index Fund QDF, SPDR MSCI USA StrategicFactors ETF QUS and Barron’s 400 ETF BFOR.

Moderna MRNA CEO Stephane Bancel’s comment to the Financial Times on Nov 29, claiming that he anticipates the existing COVID-19 vaccines to prove comparatively less effective against the new strain, has brought about a new wave of concerns (according to a CNBC article).

The omicron variant has now been reported in the U.K., Israel, Belgium, the Netherlands, Germany, Italy, Australia and Hong Kong. Going on, the World Health Organization (WHO) has labeled the variant as a “variant of concern.” At least 70 countries and territories are believed to have put travel restrictions from several African countries to control the outbreak, per a CNN report.

Federal Reserve Chair Jerome Powell further dented the market sentiments by mentioning that the central bank will be discussing speeding up the tapering process from the $15 billion-a-month schedule decided previously, per a CNBC article. This move might be taken to control the persistently high inflation levels, given that the U.S. economy is strongly recovering from the pandemic-led slump.

Commenting on the current market scenario, Gregory Daco, chief U.S. economist at Oxford Economics, has said that “Markets appear to be having trouble digesting the combo of elevated uncertainty around the impact of the Omicron variant and a hawkish Fed pivot in the context of persistently elevated inflation.” This was stated in a CNBC article.

Quality ETFs Worth a Look

Quality stocks are rich in value characteristics with a healthy balance sheet, high return on capital, low volatility and healthy margins. These stocks also have a track record of stable or rising sales and earnings growth. In comparison to plain vanilla funds, these products help lower volatility and perform rather well during market uncertainty. Further, academic researches proved that high-quality companies constantly provide better risk-adjusted returns than the broader market over the long term.

Against such a backdrop, we highlighted five ETFs targeting this niche strategy. These could enjoy smooth trading and generate market-beating returns in the current market scenario.

iShares MSCI USA Quality Factor ETF

iShares MSCI USA Quality Factor ETF provides exposure to the large- and mid-cap stocks exhibiting positive fundamentals (high return on equity, stable year-over-year earnings growth and low financial leverage) by tracking the MSCI USA Sector Neutral Quality Index (read: 5 Winning ETF Ideas for the Fourth Quarter).

Expense Ratio: 0.15%

AUM: $27.85 billion

Invesco S&P 500 Quality ETF 

Invesco S&P 500 Quality ETF tracks the S&P 500 Quality Index, a benchmark of S&P 500 stocks, that has the highest-quality score based on three fundamental measures, namely, the return on equity, accruals ratio and the financial leverage ratio.

Expense Ratio: 0.15%

AUM: $3.29 billion

FlexShares Quality Dividend Index Fund 

FlexShares Quality Dividend Index Fund seeks investment results that generally correspond to the price and yield performance, before fees and expenses, of the Northern Trust Quality Dividend Index.

Expense Ratio: 0.37%

AUM: $1.77 billion

SPDR MSCI USA StrategicFactors ETF 

SPDR MSCI USA StrategicFactors ETF offers exposure to stocks that combine value, low volatility and quality-factor strategies. This is done by tracking the MSCI USA Factor Mix A-Series Capped Index.

Expense Ratio: 0.15%

AUM: $1.10 billion

Barron’s 400 ETF 

Barron’s 400 ETF seeks investment results that generally correspond, before fees and expenses, to the performance of the Barron’s 400 Index.

Total Operating Expenses: 0.70%

AUM: $159 million

Want key ETF info delivered straight to your inbox?

Zacks’ free Fund Newsletter will brief you on top news and analysis, as well as top-performing ETFs, each week.

Get it free >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Moderna, Inc. (MRNA): Free Stock Analysis Report
 
iShares MSCI USA Quality Factor ETF (QUAL): ETF Research Reports
 
FlexShares Quality Dividend ETF (QDF): ETF Research Reports
 
Invesco S&P 500 Quality ETF (SPHQ): ETF Research Reports
 
BARRONS400 ETF (BFOR): ETF Research Reports
 
SPDR MSCI USA StrategicFactors ETF (QUS): ETF Research Reports
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/400302


Amazon (AMZN) Gains Competitive Edge with Graviton3 Instances

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Amazon AMZN ramps up the competition in the cloud market with the introduction of Amazon Web Services’ (“AWS”) Graviton3 processor-backed Amazon Elastic Compute Cloud (Amazon EC2) C7g instances.
Cost-efficient C7g instances offer enhanced performance to customers for their compute-intensive workload.
Arm-based AWS Graviton3 processors deliver up to three times better performance for machine learning workloads compared with the company’s last-generation chips — AWS Graviton2 processors.
Graviton3 offers up to two times higher floating-point performance for scientific, machine learning, and media encoding workloads. It further provides up to two times faster performance for cryptographic workloads.
The new processors deliver 25% better performance in comparison with Graviton2 processors.

– Zacks

Competitive Edge Over Arm

Although Amazon, currently carrying a Zacks Rank #5 (Strong Sell), faces stiff competition from its strong peers, namely Microsoft MSFT, Alphabet’s GOOGL Google and Oracle ORCL in the cloud domain, AMZN’s strengthening efforts toward bolstering its in-house Arm-based chip portfolio remain noteworthy.
The launch of AWS Graviton2 processors is a testament to the same.
Notably, Arm architecture has gained momentum with the rise in the demand for cheaper but efficient cloud solutions worldwide in order to lower costs.
Cost-effectiveness hugely depends on the energy consumption by the cloud servers. Notably, the lesser the energy consumption, the lower will be the cost. Arm processors, widely used in smartphones and tablets, are commonly known for their low energy consumption. Consequently, the utilization of the processors makes cloud systems more efficient.
Therefore, the Arm-based Graviton processors, which do not require an x86 instruction set that is expensive for the scale-out workloads, make AWS a more viable option in lowering costs.
AWS offers a wide range of cost-effective and power-efficient compute instances. Apart from Graviton3-powered Amazon EC2 C7g instances, AWS’s Graviton2 instance portfolio offers 12 different instances such as accelerated computing instances, storage optimized, compute optimized and memory optimized.

Efforts by Microsoft, Alphabet & Oracle

Oracle recently introduced its first Arm compute instances called OCI Ampere A1, which leveled up its game with Amazon. Notably, OCI Ampere A1 costs one cent per core hour.
Oracle, which currently carries a Zacks Rank #3 (Hold), intends to accelerate app development and improvise application performance on its cloud infrastructure on the back of OCI Ampere A1.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Meanwhile, Microsoft and Google are yet to incorporate Arm-based chips in their cloud platforms.
Reportedly, Microsoft has forayed into designing in-house Arm-based chips for Azure servers and Surface PCs. The Zacks Rank #3 company intends to produce a processor for use in its data centers by leveraging Arm designs.
Alphabet’s Google has hired Intel engineering veteran Uri Frank in an effort to design server chips. This is in sync with the Zacks Rank #1 company’s increasing investment in customizing its chips in order to reduce energy use and increase performance across its cloud business.

Zacks Names “Single Best Pick to Double”

From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.

You know this company from its past glory days, but few would expect that it’s poised for a monster turnaround. Fresh from a successful repositioning and flush with A-list celeb endorsements, it could rival or surpass other recent Zacks’ Stocks Set to Double like Boston Beer Company which shot up +143.0% in a little more than 9 months and Nvidia which boomed +175.9% in one year.

Free: See Our Top Stock and 4 Runners Up >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Amazon.com, Inc. (AMZN): Free Stock Analysis Report
 
Microsoft Corporation (MSFT): Free Stock Analysis Report
 
Oracle Corporation (ORCL): Free Stock Analysis Report
 
Alphabet Inc. (GOOGL): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/400303


Growth Stock Meltdown: ROKU and PYPL vs. NVDA and TTD

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
[embedded content]

Holy overvalued price-to-sales ratio Batman! These stocks are going down!
In today’s Cook’s Kitchen, I take a look at the bloodbath in our favorite growth machines, from Roku ROKU to PayPal PYPL.
I also explain why I’m confident about where I can buy PayPal, but not so sure about Roku.
Just as important, I explain how to buy any of your favorite ideas as they are coming down.
For instance, I want to be a buyer of PYPL above $170. And I’m so confident, that I’m willing to put a limit buy order in my account to capture the next flush.
Why is this so important? Because during crushing sell-offs in growth stocks, the algos will push hard to trigger all the stop-loss orders.
And this means that when you get that last spike down, it will come quick and reverse before you can say “I knew I shoulda had a buy order in there!”
Where’s the Strength in This Market?
Then there’s NVIDIA NVDA and The Trade Desk TTD. In the video, I show a table of relative strength for about 30 top growth stocks as of last week. It comes courtesy of Chris Perruna’s Twitter feed, @cperruna, where he ran a 3-month relative strength screen using MarketSmith.
In the top of the heap were two of my favorites, NVIDIA and The Trade Desk. I’m still holding NVDA with a cost basis near $100 with no fear of giving back some profits.
And in TTD — who I call the “CME of Advertising” — we just took 120% profits last month. So I’m looking to buy inside $90-95.
Finally, Shopify SHOP was holding up pretty well too at the end of last week with a relative strength rating of 88, right there with Apple busting new highs.
But this week it’s down another 7% from all-time highs above $1700. I’m getting ready to buy some Shopify if shares slip under $1425.
One more thing: In the video, I also talk about what I think the extent of this corrective action will be for the S&P 500 and where this whole sell-off turns around again to close the year on a high note.
Actually, two more: I mentioned my discussion with Tracey Ryniec on her MarketEdge podcast Tuesday. Here’s that link…
Growth Stock Sell-Off: What Should You Do?
Tracey and I discuss PINS, PTON, LULU, RH, EXAS and more in that 30 minute episode.
Disclosure: I own shares of NVDA and PINS and may be buying PYPL and TTD soon.

– Zacks

Zacks Names “Single Best Pick to Double”

From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.

You know this company from its past glory days, but few would expect that it’s poised for a monster turnaround. Fresh from a successful repositioning and flush with A-list celeb endorsements, it could rival or surpass other recent Zacks’ Stocks Set to Double like Boston Beer Company which shot up +143.0% in a little more than 9 months and Nvidia which boomed +175.9% in one year.

Free: See Our Top Stock and 4 Runners Up >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
NVIDIA Corporation (NVDA): Free Stock Analysis Report
 
PayPal Holdings, Inc. (PYPL): Free Stock Analysis Report
 
Shopify Inc. (SHOP): Free Stock Analysis Report
 
The Trade Desk (TTD): Free Stock Analysis Report
 
Roku, Inc. (ROKU): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/400293


Southern Copper (SCCO) Stock Moves -1.78%: What You Should Know

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Southern Copper (SCCO) closed at $58.50 in the latest trading session, marking a -1.78% move from the prior day. This change was narrower than the S&P 500’s 1.9% loss on the day. Meanwhile, the Dow lost 1.86%, and the Nasdaq, a tech-heavy index, added 0.21%.

– Zacks

Coming into today, shares of the miner had lost 1.57% in the past month. In that same time, the Basic Materials sector gained 0.06%, while the S&P 500 gained 1.2%.

Southern Copper will be looking to display strength as it nears its next earnings release. On that day, Southern Copper is projected to report earnings of $1.10 per share, which would represent year-over-year growth of 44.74%. Meanwhile, the Zacks Consensus Estimate for revenue is projecting net sales of $2.59 billion, up 9.99% from the year-ago period.

Looking at the full year, our Zacks Consensus Estimates suggest analysts are expecting earnings of $4.40 per share and revenue of $10.79 billion. These totals would mark changes of +116.75% and +35.12%, respectively, from last year.

Any recent changes to analyst estimates for Southern Copper should also be noted by investors. These revisions help to show the ever-changing nature of near-term business trends. As such, positive estimate revisions reflect analyst optimism about the company’s business and profitability.

Our research shows that these estimate changes are directly correlated with near-term stock prices. We developed the Zacks Rank to capitalize on this phenomenon. Our system takes these estimate changes into account and delivers a clear, actionable rating model.

The Zacks Rank system ranges from #1 (Strong Buy) to #5 (Strong Sell). It has a remarkable, outside-audited track record of success, with #1 stocks delivering an average annual return of +25% since 1988. The Zacks Consensus EPS estimate has moved 0.15% lower within the past month. Southern Copper is currently a Zacks Rank #3 (Hold).

Investors should also note Southern Copper’s current valuation metrics, including its Forward P/E ratio of 13.53. This valuation marks a premium compared to its industry’s average Forward P/E of 12.93.

Also, we should mention that SCCO has a PEG ratio of 0.84. The PEG ratio is similar to the widely-used P/E ratio, but this metric also takes the company’s expected earnings growth rate into account. The Mining – Non Ferrous was holding an average PEG ratio of 0.64 at yesterday’s closing price.

The Mining – Non Ferrous industry is part of the Basic Materials sector. This group has a Zacks Industry Rank of 111, putting it in the top 44% of all 250+ industries.

The Zacks Industry Rank gauges the strength of our industry groups by measuring the average Zacks Rank of the individual stocks within the groups. Our research shows that the top 50% rated industries outperform the bottom half by a factor of 2 to 1.

To follow SCCO in the coming trading sessions, be sure to utilize Zacks.com.

Infrastructure Stock Boom to Sweep America

A massive push to rebuild the crumbling U.S. infrastructure will soon be underway. It’s bipartisan, urgent, and inevitable. Trillions will be spent. Fortunes will be made.

The only question is “Will you get into the right stocks early when their growth potential is greatest?”

Zacks has released a Special Report to help you do just that, and today it’s free. Discover 7 special companies that look to gain the most from construction and repair to roads, bridges, and buildings, plus cargo hauling and energy transformation on an almost unimaginable scale.

Download FREE: How to Profit from Trillions on Spending for Infrastructure >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Southern Copper Corporation (SCCO): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/400032


Albertsons Companies, Inc. (ACI) Stock Moves -0.68%: What You Should Know

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

In the latest trading session, Albertsons Companies, Inc. (ACI) closed at $35.19, marking a -0.68% move from the previous day. This change was narrower than the S&P 500’s daily loss of 1.9%. Elsewhere, the Dow lost 1.86%, while the tech-heavy Nasdaq added 0.21%.

– Zacks

Coming into today, shares of the company had gained 11.35% in the past month. In that same time, the Consumer Staples sector lost 0.38%, while the S&P 500 gained 1.2%.

Investors will be hoping for strength from Albertsons Companies, Inc. as it approaches its next earnings release. In that report, analysts expect Albertsons Companies, Inc. to post earnings of $0.55 per share. This would mark a year-over-year decline of 16.67%. Meanwhile, the Zacks Consensus Estimate for revenue is projecting net sales of $15.96 billion, up 3.58% from the year-ago period.

Looking at the full year, our Zacks Consensus Estimates suggest analysts are expecting earnings of $2.59 per share and revenue of $69.78 billion. These totals would mark changes of -20.06% and +0.12%, respectively, from last year.

Investors should also note any recent changes to analyst estimates for Albertsons Companies, Inc.These revisions help to show the ever-changing nature of near-term business trends. As such, positive estimate revisions reflect analyst optimism about the company’s business and profitability.

Based on our research, we believe these estimate revisions are directly related to near-team stock moves. We developed the Zacks Rank to capitalize on this phenomenon. Our system takes these estimate changes into account and delivers a clear, actionable rating model.

Ranging from #1 (Strong Buy) to #5 (Strong Sell), the Zacks Rank system has a proven, outside-audited track record of outperformance, with #1 stocks returning an average of +25% annually since 1988. Within the past 30 days, our consensus EPS projection remained stagnant. Albertsons Companies, Inc. is currently a Zacks Rank #1 (Strong Buy).

In terms of valuation, Albertsons Companies, Inc. is currently trading at a Forward P/E ratio of 13.66. For comparison, its industry has an average Forward P/E of 21.57, which means Albertsons Companies, Inc. is trading at a discount to the group.

Investors should also note that ACI has a PEG ratio of 1.14 right now. This metric is used similarly to the famous P/E ratio, but the PEG ratio also takes into account the stock’s expected earnings growth rate. The Consumer Products – Staples was holding an average PEG ratio of 3.94 at yesterday’s closing price.

The Consumer Products – Staples industry is part of the Consumer Staples sector. This industry currently has a Zacks Industry Rank of 215, which puts it in the bottom 16% of all 250+ industries.

The Zacks Industry Rank gauges the strength of our individual industry groups by measuring the average Zacks Rank of the individual stocks within the groups. Our research shows that the top 50% rated industries outperform the bottom half by a factor of 2 to 1.

Be sure to follow all of these stock-moving metrics, and many more, on Zacks.com.

Infrastructure Stock Boom to Sweep America

A massive push to rebuild the crumbling U.S. infrastructure will soon be underway. It’s bipartisan, urgent, and inevitable. Trillions will be spent. Fortunes will be made.

The only question is “Will you get into the right stocks early when their growth potential is greatest?”

Zacks has released a Special Report to help you do just that, and today it’s free. Discover 7 special companies that look to gain the most from construction and repair to roads, bridges, and buildings, plus cargo hauling and energy transformation on an almost unimaginable scale.

Download FREE: How to Profit from Trillions on Spending for Infrastructure >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Albertsons Companies, Inc. (ACI): Free Stock Analysis Report
 
To read this article on Zacks.com click here.

https://www.entrepreneur.com/article/400031


Cabot (CBT) to Divest Purification Solutions Unit for $111M

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Cabot Corporation CBT recently entered into an agreement to sell its Purification Solutions business to One Equity Partners, a middle-market private equity firm. The transaction, valued at $111 million and expected to close in the second quarter of fiscal 2022, is subject to customary closing conditions and applicable works council consultations.
Cabot’s Purification Solutions business is a renowned player in the research, development, manufacturing, and sale of high-performing activated carbon used in a range of environmental, health, safety, and industrial applications.
The company expects to recognize a pre-tax impairment charge in the range of $155-$165 million in the first quarter of fiscal 2022 in relation to the sale, with net cash proceeds from the transaction expected to be roughly $80 million.
While Credit Suisse is acting as the financial advisor, K&L Gates is giving legal counsel to Cabot for the transaction.
Cabot is enthusiastic about the deal as One Equity Partners has a proven track record of advancing market-leading industrial companies. The transaction will allow the company to channel its resources on its core business segments and invest in units with strong future growth and innovation potential, such as Battery Materials.
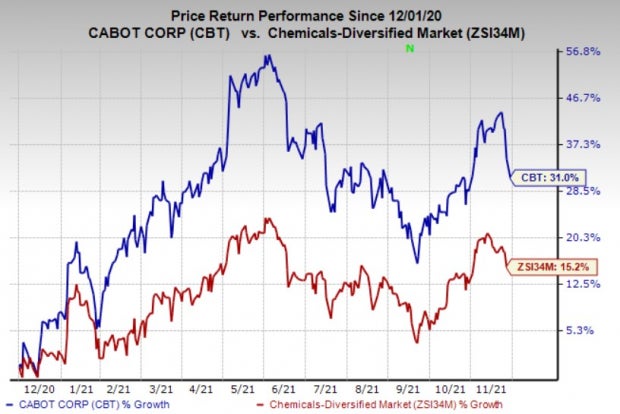
Cabot’s shares have risen 31% over the past year, outperforming the 15.2% rise of the industry.

– Zacks

Zacks Investment ResearchImage Source: Zacks Investment Research

In the fourth quarter of fiscal 2021, Cabot reported adjusted earnings of $1.11 per share, topping the Zacks Consensus Estimate of $1.02. Revenues were $904 million in the quarter, which jumped 37.2% year over year but missed the Zacks Consensus Estimate of $924.5 million.
In its fourth-quarter earnings call, Cabot stated that it expects continued strong end-market demand and benefits from growth investments. It expects to benefit from higher volumes driven by strong forecasted levels of tire production and higher pricing in the Reinforcement Materials segment. In the Performance Chemicals segment, Cabot projects continued demand growth across its broad set of applications, with particular strength in battery materials and inkjet packaging.
The company also expects challenges such as rising input costs, global supply-chain disruptions and the semiconductor chip shortage to moderate through the next fiscal year. The company expects adjusted earnings per share for fiscal 2022 in the range of $5.20-$5.60.

Zacks Rank & Key Picks

Cabot currently carries a Zacks Rank #3 (Hold).
Better-ranked stocks from the basic materials space include Univar Solutions Inc. UNVR and AdvanSix Inc. ASIX sporting a Zacks Rank #1 (Strong Buy), and Celanese Corp. CE carrying a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Univar has an expected earnings growth rate of 55.2% for the current year. The Zacks Consensus Estimate for its current-year earnings has been revised 9% upward over the past 60 days.
Univar beat the Zacks Consensus Estimate for earnings in the four trailing quarters, with an earnings surprise of 24.1%, on average. UNVR’s shares have rallied 50.5% over a year.
AdvanSix has an expected earnings growth rate of 197% for the current year. The Zacks Consensus Estimate for its current-year earnings has been revised 14.1% upward over the last 60 days.
AdvanSix beat the Zacks Consensus Estimate for earnings in the four trailing quarters, with an earnings surprise of 47%, on average. ASIX’s shares have also surged 157.4% over a year.
Celanese has an expected earnings growth rate of 139.7% for the current year. The Zacks Consensus Estimate for its current-year earnings has been revised 9.1% upward over the last 60 days.
Celanese beat the Zacks Consensus Estimate for earnings in the four trailing quarters and pulled off an earnings surprise of 12.7%, on average. Shares of CE have rallied around 22.6% over a year.

Tech IPOs With Massive Profit Potential: Last years top IPOs surged as much as 299% within the first two months. With record amounts of cash flooding into IPOs and a record-setting stock market, this year could be even more lucrative. 

See Zacks’ Hottest Tech IPOs Now >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Celanese Corporation (CE): Free Stock Analysis Report
 
Cabot Corporation (CBT): Free Stock Analysis Report
 
Univar Solutions Inc. (UNVR): Free Stock Analysis Report
 
AdvanSix (ASIX): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/400025


Should You Buy the Post Earnings Dip in Gap?

Omnichannel apparel retailer Gap (GPS) reported a substantial decline in its revenues and profit margins in the last quarter due to inventory shortfalls because of the global supply chain disruptions. As the travel restrictions are reimposed amid concerns surrounding the omicron coronavirus variant, will GPS be able to overcome its production and delivery-related challenges soon? Read more to find out.

shutterstock.com – StockNews

Renowned specialty retail apparel company The Gap, Inc. (GPS) announced its fiscal third-quarter earnings (ended October 30, 2021) on November 23, 2021. GPS’ net sales fell 1.3% year-over-year to $3.94 billion, despite a 48% increase in online sales from the 2019 levels. Operating income fell 12.6% from the same period last year to $153 million. The company’s net loss came in at $152 million, reflecting a substantial decline from the year-ago net profit of $95 million. Loss per share came in at $0.40, missing the analyst estimates by 46%. Following the third-quarter earnings release, the stock declined 26.3% to close Friday’s trading session at $17.33.

GPS has cited supply chain constraints due to factory closures and port congestions as the main reason behind its poor performance in the last quarter. The significant delays in deliveries affected the company’s inventory margins as well as sales, as it was not able to meet the strong market demand.

GPS’ management stated that it has been working to increase air freight and port diversification to meet the demand this holiday season. However, with the rising concerns surrounding the omicron coronavirus variant leading to the reimposition of travel restrictions worldwide, GPS’ inventory shortfall will likely continue throughout the fiscal fourth quarter (ending January 2022).

Here’s what could shape GPS’ performance in the near term:

Legal Investigation

Nationally ranked shareholder rights firm Labaton Sucharow announced on November 27 that it is investigating whether GPS violated certain securities laws and fiduciary duties. Law firm Bronstein Gewirtz & Grossman, LLC is also currently investigating whether the company’s officers and/or directors have engaged in corporate wrongdoing on behalf of shareholders who invested in GPS before August 1, 2020.

Mixed Valuation Metrics

In terms of forward P/E, GPS is currently trading at 19.62x, 20.4% higher than the industry average of 16.3x. However, the stock’s forward Price/Sales and EV/EBITDA ratios of 0.38 and 8.65 are 68.5% and 15.8% lower than the industry averages of 1.23 and 10.27, respectively.

In addition, GPS is currently trading 5.44 times its forward cash flow, which is 57.4% lower than the industry average of 12.76.

Poor Growth Prospects

The consensus revenue estimate of $4.54 billion for the current quarter (ending January 2022), indicating a slight improvement year-over-year. However, analysts expect GPS’ EPS to remain negative in the ongoing quarter, indicating a 121.4% decline year-over-year. Also, the company’s EPS is expected to fall 22.9% in the next quarter (ending April 2022).

Consensus Rating and Price Target Indicate Potential Upside

Of the 15 Wall Street analysts that rated GPS, three rated it Buy, while 12 rated it Hold. The median price target of $24.43 indicates a 40.3% potential upside. The price targets range from a low of $20.00 to a high of $29.00.

POWR Ratings Reflect Uncertainty

GPS has an overall rating of C, which equates to Neutral in our proprietary POWR Ratings system. The POWR Ratings are calculated considering 118 different factors, with each factor weighted to an optimal degree.

GPS has a Quality grade of B, and a Stability grade of D. Its 49.23% trailing-12-month gross profit margin is 37.5% higher than the industry average of 35.82%, in sync with the Quality grade. However, the stock’s 1.67 beta justifies its poor Stability grade.

Of the 63 stocks in the Fashion & Luxury industry, GPS is ranked #48.

In addition to the grades I’ve highlighted, view GPS ratings for Momentum, Value, Sentiment, and Growth here.

Bottom Line

GPS is one of the most famous apparel retailers in the United States, known for its Old Navy, Gap, Athleta, and Banana Republic brands. While the company witnessed stable demand over the last quarter as consumer spending increased substantially, its operations were adversely impacted by the ongoing supply chain constraints. Given the current speculations surrounding the omicron coronavirus variant, the supply chain crisis is expected to continue over the next few months. Thus, investors should wait until GPS comes up with concrete plans to deal with such constraints before investing in the stock.

How Does The Gap, Inc. (GPS) Stack Up Against its Peers?

While GPS has a C rating in our proprietary rating system, you might want to consider taking a look at its industry peers, Hugo Boss AG (BOSSY), Shoe Carnival, Inc. (SCVL), and Genesco Inc. (GCO), which have an A (Strong Buy) rating.


GPS shares . Year-to-date, GPS has declined -10.35%, versus a 25.48% rise in the benchmark S&P 500 index during the same period.


About the Author: Aditi Ganguly

Aditi is an experienced content developer and financial writer who is passionate about helping investors understand the do’s and don’ts of investing. She has a keen interest in the stock market and has a fundamental approach when analyzing equities.

More…

The post Should You Buy the Post Earnings Dip in Gap? appeared first on StockNews.com

https://www.entrepreneur.com/article/399728


Navigator Holdings (NVGS) Surpasses Q3 Earnings and Revenue Estimates

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Navigator Holdings (NVGS) came out with quarterly earnings of $0.10 per share, beating the Zacks Consensus Estimate of $0.06 per share. This compares to earnings of $0.03 per share a year ago. These figures are adjusted for non-recurring items.

– Zacks

This quarterly report represents an earnings surprise of 66.67%. A quarter ago, it was expected that this transportaion company for the natural gas and and chemical industry would post earnings of $0.13 per share when it actually produced earnings of $0.01, delivering a surprise of -92.31%.

Over the last four quarters, the company has surpassed consensus EPS estimates just once.

Navigator Holdings, which belongs to the Zacks Transportation – Shipping industry, posted revenues of $85.97 million for the quarter ended September 2021, surpassing the Zacks Consensus Estimate by 4.33%. This compares to year-ago revenues of $66.77 million. The company has topped consensus revenue estimates three times over the last four quarters.

The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.

Navigator Holdings shares have lost about 26.7% since the beginning of the year versus the S&P 500’s gain of 22.3%.

What’s Next for Navigator Holdings?

While Navigator Holdings has underperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?

There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.

Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.

Ahead of this earnings release, the estimate revisions trend for Navigator Holdings was unfavorable. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #5 (Strong Sell) for the stock. So, the shares are expected to underperform the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $0.24 on $100.14 million in revenues for the coming quarter and $0.38 on $309.06 million in revenues for the current fiscal year.

Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Transportation – Shipping is currently in the top 24% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.

Investor Alert: Legal Marijuana Looking for big gains?

Now is the time to get in on a young industry primed to skyrocket from $13.5 billion in 2021 to an expected $70.6 billion by 2028.

After a clean sweep of 6 election referendums in 5 states, pot is now legal in 36 states plus D.C. Federal legalization is expected soon and that could kick start an even greater bonanza for investors. Zacks Investment Research has recently closed pot stocks that have shot up as high as +147.0%

You’re invited to immediately check out Zacks’ Marijuana Moneymakers: An Investor’s Guide. It features a timely Watch List of pot stocks and ETFs with exceptional growth potential.

Today, Download Marijuana Moneymakers FREE >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Navigator Holdings Ltd. (NVGS): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/399722