ViacomCBS (VIAC) Buys Majority Stake in Disney Properties

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

ViacomCBS VIAC recently announced that ViacomCBS Networks International (“VCNI”) completed the acquisition of a majority stake in Fox TeleColombia and Estudios TeleMexico from The Walt Disney Company DIS. The terms of the transactions have not been disclosed.
The acquisition is anticipated to enhance ViacomCBS’ capabilities to produce Spanish-language content. It will also help ViacomCBS International Studios (“VIS”) to capitalize on significant content demand on its global streaming platforms such as Pluto Tv and Paramount+.
VIS will operate Fox TeleColombia and Estudios TeleMexico as a collaborative partnership with the latter’s founding family.
The acquisition provides VCNI with complete access to the studio operations of FoxColombia and Estudios TeleMexico’s in Mexico and Colombia, which is expected to bolster the production capabilities of ViacomCBS.
It will also enable ViacomCBS to access FoxColombia’s and Estudios TeleMexico’s robust content portfolio, with various genres and including popular dramas, movies and documentaries. The content will boost ViacomCBS’s streaming platforms Pluto TV and Paramount+ along with its linear networks all around the globe.
The acquisition adds to VCNI’s growing portfolio in Latin America. In September 2021, VCNI acquired Chilevision from Warner Media. The financial terms of the deal were not disclosed. The acquisition was part of ViacomCBS’s plans to expand its reach and profitability in Latin America.
Apart from international expansions, the rapid adoption of Paramount+ bodes well for ViacomCBS.
In the streaming space, Paramount+ is facing stiff competition from players like Netflix NFLX, Disney’s Disney+ and Peacock from Comcast CMCSA division NBCUniversal.
ViacomCBS’ shares have underperformed Netflix and Comcast on a year-to-date basis. The stock has declined 10.8% year to date against Netflix’s rise of 21.7%. Comcast’s and Disney’s shares have declined 1% and 16.4% year to date, respectively.


– Zacks

Nevertheless, the growing popularity of Disney+ has been driving growth prospects of Disney. Disney+’s strong content portfolio bodes well for the company.
Comcast is benefiting from an increasing broadband subscriber base and a growing momentum in the wireless business. Additionally, its streaming service Peacock gained significant traction amid the coronavirus-led increased media consumption. Disney’s focus on Live Sports is anticipated to boost growth in the long run.
However, Netflix is still dominating the streaming market. In third-quarter 2021, Netflix added 4.38 million paid subscribers globally compared with 2.2 million in the year-ago quarter and beat its guidance of 3.5 million paid-subscriber addition. Latin America’s (LATAM) paid subscriber base rose 7.3% from the year-ago quarter’s levels to 38.9 million. The company added 0.3 million paid subscribers, up 28.9% year over year.
Paramount+ faces a tough challenge in the streaming space for market share. Nevertheless, a robust content portfolio and a strong pipeline of new releases are expected to boost Paramount+’s competitive prowess. ViacomCBS added 4.3 million subscribers in the third quarter, raising the number of global streaming subscribers to around 47 million.
ViacomCBS currently has a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

Bitcoin, Like the Internet Itself, Could Change Everything

Blockchain and cryptocurrency has sparked one of the most exciting discussion topics of a generation. Some call it the “Internet of Money” and predict it could change the way money works forever. If true, it could do to banks what Netflix did to Blockbuster and Amazon did to Sears. Experts agree we’re still in the early stages of this technology, and as it grows, it will create several investing opportunities.

Zacks’ has just revealed 3 companies that can help investors capitalize on the explosive profit potential of Bitcoin and the other cryptocurrencies with significantly less volatility than buying them directly. 

See 3 crypto-related stocks now >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Comcast Corporation (CMCSA): Free Stock Analysis Report
 
Netflix, Inc. (NFLX): Free Stock Analysis Report
 
The Walt Disney Company (DIS): Free Stock Analysis Report
 
ViacomCBS Inc. (VIAC): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/399411


Ligand’s (LGND) Drug-Developing Technologies Holds Potential

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

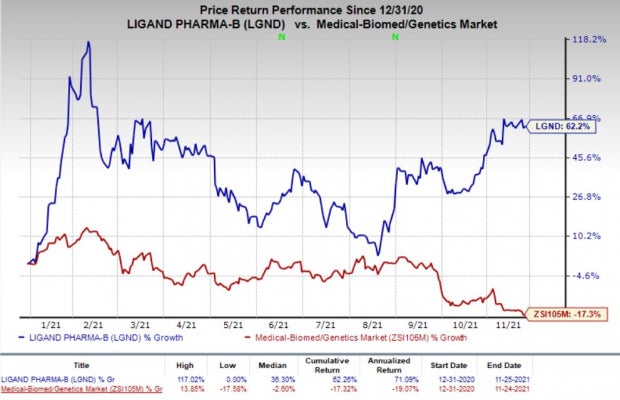
Ligand Pharmaceuticals’ LGND stock has gained 62.2% so far this year against 17.3% decrease of the industry.

– Zacks

Zacks Investment ResearchImage Source: Zacks Investment Research

Ligand’s top-line growth is primarily being driven by its Captisol technology. LGND has signed more than 160 Captisol research-use agreements and 13 clinical/commercial license agreements in 2020. These deals provide LGND with license fees and milestone-based payments.

Ligand also earns royalties on the sales of drugs developed using its Captisol technology, including Amgen’s AMGN blockbuster drug, Kyprolis. LGND’s another source of revenues is the sale of Captisol material to its partners.

Ligand’s Captisol technology should continue to be a key revenue driver with rising demand for its partnered drugs and potential approval to the new Captisol-based drugs. New deals will also help drive revenues.

Amgen’s Kyprolis is approved for treating multiple myeloma. It sales generated $824 million in the first nine months of 2021, reflecting year-over-year growth of almost 4%. Moreover, Gilead’s GILD Veklury has also boosted Ligand’s topline in 2021. Veklury is developed using the Captisol technology and Gilead gained a regulatory nod for the drug to treat severe COVID-19 patients.

Gilead recorded Veklury’s sales of $4.2 billion in the first nine-months of 2021. With the rising cases of COVID-19, especially in the European countries, the drug’s demand will likely continue to increase in the upcoming quarters.

Apart from Captisol, Ligand has another promising technology called OmniAb in its portfolio. It is newer than the Captisol technology and has longer patent protection as well. The first OmniAb-derived antibody to receive approval in any country is Gloria Biosciences’ zimberelimab. China approved the drug for treating Hodgkin’s lymphoma in August. Another OmniAb-derived partnered drug, sugemalimab, will likely get a nod in China by 2021-end. Currently, 19 different OmniAb-derived antibodies are under development through different partners.

A few potential approvals for the partnered OmniAb-derived drugs are expected in the upcoming quarters. Management believes that the platform can generate $500 million to $1 billion of annual royalties beginning 2030.

Ligand is planning to spin-off its OmniAb business into a separate public company to intensify its individual focus on Captisol and OmniAb technologies. However, the decision is yet to be finalized.

Ligand has several other technology platforms in its portfolio which have been added through different acquisitions over the past few years. Some of these technologies complemented Captisol and OmniAb platforms while others provided new avenues of growth.

Although Ligand’s technology platforms are encouraging, it is highly dependent on partners for growth. If any of LGND”s partners fails to receive regulatory approvals or terminates a deal, its prospects would be severely hit.

Moreover, Ligand’s royalty revenues are primarily driven by Kyprolis, following the sale of rights to Novartis’ NVS Promacta, which was also developed using the Captisol technology. Any generic approval for Kyprolis will hurt Ligand’s topline substantially.

We note that Promacta is marketed by Novartis worldwide and is available under the trade name of Revolade outside the United States. The sale of its rights to this Novartis’ drug in 2019 helped Ligand earn $827 million of cash.

Zacks Rank

Ligand currently carries a Zacks Rank #3 (Hold).

You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

Bitcoin, Like the Internet Itself, Could Change Everything

Blockchain and cryptocurrency has sparked one of the most exciting discussion topics of a generation. Some call it the “Internet of Money” and predict it could change the way money works forever. If true, it could do to banks what Netflix did to Blockbuster and Amazon did to Sears. Experts agree we’re still in the early stages of this technology, and as it grows, it will create several investing opportunities.

Zacks’ has just revealed 3 companies that can help investors capitalize on the explosive profit potential of Bitcoin and the other cryptocurrencies with significantly less volatility than buying them directly. 

See 3 crypto-related stocks now >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Novartis AG (NVS): Free Stock Analysis Report
 
Amgen Inc. (AMGN): Free Stock Analysis Report
 
Gilead Sciences, Inc. (GILD): Free Stock Analysis Report
 
Ligand Pharmaceuticals Incorporated (LGND): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/399412


Delek (DK) Stock Declines 6.1% Despite Beating on Q3 Earnings

Shares of Delek US Holdings, Inc.’s DK have dropped 6.1% since the third-quarter 2021 earnings announcement on Nov 4.

– Zacks

This downward stock movement could possibly be triggered by a huge debt burden in the third quarter, increase in operating expenses and a lack of contribution from DK’s retail segment.  

Behind the Earnings Headlines

Delek’s third-quarter 2021 results recently reported adjusted earnings of 13 cents a share. The Zacks Consensus Estimate was of a loss of 34 cents. The bottom line reversed the year-ago quarter’s loss of $1.01, attributable to a stronger-than-expected contribution from its refining segment. Margin from the Refining unit was $91.4 million, outpacing the Zacks Consensus Estimate of $66 million.

Quarterly revenues of $2.96 billion compared favorably with the year-ago sales of $2.06 billion and surpassed the Zacks Consensus Estimate of $2.55 billion.

Segmental Performances

Refining:  DK reported a positive margin of $91.4 million for this segment against the negative $17.8 million in the year-ago quarter. Moreover, adjusted margins of $91.8 million rebounded from -$21.2 million in the year-ago period. Results improved from increased crack spreads as the rising frequency of vaccination and a worldwide economic recovery buoyed demand.

Logistics:  This unit represents Delek’s majority interest in Delek Logistics Partners, L.P. (DKL), a publicly-traded master limited partnership that owns, operates, develops and acquires pipelines and other midstream assets. The Logistics unit’s margin of $67.2 million was in line with the year-ago period’s figure, led by higher refinery utilization and demand that was partially offset by operating expenditures associated with pipeline integrity work.

Retail: Margin for the unit, which was formed from the acquisition of Alon USA Energy in 2017, fell 2.2% to $17.9 million from the year-earlier quarter’s level of $18.3 million on lower Retail fuel sales. Delek’s merchandise sales of $81.7 million with a margin of 33.7%, on average, compared unfavorably with $86.8 million sales, carrying a margin of 31.6%, on average, in the prior year. Its retail fuel gallons sale totaled $41.9 million in the September quarter of 2021, the average margin being 33 cents per gallon. This compared unfavorably with $45.1 million sale, the average margin being 31 cents per gallon in third-quarter 2020.

Financials

Total operating expenses incurred in the quarter increased 36.1% from the prior-year period’s level to $2,910.7 million.

In the reported quarter, Delek spent $28.9 million on capital programs (50.2% on the Refining segment). As of Sep 30, 2021, DK had cash and cash equivalents worth $830.6 million and long-term debt of $2,158.8 million, with the total debt to total capital of 68.8%.

Guidance

Delek projects fourth-quarter 2021 total operating expenses in the 150-$160 million band while total crude throughput is estimated in the 280,000-290,000 barrels per day range.

DK anticipates its 2021 capital expenses at around $205-$210 million, on a gross basis.

Zacks Rank & Key Picks

Delek currently has a Zacks Rank #3 (Hold). Some better-ranked players in the energy  space are EOG Resources EOG, Diamondback Energy FANG and ConocoPhillips COP, each presently flaunting a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.

EOG Resources reported third-quarter 2021 adjusted earnings per share of $2.16, beating the Zacks Consensus Estimate of $2.01. Strong earnings were driven by increased production volumes and a higher realization of commodity prices.

EOG announced a quarterly dividend of 75 cents per share, indicating an 82% increase from the previous level. The dividend will be paid out on Jan 28, 2022, to its shareholders of record as of Jan 14, 2022. EOG Resources also declared a special dividend of $2 per share. Moreover, the board of directors updated its share repurchase authorization to $5 billion.

Diamondback Energy reported third-quarter 2021 adjusted earnings of $2.94 per share, which surpassed the Zacks Consensus Estimate of $2.81 and the year-ago quarter’s earnings of 62 cents. FANG’s bottom line was aided by better-than-expected production.

The board of directors declared a dividend of 50 cents per share for the third quarter, accounting for an 11.1% hike in Diamondback Energy’s quarterly payout from the previous level of 45 cents. The amount will be paid out on Nov 18, 2021, to its shareholders of record as of Nov 11. FANG also generated a free cash flow of $740 million in the third quarter.

ConocoPhillips reported third-quarter 2021 adjusted earnings per share of $1.77, comfortably beating the Zacks Consensus Estimate of $1.53. This outperformance is led by increased production volumes owing to the Concho acquisition and the rising realized commodity prices.

Based in Houston, TX, this one of the world’s largest independent oil and gas producers’ capital expenditures and investments totaled $1.3 billion, and dividend payments grossed $579 million. ConocoPhillips’ net cash provided by operating activities was recorded at $4.8 billion, up from the year-ago figure of $868 million. COP generated a free cash flow of $2.8 billion in the third quarter.

Bitcoin, Like the Internet Itself, Could Change Everything

Blockchain and cryptocurrency has sparked one of the most exciting discussion topics of a generation. Some call it the “Internet of Money” and predict it could change the way money works forever. If true, it could do to banks what Netflix did to Blockbuster and Amazon did to Sears. Experts agree we’re still in the early stages of this technology, and as it grows, it will create several investing opportunities.

Zacks’ has just revealed 3 companies that can help investors capitalize on the explosive profit potential of Bitcoin and the other cryptocurrencies with significantly less volatility than buying them directly. 

See 3 crypto-related stocks now >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
ConocoPhillips (COP): Free Stock Analysis Report
 
EOG Resources, Inc. (EOG): Free Stock Analysis Report
 
Delek US Holdings, Inc. (DK): Free Stock Analysis Report
 
Diamondback Energy, Inc. (FANG): Free Stock Analysis Report
 
To read this article on Zacks.com click here.

https://www.entrepreneur.com/article/399413


G-III Apparel (GIII) Queued Up for Q3 Earnings: What to Expect

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

G-III Apparel Group, Ltd. GIII is likely to report top and bottom-line growth when it releases third-quarter fiscal 2022 results on Dec 1, before market open. The Zacks Consensus Estimate for earnings in the fiscal third quarter currently stands at $1.79, which shows growth of about 37% from the year-ago period’s reported figure. The consensus estimate has increased 2.3% in the past 30 days.
A glimpse of G-III Apparel’s performance in the trailing four quarters shows that it has an earnings surprise of 180.5%, on average.
The consensus mark for quarterly revenues is pegged at $1,012 million, indicating an increase of 22.4% from the year-ago quarter’s tally.

– Zacks

Key Factors to Note

G-III Apparel’s quarterly performance is most likely to have been driven by gains from digital business and brand strength. We note that digital sales of GIII’s products have been surging for a while now.
Management is focused on driving growth across the digital landscape via investments in internal talent, e-commerce sites and improved logistics capabilities.
Management is quite optimistic about G-III Apparel’s five global power brands, including DKNY, Donna Karan, Calvin Klein, Tommy Hilfiger and Karl Lagerfeld Paris. GIII is also benefiting from assortments and products resonating well with consumer demand. It is witnessing continued strength in casual categories. GIII’s strategic licensing agreements and international business remain added positives.
All the aforesaid tailwinds are expected to have boosted G-III Apparel’s performance in the to-be-reported quarter. On its last earnings call on Sep 2, management had projected net sales of roughly $1 billion for third-quarter fiscal 2022. It had envisioned earnings per share of $1.65-$1.75.

What the Zacks Model Unveils

Our proven model predicts an earnings beat for G-III Apparel this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.

G-III Apparel has a Zacks Rank #3 and an Earnings ESP of +8.14%, currently.

More Stocks with Favorable Combination

Here are a few more companies you may want to consider as our model shows that these too have the right combination of elements to beat on earnings this season:
lululemon athletica LULU currently has an Earnings ESP of +1.44% and a Zacks Rank of 2. LULU is expected to register top and bottom-line growth when it reports third-quarter fiscal 2021 numbers. The Zacks Consensus Estimate for quarterly revenues is pegged at $1.43 billion, which suggests growth of 28.1% from the prior-year quarter’s reported figure.
The Zacks Consensus Estimate for lululemon’s quarterly earnings has moved a penny up in the past 30 days to $1.39 per share, suggesting a 19.8% increase from the year-ago quarter’s reported number. LULU delivered an earnings beat of 25.2%, on average, in the trailing four quarters. You can see the complete list of today’s Zacks #1 Rank stocks here.
PVH Corp. PVH currently has an Earnings ESP of +1.61% and a Zacks Rank #2. PVH is expected to register top- and bottom-line growth when it reports third-quarter fiscal 2021 results. The Zacks Consensus Estimate for quarterly earnings of $2.07 per share suggests growth of 56.8% from the year-ago quarter’s reported figure.
The consensus mark for PVH Corp.’s quarterly revenues is pegged at $2.40 billion, indicating an increase of 13.4% from the figure reported in the year-ago quarter. PVH has a trailing four-quarter earnings surprise of 177.5%, on average.
Costco COST currently has an Earnings ESP of +1.00% and a Zacks Rank of 3. It is likely to register top and bottom-line growth when it reports first-quarter fiscal 2022 numbers. The Zacks Consensus Estimate for quarterly earnings has moved 2.8% north in the past 30 days to $2.59 per share, suggesting an improvement of 13.1% from the year-ago quarter’s tally.
The Zacks Consensus Estimate for Costco’s quarterly revenues is pegged at $49.6 billion, implying growth of 14.8% from the figure reported in the prior-year quarter. COST delivered an earnings surprise of 7.7%, on average, in the trailing four quarters.

Bitcoin, Like the Internet Itself, Could Change Everything

Blockchain and cryptocurrency has sparked one of the most exciting discussion topics of a generation. Some call it the “Internet of Money” and predict it could change the way money works forever. If true, it could do to banks what Netflix did to Blockbuster and Amazon did to Sears. Experts agree we’re still in the early stages of this technology, and as it grows, it will create several investing opportunities.

Zacks’ has just revealed 3 companies that can help investors capitalize on the explosive profit potential of Bitcoin and the other cryptocurrencies with significantly less volatility than buying them directly. 

See 3 crypto-related stocks now >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Costco Wholesale Corporation (COST): Free Stock Analysis Report
 
lululemon athletica inc. (LULU): Free Stock Analysis Report
 
PVH Corp. (PVH): Free Stock Analysis Report
 
GIII Apparel Group, LTD. (GIII): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/399414


4 Reasons Why You Should Add Sarepta (SRPT) to Your Portfolio

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Sarepta Therapeutics SRPT concentrates on developing exon-skipping drug candidates targeting Duchenne muscular dystrophy (DMD), a rare genetic disorder affecting children and also the most common type of muscular dystrophy. SRPT’s top line is driven by its three FDA-approved DMD drugs, namely Exondys 51, Vyondys 53 and Amondys 45.

– Zacks

Sarepta is also developing gene therapies targeting different muscular dystrophies and central nervous system disorders. Its lead gene therapy candidate SRP-9001 is being developed in a pivotal study as a potential treatment of DMD.

Here we discuss four reasons why adding the Sarepta stock to one’s portfolio may prove to be beneficial in 2021.

Top Rank, Rising Estimates and Share Price: Sarepta currently has a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

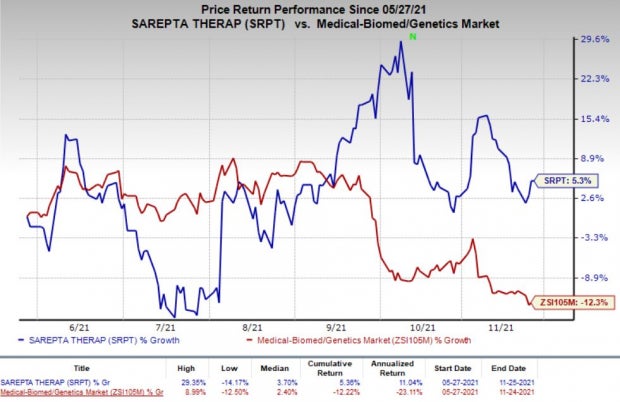
Earnings estimates for Sarepta’s loss per share have narrowed 28.2% for 2021 and 25.3% for 2022 over the past 30 days.  The stock has gained 5.3% in the past six months against a decrease of 12.3% for the industry.

Zacks Investment ResearchImage Source: Zacks Investment Research

Strong Performance of DMD Drugs: Sarepta’s Exondys 51 is the first approved disease-modifying therapy for DMD in the United States and its first product to receive marketing approval. Exondys 51 recorded impressive sales growth in the last few quarters despite the COVID-19 pandemic. Vyondys 53, approved in 2019, is boosting SRPT’s top line by bringing in additional sales. Moreover, Amondys 45 has been showing a strong demand trend since its launch earlier in 2021.

Strong performance of its three DMD drugs in the first nine months of 2021 led Sarepta to raise its revenue guidance for 2021 on its third quarter earnings call. SRPT expects product revenues in the range of $605-$615 million, indicating growth of nearly 34% from the year-ago reported figure at the midpoint. We expect robust growth in product revenues to continue in 2022.

Gene Therapy Pipeline: Sarepta is one of the pioneers in gene therapy development. Earlier this year, SRPT initiated the first pivotal study — EMBARK — to evaluate a gene therapy candidate for DMD patients.

In January 2021, management had announced that SRP-9001 met the biological endpoint of a mid-stage study during its evaluation in DMD patients but failed to achieve a statistically significant improvement in the functional endpoint of the study. This caused a massive decline in Sarepta’s share price in the same month. However, SRPT advanced the development of SRP-9001 to the pivotal EMBARK study based on favorable trends observed for function endpoint in the mid-stage study.

The pivotal study is also evaluating commercially-represented material for SRP-9001. Any positive update from the pivotal study will be a key catalyst for the stock. Sarepta is developing the micro-dystrophin-encoding gene therapy candidate in collaboration with Roche RHHBY.

Sarepta and Roche entered into a licensing agreement to develop SRP-9001 in 2019. Per the agreement, Roche has exclusive rights to launch and commercialize SRP-9001 in the ex-U.S. markets. Roche made $1.15-billion upfront payments and will pay up to $1.7 billion in regulatory and sales milestones to Sarepta.

Apart from DMD, Sarepta is developing gene therapies for treating Limb-girdle muscular dystrophy, Mucopolysaccharidosis type IIIA (MPS IIIA) and Pompe Disease in different clinical-stage studies.

Next-Generation Exon-Skipping Pipeline: Sarepta is looking to build its DMD pipeline beyond PMO-based exon-skipping treatments. SRPT is developing SRP-5051, an exon 51 skipping candidate from SRPT’s next-generation PPMO-technology, for treating DMD patients. The new technology aided in achieving a more durable response compared to PMO.

SRP-5051 targets a similar patient population as that of Sarepta’s lead drug Exondys 51. The candidate showed significantly better responses in patients with its once-monthly doses in clinical studies than the once-weekly doses of Exondys 51.

Successful development will offer DMD patients a better alternative with a much lower dose and a new drug with longer patent protection. SRPT initiated the pivotal part B of the MOMENTUM study in the fourth quarter of 2021.

Conclusion

Strong demand for its commercial DMD drugs and promising pipeline progress represents an opportunity for investors to gain from Sarepta’s potential growth over the next few quarters. On the flip side, shares of SRPT declined more than 50% on Jan 8, 2021, following a negative clinical update on its DMD gene therapy candidate, SRP-9001. However, any positive update from the ongoing pivotal study on SRP-9001 will likely be a catalyst for the stock’s substantial upside going forward.

A few other companies also developing gene therapies targeting DMD patients are Pfizer PFE and REGENXBIO RGNX. Successful development of these gene therapy candidates may increase competition for Sarepta.

Pfizer began dosing in the phase III CIFFREO study last December. The study is evaluating the safety and efficacy of its gene therapy candidate PF-06939926 for treating DMD. Pfizer is the closest competitor of Sarepta in developing a DMD gene therapy with both companies evaluating their respective candidates in late-stage studies. Pfizer’s DMD candidate enjoys fast track, orphan drug and rare pediatric disease designations in the United States.

REGENXBIO plans to start a clinical study next year to evaluate its gene therapy candidate RGX-202 for treating DMD. RGX-202 was designed using REGENXBIO’s proprietary NAV AAV8 vector to deliver an optimized microdystrophin transgene to develop a targeted therapy for improved resistance to muscle damage associated with DMD. REGENXBIO received an orphan drug designation for the candidate earlier this month.

Bitcoin, Like the Internet Itself, Could Change Everything

Blockchain and cryptocurrency has sparked one of the most exciting discussion topics of a generation. Some call it the “Internet of Money” and predict it could change the way money works forever. If true, it could do to banks what Netflix did to Blockbuster and Amazon did to Sears. Experts agree we’re still in the early stages of this technology, and as it grows, it will create several investing opportunities.

Zacks’ has just revealed 3 companies that can help investors capitalize on the explosive profit potential of Bitcoin and the other cryptocurrencies with significantly less volatility than buying them directly. 

See 3 crypto-related stocks now >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Roche Holding AG (RHHBY): Free Stock Analysis Report
 
Pfizer Inc. (PFE): Free Stock Analysis Report
 
Sarepta Therapeutics, Inc. (SRPT): Free Stock Analysis Report
 
REGENXBIO Inc. (RGNX): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/399415


Here’s Why You Should Retain Crown Castle (CCI) Stock Now

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Growth in mobile data usage, spectrum availability and high-network investments in wireless carriers will likely spur demand for Crown Castle International Corp.’s CCI properties.

– Zacks

The ability to offer a holistic network solution with towers, fiber and small cells, and ample liquidity poises Crown Castle well for long-term growth.

As the data volume of wireless and wired networks is growing rapidly amid the widespread adoption of smartphones and applications, the network carriers continue to spend on network deployments to harness spectrum abilities as well as improve and densify their cell sites and coverage.

Hence, to capitalize on this opportunity, Crown Castle and other tower operators like SBA Communications SBAC are increasingly investing in new small cell and fiber assets to enhance the network density required for their customers’ wireless networks.

A strong and creditworthy tenant base adds resiliency to Crown Castle’s business. CCI has long-term (typically 5-15 year) tower lease agreements with top U.S. carriers, which contribute to recurring site rental cash flows over the long term.

Additionally, Crown Castle has sufficient liquidity and enjoys a decent balance sheet position. CCI exited third-quarter 2021 with cash and cash equivalents of $357 million, and $5 billion of undrawn capacity in its revolver.  As of the third-quarter end, CCI enjoyed investment-grade credit ratings of BBB-, BBB+ and Baa3 from Standard & Poor’s, Fitch and Moody’s, respectively, facilitatingits access to the debt markets at attractive terms.

However, tenant concentration is very high for Crown Castle. In fact, the top three among its customers, namely Verizon VZ, AT&T T and T-Mobile, accounted for majority of its total revenues.

Hence, loss of either Verizon, AT&T and T-Mobile or any consolidation among the threewill significantly hamper Crown Castle’s top line. CCI’s performance is dependent on carrier spending and therefore, any pullback or rationalization in network spending by tenants might adversely affect its growth.

Shares of this currently Zacks Rank #3 (Hold) Crown Castle have appreciated 17.3% year to date, underperforming the industry’s rally of 24.2%. However, the estimate revision trend of 2021 fund from operations (FFO) per share indicates a favorable outlook for CCI as the same has been revised marginally upward over the past two months.

Zacks Investment ResearchImage Source: Zacks Investment Research

The Zacks Consensus Estimate for SBA Communications’ current-year FFO per share has been raised 1% in the past month. SBAC currently has a Zacks Rank of 3.

You can see  the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

Over the last four quarters, SBAC’s FFO per share surpassed the consensus estimate on all occasions, the average being 2.89%. Shares of SBAC have appreciated 19.3% in the past six months, outperforming the industry’s rally of 10%.

The Zacks Consensus Estimate for Verizon’s 2021 FFO per share has moved marginally north in the past two months. VZ is currently Zacks #3 Ranked.

Over the last four quarters, Verizon’s FFO per share surpassed the consensus mark on all occasions, the average being 3.73%. Shares of VZ have declined 5.7% in the past three months, compared with the industry’s decrease of 10.3%.

The Zacks Consensus Estimate for AT&T’s 2021 FFO per share has moved marginally south in the past week. T is currently a #3 Ranked player.

AT&T’s FFO per share surpassed the consensus mark inall the last four quarters, the average being 10.02%. Shares of T have declined 9.8% in the past three months compared with the industry’s fall of 10.3%.

Note: Anything related to earnings presented in this write-up represent funds from operations (FFO) — a widely used metric to gauge the performance of REITs.

Bitcoin, Like the Internet Itself, Could Change Everything

Blockchain and cryptocurrency has sparked one of the most exciting discussion topics of a generation. Some call it the “Internet of Money” and predict it could change the way money works forever. If true, it could do to banks what Netflix did to Blockbuster and Amazon did to Sears. Experts agree we’re still in the early stages of this technology, and as it grows, it will create several investing opportunities.

Zacks’ has just revealed 3 companies that can help investors capitalize on the explosive profit potential of Bitcoin and the other cryptocurrencies with significantly less volatility than buying them directly. 

See 3 crypto-related stocks now >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
AT&T Inc. (T): Free Stock Analysis Report
 
Verizon Communications Inc. (VZ): Free Stock Analysis Report
 
Crown Castle International Corporation (CCI): Free Stock Analysis Report
 
SBA Communications Corporation (SBAC): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/399416


Are You Looking for a High-Growth Dividend Stock? Essa Bancorp (ESSA) Could Be a Great Choice

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

All investors love getting big returns from their portfolio, whether it’s through stocks, bonds, ETFs, or other types of securities. However, when you’re an income investor, your primary focus is generating consistent cash flow from each of your liquid investments.

– Zacks

Cash flow can come from bond interest, interest from other types of investments, and of course, dividends. A dividend is that coveted distribution of a company’s earnings paid out to shareholders, and investors often view it by its dividend yield, a metric that measures the dividend as a percent of the current stock price. Many academic studies show that dividends make up large portions of long-term returns, and in many cases, dividend contributions surpass one-third of total returns.

Essa Bancorp in Focus

Headquartered in Stroudsburg, Essa Bancorp (ESSA) is a Finance stock that has seen a price change of 15.73% so far this year. Currently paying a dividend of $0.12 per share, the company has a dividend yield of 2.77%. In comparison, the Financial – Savings and Loan industry’s yield is 2.49%, while the S&P 500’s yield is 1.34%.

Looking at dividend growth, the company’s current annualized dividend of $0.48 is up 2.1% from last year. Over the last 5 years, Essa Bancorp has increased its dividend 3 times on a year-over-year basis for an average annual increase of 7.39%. Any future dividend growth will depend on both earnings growth and the company’s payout ratio; a payout ratio is the proportion of a firm’s annual earnings per share that it pays out as a dividend. Essa Bancorp’s current payout ratio is 29%. This means it paid out 29% of its trailing 12-month EPS as dividend.

ESSA is expecting earnings to expand this fiscal year as well. The Zacks Consensus Estimate for 2021 is $1.73 per share, representing a year-over-year earnings growth rate of 4.85%.

Bottom Line

Investors like dividends for a variety of different reasons, from tax advantages and decreasing overall portfolio risk to considerably improving stock investing profits. It’s important to keep in mind that not all companies provide a quarterly payout.

High-growth firms or tech start-ups, for example, rarely provide their shareholders a dividend, while larger, more established companies that have more secure profits are often seen as the best dividend options. Income investors must be conscious of the fact that high-yielding stocks tend to struggle during periods of rising interest rates. That said, they can take comfort from the fact that ESSA is not only an attractive dividend play, but also represents a compelling investment opportunity with a Zacks Rank of #2 (Buy).

Breakout Biotech Stocks with Triple-Digit Profit Potential

The biotech sector is projected to surge beyond $2.4 trillion by 2028 as scientists develop treatments for thousands of diseases. They’re also finding ways to edit the human genome to literally erase our vulnerability to these diseases.

Zacks has just released Century of Biology: 7 Biotech Stocks to Buy Right Now to help investors profit from 7 stocks poised for outperformance. Recommendations from previous editions of this report have produced gains of +205%, +258% and +477%. The stocks in this report could perform even better.

See these 7 breakthrough stocks now>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
ESSA Bancorp, Inc. (ESSA): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/399223


BGSF or WNS: Which Is the Better Value Stock Right Now?

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Investors with an interest in Business – Services stocks have likely encountered both BGSF (BGSF) and WNS Holdings Limited (WNS). But which of these two companies is the best option for those looking for undervalued stocks? Let’s take a closer look.

– Zacks

There are plenty of strategies for discovering value stocks, but we have found that pairing a strong Zacks Rank with an impressive grade in the Value category of our Style Scores system produces the best returns. The proven Zacks Rank puts an emphasis on earnings estimates and estimate revisions, while our Style Scores work to identify stocks with specific traits.

Both BGSF and WNS Holdings Limited have a Zacks Rank of # 2 (Buy) right now. Investors should feel comfortable knowing that both of these stocks have an improving earnings outlook since the Zacks Rank favors companies that have witnessed positive analyst estimate revisions. But this is just one piece of the puzzle for value investors.

Value investors also try to analyze a wide range of traditional figures and metrics to help determine whether a company is undervalued at its current share price levels.

The Value category of the Style Scores system identifies undervalued companies by looking at a number of key metrics. These include the long-favored P/E ratio, P/S ratio, earnings yield, cash flow per share, and a variety of other fundamentals that help us determine a company’s fair value.

BGSF currently has a forward P/E ratio of 12.63, while WNS has a forward P/E of 26.72. We also note that BGSF has a PEG ratio of 0.63. This popular metric is similar to the widely-known P/E ratio, with the difference being that the PEG ratio also takes into account the company’s expected earnings growth rate. WNS currently has a PEG ratio of 2.03.

Another notable valuation metric for BGSF is its P/B ratio of 2.09. The P/B ratio is used to compare a stock’s market value with its book value, which is defined as total assets minus total liabilities. For comparison, WNS has a P/B of 6.42.

These metrics, and several others, help BGSF earn a Value grade of A, while WNS has been given a Value grade of C.

Both BGSF and WNS are impressive stocks with solid earnings outlooks, but based on these valuation figures, we feel that BGSF is the superior value option right now.

Breakout Biotech Stocks with Triple-Digit Profit Potential

The biotech sector is projected to surge beyond $2.4 trillion by 2028 as scientists develop treatments for thousands of diseases. They’re also finding ways to edit the human genome to literally erase our vulnerability to these diseases.

Zacks has just released Century of Biology: 7 Biotech Stocks to Buy Right Now to help investors profit from 7 stocks poised for outperformance. Recommendations from previous editions of this report have produced gains of +205%, +258% and +477%. The stocks in this report could perform even better.

See these 7 breakthrough stocks now>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
BGSF, Inc. (BGSF): Free Stock Analysis Report
 
WNS Holdings Limited (WNS): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/399224


Why HP (HPQ) is a Great Dividend Stock Right Now

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Getting big returns from financial portfolios, whether through stocks, bonds, ETFs, other securities, or a combination of all, is an investor’s dream. However, when you’re an income investor, your primary focus is generating consistent cash flow from each of your liquid investments.

– Zacks

Cash flow can come from bond interest, interest from other types of investments, and of course, dividends. A dividend is the distribution of a company’s earnings paid out to shareholders; it’s often viewed by its dividend yield, a metric that measures a dividend as a percent of the current stock price. Many academic studies show that dividends account for significant portions of long-term returns, with dividend contributions exceeding one-third of total returns in many cases.

HP in Focus

HP (HPQ) is headquartered in Palo Alto, and is in the Computer and Technology sector. The stock has seen a price change of 30.91% since the start of the year. The personal computer and printer maker is paying out a dividend of $0.19 per share at the moment, with a dividend yield of 2.41% compared to the Computer – Mini computers industry’s yield of 1.51% and the S&P 500’s yield of 1.33%.

Looking at dividend growth, the company’s current annualized dividend of $0.78 is up 0.6% from last year. HP has increased its dividend 5 times on a year-over-year basis over the last 5 years for an average annual increase of 10.20%. Looking ahead, future dividend growth will be dependent on earnings growth and payout ratio, which is the proportion of a company’s annual earnings per share that it pays out as a dividend. HP’s current payout ratio is 22%. This means it paid out 22% of its trailing 12-month EPS as dividend.

Earnings growth looks solid for HPQ for this fiscal year. The Zacks Consensus Estimate for 2021 is $4.03 per share, representing a year-over-year earnings growth rate of 6.33%.

Bottom Line

From greatly improving stock investing profits and reducing overall portfolio risk to providing tax advantages, investors like dividends for a variety of different reasons. It’s important to keep in mind that not all companies provide a quarterly payout.

Big, established firms that have more secure profits are often seen as the best dividend options, but it’s fairly uncommon to see high-growth businesses or tech start-ups offer their stockholders a dividend. During periods of rising interest rates, income investors must be mindful that high-yielding stocks tend to struggle. With that in mind, HPQ is a compelling investment opportunity. Not only is it a strong dividend play, but the stock currently sits at a Zacks Rank of 3 (Hold).

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
HP Inc. (HPQ): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/399031


ATCO vs. TROW: Which Stock Should Value Investors Buy Now?

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Investors interested in Financial – Investment Management stocks are likely familiar with Atlas (ATCO) and T. Rowe Price (TROW). But which of these two stocks presents investors with the better value opportunity right now? Let’s take a closer look.

– Zacks

The best way to find great value stocks is to pair a strong Zacks Rank with an impressive grade in the Value category of our Style Scores system. The proven Zacks Rank puts an emphasis on earnings estimates and estimate revisions, while our Style Scores work to identify stocks with specific traits.

Atlas and T. Rowe Price are sporting Zacks Ranks of #2 (Buy) and #3 (Hold), respectively, right now. Investors should feel comfortable knowing that ATCO likely has seen a stronger improvement to its earnings outlook than TROW has recently. But this is only part of the picture for value investors.

Value investors also try to analyze a wide range of traditional figures and metrics to help determine whether a company is undervalued at its current share price levels.

The Style Score Value grade factors in a variety of key fundamental metrics, including the popular P/E ratio, P/S ratio, earnings yield, cash flow per share, and a number of other key stats that are commonly used by value investors.

ATCO currently has a forward P/E ratio of 8.11, while TROW has a forward P/E of 16.33. We also note that ATCO has a PEG ratio of 0.29. This metric is used similarly to the famous P/E ratio, but the PEG ratio also takes into account the stock’s expected earnings growth rate. TROW currently has a PEG ratio of 1.81.

Another notable valuation metric for ATCO is its P/B ratio of 1.01. The P/B ratio is used to compare a stock’s market value with its book value, which is defined as total assets minus total liabilities. For comparison, TROW has a P/B of 5.67.

These metrics, and several others, help ATCO earn a Value grade of A, while TROW has been given a Value grade of C.

ATCO stands above TROW thanks to its solid earnings outlook, and based on these valuation figures, we also feel that ATCO is the superior value option right now.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Atlas Corp. (ATCO): Free Stock Analysis Report
 
T. Rowe Price Group, Inc. (TROW): Free Stock Analysis Report
 
To read this article on Zacks.com click here.

https://www.entrepreneur.com/article/399032