Best Penny Stocks To Buy For A Short Squeeze? 5 To Watch Today

This is going to be an exciting week for the stock market. We’ve got the US Thanksgiving holiday on Thursday followed by a half-day for equities on Friday. For some, this isn’t a week to slow down but to hit the accelerator, especially when it comes to penny stocks. Though broader markets will stick to their trends, we’re sure to see some fireworks in the land of small- and micro-cap stocks. It’s almost like clockwork; each year during shorter, holiday weeks, retail attention focuses on cheap stocks to buy.

PennyStocks.com – PennyStocks

Adding to this, traders tend to look for different trends. Recently, there’s been a growing interest in things like EV and renewable energy. Then again, you also can’t ignore the digital asset and metaverse stocks that have popped up this quarter as well. Everything from cryptocurrency and NFTs to virtual worlds and digital ecosystems is grabbing attention.

Are there other trends to track? Of course, and a few of these trends center around more technical traits. Things like low float and short squeeze stocks remain a hot button. That’s thanks, in part to what we saw earlier this year with the rise of the “apes” and the dramatic breakouts for countless meme stocks. This is where we’ll look today; stocks with higher short interest. There’s no guarantee that they’ll experience a short squeeze. As they say, knowing is half the battle.

5 Short Squeeze Penny Stocks To Watch

  1. Camber Energy (NYSE:CEI)
  2. Senseonics Holdings (NYSE:SENS)
  3. Progenity (NASDAQ:PROG)
  4. Aspira Women’s Health (NASDAQ:AWH)
  5. Vinco Ventures (NASDAQ:BBIG)

1. Camber Energy (NYSE:CEI)

One of the newest meme stocks to watch is Camber Energy. The company caught the sweeping interest of retail traders during late summer. Shares of CEI stock exploded from below $0.35 to highs of $4.85. But just as quickly as it broke out, so too did it break down. One of the biggest bearish catalysts came in the form of a short report from Kerrisdale Capital citing concerns about the company compared to the market activity at the time.

Read more: Top Penny Stocks to Add to Your Watchlist in Late November

Regardless, CEI stock continues catching intermittent boosts in trading momentum. This last week has been one of those periods, thanks to a response to these exact claims made by Kerrisdale.

Recent CEI Stock News

Camber has worked to solidify a deal with ESG Clean Energy LLC. The company develops net-zero carbon footprints and offers clean energy solutions. Camber and ESG signed an agreement for an exclusive license to specific stationary electric power generation intellectual property. This included the way heat from manufacturing was captured and reused for other power needs.

In its statement, ESG expressed the information given from Kirrsdale contained “misleading and inaccurate” information. With this response, there has been a bit more optimism in the market during the second half of November.

While CEI stock isn’t the highest on the list as far as short interest goes, it has a higher percentage than others in the stock market today. Fintel data shows the short float percentage for CEI sitting just over 13% right now.

short squeeze penny stocks to buy Camber Energy CEI stock chart

2. Senseonics Holdings (NYSE:SENS)

If there’s been one company consistently on a watch list this year, it has been Senseonics. Despite a recent pullback from November highs, SENS stock has made a big move year-to-date. Where certain penny stocks experience a big move over one or two days and then whisk away, never to be heard from again, Senseonics has managed a consistent uptrend from under $1 in January to over $3.50 to start this short week.

Read more: 3 Penny Stocks to Add to Your Watch List Right Now

The medical device company has found its niche in glucose monitoring. Its Eversense platform gives patients the ability to track glucose data without finger-prick methods, which is relatively mainstream. The device is implanted into each person, and then it sends signals to an application throughout the day for constant monitoring.

Recent SENS Stock News

Earnings are on the docket for hundreds of companies this month. Senseonics reported its latest round earlier in November. Following an EPS beat, the market seems focused on what’s coming next for the company. In particular, Eversense is currently in review by the FDA for Premarket Approval and an expected decision in the coming months. Keep this in mind if SENS stock is on your watch list right now.

As far as the percentage of the float that’s short in this stock, Fintel data shows that figure sitting around 25.24% right now.

short squeeze penny stocks to buy Senseonics Holdings SENS stock chart

3. Progenity (NASDAQ:PROG)

A long-time placeholder on our list of penny stocks with higher short interest is Progenity. In fact, since late September, PROG stock has been at the center of the spotlight when it comes to this trend. In addition, Progenity has worked toward advancing its Preecludia platform, which is a preeclampsia rule-out test. The platform aids physicians in evaluating and managing patients with potentially compromised pregnancies. The company has engaged an advisory firm to launch its licensing initiatives.

Further to this, Progenity also received a patent allowance for one of the critical assays for the test.

Recent PROG Stock News

Other than the future of Preecludia, Progenity has also worked to streamline and lean out its operations. In the company’s Q3 business update, management explained that the company implemented cost-cutting measures that could result in roughly $145 million in savings annually.

“Progenity is making great strides in its transformation into a biotherapeutics company. I’m looking forward to accelerating this process, and to helping the company efficiently advance its innovation pipeline, which has great potential to impact the diagnosis and treatment of serious diseases,” said Adi Mohanty, Chief Executive Officer of Progenity.

Even with this brighter outlook for the overall transformation of Progenity, short interest remains a key catalyst. According to Fintel data, PROG stock’s short float percentage sits around 19.5% right now.

short squeeze penny stocks to buy Progenity PROG stock chart

4. Aspira Women’s Health (NASDAQ:AWH)

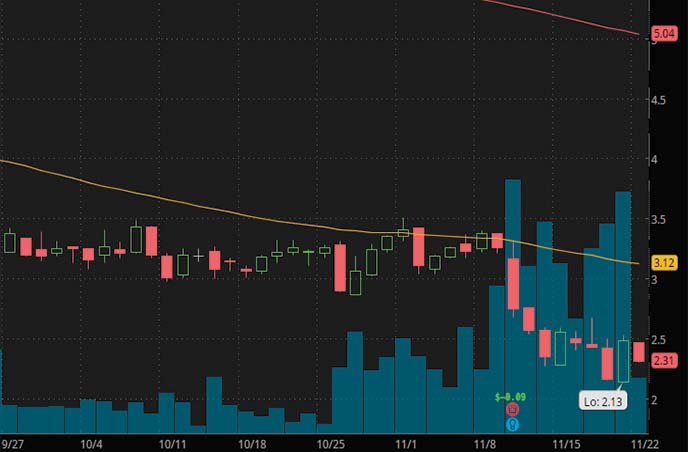
Shares of Aspira Women’s Health have seen a very different response in the market compared to SENS. However, a recent spike in trading volume may have turned some attention to AWH stock at the end of last week. Aspira dropped heavily after reporting mixed earnings, but Friday’s November 19th session saw a noticeable reversal in trend. The penny stock bounced from lows of $2.13 to after-hour highs of $2.62.

Recent AWH Stock News

Similar to Senseonics, earnings were the latest fundamental development reported on by the company. Although Aspira missed the EPS estimate, it was able to beat on sales. It reported $1.67 million compared to an expected $1.62 million from analysts. Furthermore, the women’s healthcare company discussed considerable progress in its product collaboration with the Dana Farber Cancer Institute and completed a Phase 1 proof-of-concept study for developing an ovarian cancer screening application. The company’s also waiting on awaiting a resolution from the FDA regarding its Endocheck product by the end of the year. This is Aspira’s platform to identify Endometriosis in patients.

As far as Fintel’s short data goes, AWH stock sits with a short float percentage of 17.48% right now.
short squeeze penny stocks to buy Allied Womens Health AWH stock chart

5. Vinco Ventures (NASDAQ:BBIG)

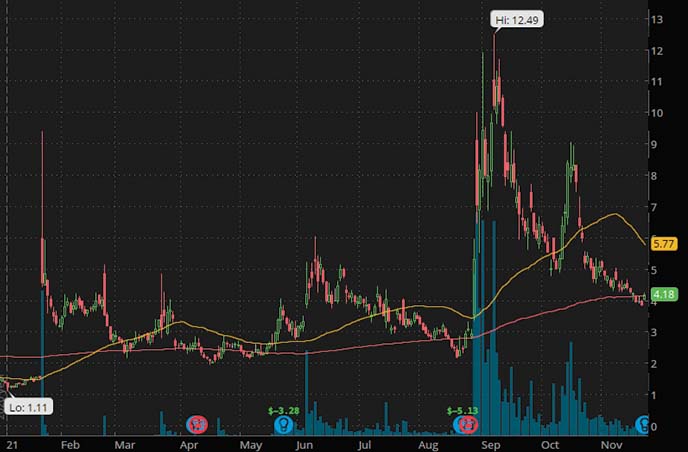
Similar to Camber Energy, Vinco Ventures has become a frequent mention on the active list of meme stocks to watch right now. The tech company has several angles that have helped it gain interest among traders this year. From its deal for a TikTok competitor technology platform to a spin-off of a crypto company, BBIG stock has had plenty of catalysts along the way. This has culminated into a year-to-date move of more than 260%.

Recent BBIG Stock News

While most of the previous interest has stemmed from its Cryptyde spin-off, speculation could have begun building heading into next week. One of the biggest reasons for this has to do with its November 19 update. Management said it will report Q3 earnings after the bell on November 22 (today). There’s also a webcast and conference call set for November 23. Even with this speculative momentum, it’s important to note that earnings can present a higher risk situation. Depending on what’s reported, the market can respond in kind, and sometimes that isn’t in favor of the bulls. Keep this in mind if BBIG stock is on your list right now.

As far as short data is concerned, Fintel shows BBIG with a short float percentage of 25.67% heading into earnings.
short squeeze penny stocks to buy Vinco Ventures BBIG stock chart

Are Short Squeeze Penny Stocks On Your Radar?

Short squeezes can be very exciting, especially when it comes to short-term breakouts. However, it’s essential to understand that they can also break down just as quickly as they move higher. So if any companies with high short interest are on your list, don’t solely bank on the fact that there’s “a short” in a stock. Doing additional research and understanding underlying catalysts is important, especially regarding penny stocks (with or without higher short interest).

https://www.entrepreneur.com/article/398548


2 Blue Chip Stocks to Buy Now at Deep Discounts and Hold for Years

Mega-cap technology stocks have surged to new highs recently. The momentum pushed the Nasdaq to records Friday as the market heads into a Thanksgiving-shortened week. The quick rebound came after investors took a temporary breather earlier this month.

– Zacks

The bulls have fought their way back in control—at least temporarily—in the face of 30-year high inflation in October. Wall Street is apparently still optimistic despite rising prices, supply chain setbacks, and difficulty filling millions of open jobs.

The backdrop for the positivity might focus on the fact that surging prices have not negatively impacted margins projections for the S&P 500 for 2022 or 2023. On top of that, fresh data out earlier this week showed U.S. retail sales jumped by a seasonally adjusted 1.7% in October vs. September. This is a great sign for the entire holiday shopping period.

Helping support the market moment, as is often the case, are strong earnings results and low rates. And interest rates are poised to remain at historically low levels for the foreseeable future even if the Fed was forced to start raising them tomorrow.  

All that said, now might not be the best time to buy into mega-cap tech stocks. Instead, investors with long-term outlooks should consider blue-chip stocks trading well below their records…

Comcast CMCSA

Comcast is a global media and technology conglomerate that operates broadband and wireless internet businesses, as well as paid-TV and much more. CMCSA expanded its international reach through its Sky acquisition, and its streaming TV segment, driven by NBCUniversal’s Peacock is slowly helping counterbalance its fading cable TV unit that’s lost subscribers to cord-cutting.

Comcast’s movie studio and theme parks, which operate under the Universal brand, have bounced back recently amid the economic reopening. Meanwhile, its Xfinity Mobile cellphone business, which launched in 2017, has continued to gain steam. The segment added 285K customers last quarter for its best ever-showing, as part of a solid Q3 that saw Comcast beat our Q3 earnings and revenue estimates in late October.

Comcast has now topped our adjusted quarterly earnings estimates by an average of 21% in the trailing four quarters, including a 16% beat last period after its Q3 EPS jumped 34%.

Zacks estimates call for its FY21 earnings to climb 21% and then pop another 20% higher next year to $3.78 a share. Meanwhile, its revenue is projected to jump 12% in FY21 and another 7% higher to reach $123.44 billion in FY22, as it returns to solid growth after a slight covid-hit downturn.

Zacks Investment ResearchImage Source: Zacks Investment Research

Comcast, which lands a Zacks Rank #3 (Hold) right now, also bought back $1.5 billion worth of its shares last quarter and its 1.90% dividend yield nearly matches the 30-year U.S. Treasury and blows away the S&P 500’s 1.21%. Wall Street also remains largely bullish on Comcast, with 11 of the 15 brokerage recommendations Zacks has at “Strong Buys.”

CMCSA shares started to fall at the end of August, alongside the broader market. But the media and internet titan has failed to mount any real comeback just yet, down 16% from its records as of Friday at $51.91 a share. Comcast is trading well below its 50-day and 200-day moving averages.

Luckily, its Zacks consensus prices target of nearly $65 a share marks 25% upside to its current levels. And the recent downturn has it trading below its five-year median at 14.2X forward 12-month earnings. This also represents a 30% discount to its industry and its own year-long highs. And Comcast is closing in on oversold RSI levels (30 or under) at 38, while the S&P 500 is at overbought.

Disney DIS

Disney fell well short of our Q4 earnings estimates on November 10, and Wall Street dumped the stock on slowing streaming growth. The recent post-earnings decline extends a longer downward trend that sets up a solid entry point for the entertainment powerhouse.

The firm added roughly 2.1 million new Disney+ subscribers to come in far below analysts estimate. The figure also marked its slowest growth since it launched in November of 2019. That “miss” is a tad misleading and it clouds how far the streaming service has come.

Disney+ boasts 118.1 million subscribers at the moment and executives reiterated on its earnings call the 230 to 260 million subscriber guidance by the end of FY24 for its namesake streaming platform. The new goal blows away its initial 60 to 90 million projections back in the fall of 2019.

Overall, its total streaming space hit 179 million across Disney+, ESPN+ and Hulu—NFLX closed Q3 with 214 million. The company is now one of the major players in a growth industry and its catalog and brands remain at the top of the food chain.

Disney’s Star Wars and Marvel movies dominated theaters before the pandemic and covid temporarily crushed its parks segment. The entrainment titan’s parks and resorts from Disney World in Orlando to Shanghai Disney Resort are now open. On top of that, it began releasing movies again in theaters, with comparatively strong showings given the circumstances. Plus, more and more people are poised to venture back to the theaters in 2022.

Zacks Investment ResearchImage Source: Zacks Investment Research

Disney’s revenue climbed 26% in the quarter and 3% on the year. Zacks estimates now call for its FY22 revenue to soar 25% to crush its pre-covid totals by $16 billion at $84.39 billion, with FY23 ready to climb 12% higher to over $94 billion. At the bottom end of the income statement, its adjusted earnings are expected to skyrocket 107% and 31%, respectively during this stretch.

Disney lands a Zacks Rank #3 (Hold) and its current-year EPS consensus slipped slightly following its release. Similar to its peer on our list today, Wall Street is still bullish on Disney for the long haul, with 11 of the 17 brokerage recommendations at “Strong Buys,” with two more “Buys” and nothing under a “Hold.”

Disney closed regular trading hours Friday 23% below its records at $154.00 a share. The pullback from its highs includes a roughly 13% decline since its earnings release. DIS is now trading around where it was last December and the post-earnings drop sent in well below oversold RSI levels (30 or under) at 25.

The decline completely recalibrated its valuation that had grown rather out of whack amid its huge pandemic climb, when its parks and theater units were crushed and it continued to spend on streaming. Disney now trades at a 60% discount to its year-long highs at 30.2X forward 12-month earnings. The stock does sit well off its 50-day and 200-day moving averages.

Yet, its current Zacks consensus price target of $201.95 share represents 31% upside potential to Friday’s close. All things considered, investors with long-term horizons might want to scoop up Disney stock now, even if it falls further because timing doesn’t matter as much if you plan to hold DIS for years.

More Stock News: This Is Bigger than the iPhone!

It could become the mother of all technological revolutions. Apple sold a mere 1 billion iPhones in 10 years but a new breakthrough is expected to generate more than 77 billion devices by 2025, creating a $1.3 trillion market.

Zacks has just released a Special Report that spotlights this fast-emerging phenomenon and 4 tickers for taking advantage of it. If you don’t buy now, you may kick yourself in 2022.

Click here for the 4 trades >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Comcast Corporation (CMCSA): Free Stock Analysis Report
 
The Walt Disney Company (DIS): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/398363


S&P 500 Growth ETF (IVW) Hits a New 52-Week High

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

For investors looking for momentum, iShares S&P 500 Growth ETF IVW is probably a suitable pick. The fund just hit a 52-week high and is up 38.7% from its 52-week low price of $59.97/share.

– Zacks

Let’s take a look at the fund and its near-term outlook to gain an insight into where it might be headed:

IVW in Focus

iShares S&P 500 Growth ETF seeks to track the investment results of an index composed of large-capitalization U.S. equities that exhibit growth characteristics. It has AUM of $38.89 billion and charges 18 basis points in annual fees.

Why the Move?

Wall Street has been loudly cheering the third-quarter earnings season. There have also been certain upbeat economic data releases that have raised investor optimism. The coronavirus vaccine rollout is gradually helping control the spread of the outbreak across the globe. Accordingly, the global demand and economic growth levels are on the path of recovery from the pandemic-led slump. Investors have rotated back into growth-oriented market areas in recent weeks on optimism surrounding the economic recovery. These factors are making funds like IVW more attractive.

More Gains Ahead?

The fund has a Zacks ETF Rank #2 (Buy). It seems like it will remain strong, with a positive weighted alpha of 37.97, which gives cues of further rally.

Want key ETF info delivered straight to your inbox?

Zacks’ free Fund Newsletter will brief you on top news and analysis, as well as top-performing ETFs, each week.

Get it free >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
iShares S&P 500 Growth ETF (IVW): ETF Research Reports
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/398364


The Fitness Industry’s Roundtrip

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

What a difference a single year can make. Now that most of the pandemic-related restrictions have been lifted across the country, investors have been aiming to take advantage of stocks that stand to benefit from the economic reopening. Whereas last year witnessed a surge in many of the ‘stay-at-home’ names, the beginnings of a return to normalcy have coincided with a surge in industries that were decimated last year.

– Zacks

Gyms were certainly one of the hardest hit businesses in 2020, and it’s easy to understand why that was the case. Their monthly revenues disappeared overnight as gyms were forced to freeze memberships at no cost to the consumer.

Social distancing and other restrictions that were imposed upon the public left zero chance of getting a workout in at the gym for a solid four months in most states. And even when gyms were permitted to reopen, many members were extremely hesitant to return. A survey conducted by Statista Global Consumer showed 46% of respondents were very uncomfortable going back to the gym in the latter half of 2020.

As such, people turned to exercise at home, which led to well-known names like Peloton PTON and Nautilus NLS skyrocketing in 2020. Last year, it seemed like everyone was buying a spin bike to use in the comfort of their home (I know one ended up in mine). While both Peloton and Nautilus had a stellar 2020, we can see in the chart below that these ‘stay-at-home’ names have reversed course this year, while the more traditional Planet Fitness has held up well.

Zacks Investment ResearchImage Source: Zacks Investment Research

Every fitness advertisement last year claimed that the industry had been changed forever. Yet just like many major cities have seen numbers come roaring back after an initial scare, gyms are also seeing members return. This is an industry that has truly completed the roundtrip.

People are going back to the gym. And while it’s certainly convenient to workout in your own residence, there is simply no getting around the fact that gyms have a much wider array of machines and equipment to help keep people in shape – not to mention extra amenities such as pools, spas and other luxuries.

Let’s take a look at three stocks that stand to benefit from the continued economic reopening.

Lululemon Athletica (LULU)

One could argue that Lululemon has created its own specific niche within the fitness industry. Last year, LULU acquired Mirror, the smart at-home workout machine founded by Brynn Putnam. And while it has been touting Mirror in much of its marketing, the company has built a devout following over the years for its athletic apparel and yoga-related products.

Currently sporting a Zacks #2 Buy rating, a return to the gym has undoubtedly provided a boost to LULU’s core business. The company has seen a rebound in brick-and-mortar sales driven by an increase in store traffic as consumers have become more comfortable shopping in store. In the second quarter, traffic trends increased by over 150% compared to last year. LULU most recently reported an EPS beat of $1.65 back in September, delivering a 36% surprise over consensus and 123% growth over the same quarter in 2020.

lululemon athletica inc. Price, Consensus and EPS Surprise

lululemon athletica inc. Price, Consensus and EPS Surprise

lululemon athletica inc. price-consensus-eps-surprise-chart | lululemon athletica inc. Quote

The company is part of the Textile – Apparel industry within the Consumer Discretionary sector. This industry currently boasts a Zacks Industry rank of 66, which puts it in the top 26% of all 253 industries.

LULU’s next earnings report is slated for December 9th. Management remains upbeat and earlier this year raised its outlook for fiscal 2021. LULU’s current full-year Zacks Consensus Estimates are anticipating earnings of $7.51 per share, which would represent a nearly +60% change year-over-year.

The company’s solid financial footing and strong business momentum should serve it well heading into next year. 

Dicks Sporting Goods (DKS)

Currently holding a Zacks #3 ranking, DKS stock has been on a tear this year. It has advanced over 160% and is showing no signs of slowing down. The company is on a hot streak in terms of EPS surprises. In each of the last three quarters, DKS has handily beat estimates with an average EPS surprise of over 118%. It most recently reported earnings back in August of $5.08 per share, up 58% from the prior year quarter and a surprise of over 81% compared to the $2.80 consensus.

DICK’S Sporting Goods, Inc. Price, Consensus and EPS Surprise

DICK'S Sporting Goods, Inc. Price, Consensus and EPS Surprise

DICK’S Sporting Goods, Inc. price-consensus-eps-surprise-chart | DICK’S Sporting Goods, Inc. Quote

The sporting goods retailer is witnessing increased demand from the economic reopening, which has translated into more consumer purchases for its athletic shoes, apparel and other accessories. Solid Q2 results were driven by an increase in net sales of 21% year-over-year and double-digit sales growth in its core categories – hardlines, apparel and footwear.

DKS management revised its fiscal 2021 guidance earlier this year. Same-store sales are likely to grow 18-20%, up substantially from the prior 8-11%. Adjusted earnings are expected to be in the range of $12.45-$12.95, reflecting a drastic improvement from the $8-$8.70 previously expected.

The company is part of the Retail – Miscellaneous industry group, which ranks 106 out of all 253 industries, putting it in the top 42%.

Zacks full-year current consensus estimates are sitting at $12.91, which would represent an increase of nearly 111% year-over-year. DKS is due to report quarterly earnings next Tuesday, November 23rd. The consensus estimate has been revised upward by 3.3% in the past 30 days.

What the Zacks Model Reveals

The Zacks Model predicts an earnings beat for DKS for the upcoming earnings announcement. The combination of a positive Earnings ESP (Expected Surprise Prediction) and a Zacks Rank #1 (Strong Buy), #2 (Buy) or #3 (Hold) increases the chances of an earnings beat. The Earnings ESP looks to find companies that have recently seen positive earnings estimate revision activity. DKS currently has an Earnings ESP of +27.97%.

Life Time Group Holdings (LTH)

Life Time, currently a Zacks #3 Hold, is a leading lifestyle brand offering premium fitness, wellness and health experiences to over 1.4 million individual members. The company was founded nearly 30 years ago and is headquartered in Chanhassen, Minnesota. Life Time operates over 150 fitness centers across 29 states as well as a Canadian location.

Prior to the pandemic, the company generated $1.9 billion in revenue in 2019, with $438 million in Adjusted EBITDA and $30 million in net income. While a COVID-related downturn was expected for the company in 2020, LTH has seen a strong rebound in 2021. The company has also invested in multiple lucrative partnerships, including an agreement with Apple to provide Apple Fitness+ to their members.

LTH recently enjoyed its IPO back in early October. The company has since reported that Q3 revenue was up 66.7% to $385 million and comparable center sales were up 58.7%. These results were achieved with nearly 20% of LTH’s centers still experiencing pandemic-related restrictions during the quarter. The stock is currently about 10% from its initial $18 IPO price.

Life Time Group Holdings, Inc. Price, Consensus and EPS Surprise

Life Time Group Holdings, Inc. Price, Consensus and EPS Surprise

Life Time Group Holdings, Inc. price-consensus-eps-surprise-chart | Life Time Group Holdings, Inc. Quote

On a personal note, I’ve been a Life Time member for many years and have been continuously impressed with their services. Having frequented several well-known gyms, I can definitively say that LTH’s luxurious fitness centers are some of the best in the business. The company’s handling of the pandemic and the procedures it implemented with regards to social distancing, cleanliness and safety were second to none.

The staff does an incredible job and I can tell that this is a well-run company. It will be interesting to see how the stock performs moving forward. LTH is scheduled to report earnings on January 27th, 2022.

More Stock News: This Is Bigger than the iPhone!

It could become the mother of all technological revolutions. Apple sold a mere 1 billion iPhones in 10 years but a new breakthrough is expected to generate more than 77 billion devices by 2025, creating a $1.3 trillion market.

Zacks has just released a Special Report that spotlights this fast-emerging phenomenon and 4 tickers for taking advantage of it. If you don’t buy now, you may kick yourself in 2022.

Click here for the 4 trades >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
DICK’S Sporting Goods, Inc. (DKS): Free Stock Analysis Report
 
lululemon athletica inc. (LULU): Free Stock Analysis Report
 
Nautilus Group, Inc. The (NLS): Free Stock Analysis Report
 
Peloton Interactive, Inc. (PTON): Free Stock Analysis Report
 
Life Time Group Holdings, Inc. (LTH): Get Free Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/398352


Titan Machinery (TITN) Dips More Than Broader Markets: What You Should Know

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Titan Machinery (TITN) closed the most recent trading day at $34.07, moving -0.82% from the previous trading session. This move lagged the S&P 500’s daily loss of 0.14%.

– Zacks

Coming into today, shares of the agriculture and construction equipment seller had gained 19.44% in the past month. In that same time, the Retail-Wholesale sector gained 3.83%, while the S&P 500 gained 5.04%.

Investors will be hoping for strength from Titan Machinery as it approaches its next earnings release, which is expected to be November 23, 2021. The company is expected to report EPS of $0.61, up 5.17% from the prior-year quarter. Our most recent consensus estimate is calling for quarterly revenue of $430.3 million, up 19.24% from the year-ago period.

Looking at the full year, our Zacks Consensus Estimates suggest analysts are expecting earnings of $2.13 per share and revenue of $1.68 billion. These totals would mark changes of +69.05% and +19.2%, respectively, from last year.

Any recent changes to analyst estimates for Titan Machinery should also be noted by investors. Recent revisions tend to reflect the latest near-term business trends. As a result, we can interpret positive estimate revisions as a good sign for the company’s business outlook.

Our research shows that these estimate changes are directly correlated with near-term stock prices. Investors can capitalize on this by using the Zacks Rank. This model considers these estimate changes and provides a simple, actionable rating system.

The Zacks Rank system ranges from #1 (Strong Buy) to #5 (Strong Sell). It has a remarkable, outside-audited track record of success, with #1 stocks delivering an average annual return of +25% since 1988. The Zacks Consensus EPS estimate remained stagnant within the past month. Titan Machinery is holding a Zacks Rank of #2 (Buy) right now.

Investors should also note Titan Machinery’s current valuation metrics, including its Forward P/E ratio of 16.17. This valuation marks a premium compared to its industry’s average Forward P/E of 7.04.

The Automotive – Retail and Whole Sales industry is part of the Retail-Wholesale sector. This group has a Zacks Industry Rank of 28, putting it in the top 12% of all 250+ industries.

The Zacks Industry Rank gauges the strength of our industry groups by measuring the average Zacks Rank of the individual stocks within the groups. Our research shows that the top 50% rated industries outperform the bottom half by a factor of 2 to 1.

To follow TITN in the coming trading sessions, be sure to utilize Zacks.com.

More Stock News: This Is Bigger than the iPhone!

It could become the mother of all technological revolutions. Apple sold a mere 1 billion iPhones in 10 years but a new breakthrough is expected to generate more than 77 billion devices by 2025, creating a $1.3 trillion market.

Zacks has just released a Special Report that spotlights this fast-emerging phenomenon and 4 tickers for taking advantage of it. If you don’t buy now, you may kick yourself in 2022.

Click here for the 4 trades >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Titan Machinery Inc. (TITN): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/398353


Delta Air Lines (DAL) Dips More Than Broader Markets: What You Should Know

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

In the latest trading session, Delta Air Lines (DAL) closed at $39.69, marking a -1.07% move from the previous day. This change lagged the S&P 500’s 0.14% loss on the day.

– Zacks

Heading into today, shares of the airline had lost 0.69% over the past month, lagging the Transportation sector’s gain of 3.51% and the S&P 500’s gain of 5.04% in that time.

Delta Air Lines will be looking to display strength as it nears its next earnings release. In that report, analysts expect Delta Air Lines to post earnings of -$0.18 per share. This would mark year-over-year growth of 92.89%. Our most recent consensus estimate is calling for quarterly revenue of $8.79 billion, up 121.25% from the year-ago period.

For the full year, our Zacks Consensus Estimates are projecting earnings of -$4.62 per share and revenue of $28.99 billion, which would represent changes of +57.06% and +69.6%, respectively, from the prior year.

Investors should also note any recent changes to analyst estimates for Delta Air Lines. These revisions help to show the ever-changing nature of near-term business trends. As a result, we can interpret positive estimate revisions as a good sign for the company’s business outlook.

Based on our research, we believe these estimate revisions are directly related to near-team stock moves. Investors can capitalize on this by using the Zacks Rank. This model considers these estimate changes and provides a simple, actionable rating system.

The Zacks Rank system, which ranges from #1 (Strong Buy) to #5 (Strong Sell), has an impressive outside-audited track record of outperformance, with #1 stocks generating an average annual return of +25% since 1988. Within the past 30 days, our consensus EPS projection remained stagnant. Delta Air Lines is currently sporting a Zacks Rank of #4 (Sell).

The Transportation – Airline industry is part of the Transportation sector. This industry currently has a Zacks Industry Rank of 230, which puts it in the bottom 10% of all 250+ industries.

The Zacks Industry Rank gauges the strength of our individual industry groups by measuring the average Zacks Rank of the individual stocks within the groups. Our research shows that the top 50% rated industries outperform the bottom half by a factor of 2 to 1.

You can find more information on all of these metrics, and much more, on Zacks.com.

More Stock News: This Is Bigger than the iPhone!

It could become the mother of all technological revolutions. Apple sold a mere 1 billion iPhones in 10 years but a new breakthrough is expected to generate more than 77 billion devices by 2025, creating a $1.3 trillion market.

Zacks has just released a Special Report that spotlights this fast-emerging phenomenon and 4 tickers for taking advantage of it. If you don’t buy now, you may kick yourself in 2022.

Click here for the 4 trades >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Delta Air Lines, Inc. (DAL): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/398354


Dick’s Sporting Goods (DKS) Dips More Than Broader Markets: What You Should Know

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Dick’s Sporting Goods (DKS) closed at $138.59 in the latest trading session, marking a -1.18% move from the prior day. This move lagged the S&P 500’s daily loss of 0.14%. Elsewhere, the Dow lost 0.75%, while the tech-heavy Nasdaq lost 0.07%.

– Zacks

Coming into today, shares of the sporting goods retailer had gained 13.15% in the past month. In that same time, the Retail-Wholesale sector gained 3.83%, while the S&P 500 gained 5.04%.

Wall Street will be looking for positivity from Dick’s Sporting Goods as it approaches its next earnings report date. This is expected to be November 23, 2021. On that day, Dick’s Sporting Goods is projected to report earnings of $1.88 per share, which would represent a year-over-year decline of 6.47%. Meanwhile, the Zacks Consensus Estimate for revenue is projecting net sales of $2.42 billion, up 0.43% from the year-ago period.

For the full year, our Zacks Consensus Estimates are projecting earnings of $12.91 per share and revenue of $11.69 billion, which would represent changes of +110.95% and +21.97%, respectively, from the prior year.

It is also important to note the recent changes to analyst estimates for Dick’s Sporting Goods. These revisions typically reflect the latest short-term business trends, which can change frequently. As a result, we can interpret positive estimate revisions as a good sign for the company’s business outlook.

Our research shows that these estimate changes are directly correlated with near-term stock prices. To benefit from this, we have developed the Zacks Rank, a proprietary model which takes these estimate changes into account and provides an actionable rating system.

The Zacks Rank system, which ranges from #1 (Strong Buy) to #5 (Strong Sell), has an impressive outside-audited track record of outperformance, with #1 stocks generating an average annual return of +25% since 1988. Over the past month, the Zacks Consensus EPS estimate has moved 0.22% higher. Dick’s Sporting Goods currently has a Zacks Rank of #3 (Hold).

Looking at its valuation, Dick’s Sporting Goods is holding a Forward P/E ratio of 10.86. For comparison, its industry has an average Forward P/E of 18.73, which means Dick’s Sporting Goods is trading at a discount to the group.

It is also worth noting that DKS currently has a PEG ratio of 0.85. The PEG ratio is similar to the widely-used P/E ratio, but this metric also takes the company’s expected earnings growth rate into account. Retail – Miscellaneous stocks are, on average, holding a PEG ratio of 1.13 based on yesterday’s closing prices.

The Retail – Miscellaneous industry is part of the Retail-Wholesale sector. This group has a Zacks Industry Rank of 106, putting it in the top 42% of all 250+ industries.

The Zacks Industry Rank gauges the strength of our individual industry groups by measuring the average Zacks Rank of the individual stocks within the groups. Our research shows that the top 50% rated industries outperform the bottom half by a factor of 2 to 1.

You can find more information on all of these metrics, and much more, on Zacks.com.

More Stock News: This Is Bigger than the iPhone!

It could become the mother of all technological revolutions. Apple sold a mere 1 billion iPhones in 10 years but a new breakthrough is expected to generate more than 77 billion devices by 2025, creating a $1.3 trillion market.

Zacks has just released a Special Report that spotlights this fast-emerging phenomenon and 4 tickers for taking advantage of it. If you don’t buy now, you may kick yourself in 2022.

Click here for the 4 trades >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
DICK’S Sporting Goods, Inc. (DKS): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/398355


TSMC (TSM) Gains As Market Dips: What You Should Know

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

TSMC (TSM) closed at $124.26 in the latest trading session, marking a +0.71% move from the prior day. This move outpaced the S&P 500’s daily loss of 0.14%. Elsewhere, the Dow lost 0.75%, while the tech-heavy Nasdaq lost 0.07%.

– Zacks

Coming into today, shares of the chip company had gained 6.11% in the past month. In that same time, the Computer and Technology sector gained 5.43%, while the S&P 500 gained 5.04%.

Wall Street will be looking for positivity from TSMC as it approaches its next earnings report date. On that day, TSMC is projected to report earnings of $1.15 per share, which would represent year-over-year growth of 18.56%. Meanwhile, the Zacks Consensus Estimate for revenue is projecting net sales of $16.1 billion, up 27.01% from the year-ago period.

For the full year, our Zacks Consensus Estimates are projecting earnings of $4.16 per share and revenue of $58.66 billion, which would represent changes of +22.71% and +28.92%, respectively, from the prior year.

It is also important to note the recent changes to analyst estimates for TSMC. These revisions typically reflect the latest short-term business trends, which can change frequently. As a result, we can interpret positive estimate revisions as a good sign for the company’s business outlook.

Our research shows that these estimate changes are directly correlated with near-term stock prices. To benefit from this, we have developed the Zacks Rank, a proprietary model which takes these estimate changes into account and provides an actionable rating system.

The Zacks Rank system, which ranges from #1 (Strong Buy) to #5 (Strong Sell), has an impressive outside-audited track record of outperformance, with #1 stocks generating an average annual return of +25% since 1988. Over the past month, the Zacks Consensus EPS estimate remained stagnant. TSMC currently has a Zacks Rank of #3 (Hold).

Looking at its valuation, TSMC is holding a Forward P/E ratio of 29.66. For comparison, its industry has an average Forward P/E of 29.66, which means TSMC is trading at a no noticeable deviation to the group.

It is also worth noting that TSM currently has a PEG ratio of 1.85. The PEG ratio is similar to the widely-used P/E ratio, but this metric also takes the company’s expected earnings growth rate into account. Semiconductor – Circuit Foundry stocks are, on average, holding a PEG ratio of 1.85 based on yesterday’s closing prices.

The Semiconductor – Circuit Foundry industry is part of the Computer and Technology sector. This group has a Zacks Industry Rank of 106, putting it in the top 42% of all 250+ industries.

The Zacks Industry Rank gauges the strength of our individual industry groups by measuring the average Zacks Rank of the individual stocks within the groups. Our research shows that the top 50% rated industries outperform the bottom half by a factor of 2 to 1.

You can find more information on all of these metrics, and much more, on Zacks.com.

More Stock News: This Is Bigger than the iPhone!

It could become the mother of all technological revolutions. Apple sold a mere 1 billion iPhones in 10 years but a new breakthrough is expected to generate more than 77 billion devices by 2025, creating a $1.3 trillion market.

Zacks has just released a Special Report that spotlights this fast-emerging phenomenon and 4 tickers for taking advantage of it. If you don’t buy now, you may kick yourself in 2022.

Click here for the 4 trades >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Taiwan Semiconductor Manufacturing Company Ltd. (TSM): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/398356


The Retail Sector Margin Squeeze

Most of the large retailers have been able to work through the supply-chain challenges and keep their shelves fully stoked. What this suggests is that when it comes to supply-chain management, size does matter.

– Zacks

That said, all of the big retailers had to spend more to keep shelves stocked, with freight expenses a major drag on margins and outlook. We saw this with Target TGT and Walmart WMT, and even the mighty Amazon AMZN had to deal with these issues. Both Walmart and Target exited Q3 with above-normal inventory on hand, as a way to handle the holidays efficiently.

We will discuss more details about Walmart and Target a little later, but let’s recap the Retail sector’s Q3 earnings season scorecard.

With results from 29 of the 35 retailers in the S&P 500 index already out, total earnings for these companies that have reported are up +8% on +10.8% higher revenues, with 86.2% beating EPS and revenue estimates. Net margins for this group are down 14 basis points from the year-earlier level, as a result of the aforementioned headwinds. This would follow the 150 basis point expansion in the preceding reporting cycle (2021 Q2).

For the S&P 500 index as a whole, Q3 net margins are up 230 basis points. The chart below put the Retail sector’s Q3 earnings and revenue growth rates in a historical context.

Zacks Investment ResearchImage Source: Zacks Investment Research

The comparison charts below put the sector’s Q3 EPS and revenue beats percentages in a historical context.

Zacks Investment ResearchImage Source: Zacks Investment Research

While the proportion of these companies beating Q3 EPS and revenue estimates is below what we had seen in the preceding period, the beats percentages are nevertheless tracking historical averages.

Getting back to the Walmart report, the stock was modestly down following the release even as it did an impressive job of navigating the supply-chain issue. Walmart’s U.S. comps were up +9.9% in Q3, with Walmart U.S. up +9.2% and Sam’s Club up +13.9%. Walmart’s Q3 gross margin of 25.3% was down 20 bps from the year-earlier level. Walmart exited Q3 with +11% more in inventory relative to the year-earlier level.

Walmart shares have lagged the broader market and Target this year, with the market concerned about the retail giant’s margins outlook in the face of inflationary and supply-chain issues. The stock is down -0.9% this year vs. +26.4% gain for the S&P 500 index and Target’s +42.4% gain.

The market loves Target’s digital offering that seamlessly integrates the online into the company’s brick-and-mortar footprint. Target enjoyed strong growth, with comps up +12.7%, though gross margins came in weaker than expected on the back of higher freight and supply-chain expenses. Target exited the quarter with +18% more inventory than the year-earlier, effectively guaranteeing stocked shelves during holidays.

Q3 Earnings Season Scorecard

Including all the results that came out through Friday, November 19th, we now have Q3 results from 475 S&P 500 members or 95% of the index’s total membership. Total earnings (or aggregate net income) for these companies are up +41.9% from the same period last year on +17.7% higher revenues, with 79.7% beating EPS estimates and 74.5% beating revenue estimates.

The proportion of these companies beating both EPS and revenue estimates is 62.7%, the blended beats percentage.

Earnings and revenue growth has come down in the ongoing Q3 earnings season from the first-half’s break-neck speed, but it is still very high.

You can see this in the comparison charts below that shows the Q3 earnings and revenue growth for the 475 S&P 500 members that have reported results through Friday, November 19th.

Zacks Investment ResearchImage Source: Zacks Investment Research

The unfavorable comparison to the first half of the year isn’t only with respect to the growth rates, as the proportion of these companies beating EPS and revenue estimates is also tracking below what we had seen from this same group of companies earlier in the year, as you can see in the charts below.

Zacks Investment ResearchImage Source: Zacks Investment Research

The decelerated growth pace notwithstanding, aggregate Q3 earnings for the S&P 500 index are on track to reach a new all-time quarterly record, surpassing the record set in the preceding quarter. You can see this in the chart below that shows the 2021 Q3 aggregate total at $477.8 billion.

Zacks Investment ResearchImage Source: Zacks Investment Research

The one notable disconcerting development this earnings season is on the revisions front, with estimates for the current period (2021 Q4) modestly turning down in recent days after inching up at the start of the reporting cycle.

Zacks Investment ResearchImage Source: Zacks Investment Research

This is in contrast to the persistent positive revisions trend that we have been seeing since the Summer of 2020. While the magnitude of negative revisions to Q4 estimates is fairly modest in the aggregate, it is relatively more pronounced for the Retail and Transportation sectors.

Estimates for full-year 2022 are still going up, though the revisions trend has notably plateaued since the start of October. In fact, had it not been for the positive revisions to estimates for the Energy sector, estimates for the index as a whole would have actually come down since the start of Q3.

The chart below shows how aggregate estimates for full-year 2022 have evolved since the start of the year.

Zacks Investment ResearchImage Source: Zacks Investment Research

Since the start of October, aggregate estimates have come down for 10 of the 16 Zacks sectors and gone up for four. The four sectors experiencing positive estimate revisions since the start of October include Energy, Autos, Basic Materials and Medical.

Positive revisions to Energy sector earnings estimates have been the most pronounced and have helped offset negative revisions to a host of other sectors. The Energy sector is expected to have the highest earnings in 2022 since 2012.

Expectations for Q3 & Beyond

Looking at the quarter as a whole, combining the actual results that have come out with estimates for the still-to-come companies, total Q3 earnings for the S&P 500 index are expected to be up +40.3% from the same period last year on +17.2% higher revenues.

The chart below presents the earnings and revenue growth picture on a quarterly basis, with expectations for 2021 Q3 contrasted with the actual growth achieved over the preceding four quarters and estimates for the following three.

Zacks Investment ResearchImage Source: Zacks Investment Research

The chart below shows the comparable picture on an annual basis.

Zacks Investment ResearchImage Source: Zacks Investment Research

For a detailed look at the overall earnings picture, including expectations for the coming periods, please check out our weekly Earnings Trends report >>>>Breaking Down the Outlook for Margins 

More Stock News: This Is Bigger than the iPhone!

It could become the mother of all technological revolutions. Apple sold a mere 1 billion iPhones in 10 years but a new breakthrough is expected to generate more than 77 billion devices by 2025, creating a $1.3 trillion market.

Zacks has just released a Special Report that spotlights this fast-emerging phenomenon and 4 tickers for taking advantage of it. If you don’t buy now, you may kick yourself in 2022.

Click here for the 4 trades >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Amazon.com, Inc. (AMZN): Free Stock Analysis Report
 
Target Corporation (TGT): Free Stock Analysis Report
 
Walmart Inc. (WMT): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/398357


How To Play The Crypto Correction

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
[embedded content]

The digital currency space is contracting after reaching nearly $3 trillion in total market value last week. It has officially entered correction territory (10% to 20% decline from recent highs). Nothing is surprising about a 10% pullback in this highly volatile market, but this current correction is the most significant digital currencies have seen since September and could mean that more pain is to come.

– Zacks

Cryptocurrencies have been the best performing asset class of 2021 by a mile as agile market participants prepare for the rapidly evolving future of finance. The total crypto market cap started the year under $800 billion. However, a tidal wave of fresh capital from individuals and deep-pocket money managers alike pushed this mystifying market’s value up 240% year-to-date (despite the recent tumble).

Traders are now pulling profits from their biggest winners, catalyzing a bearish domino effect that could easily pull this market down another 10% before a bottom is called. I have no doubt that investor & traders will buy this market right back up once the momentum shifts back towards the upside. My trades will be queuing off Fibonacci-extension levels (downside targets) in key coins like Ethereum ETH and Bitcoin BTC for my entry points (not implying that I will be buying either just using for technical reasons).

The coin that I am looking to buy on this crypto dip is Solana SOL, which is positioned to replace Ethereum as the most useful digital asset. Solana is functionally the same as Ethereum but supports transaction speeds over 1,000x as fast and fees that are 60,000x lower.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Renesola Ltd. (SOL): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/397872