You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
America’s Car-Mart (CRMT) came out with quarterly earnings of $3.33 per share, missing the Zacks Consensus Estimate of $3.41 per share. This compares to earnings of $3.05 per share a year ago. These figures are adjusted for non-recurring items.
– Zacks
This quarterly report represents an earnings surprise of -2.35%. A quarter ago, it was expected that this auto retailer would post earnings of $3.55 per share when it actually produced earnings of $3.57, delivering a surprise of 0.56%.
Over the last four quarters, the company has surpassed consensus EPS estimates three times.
America’s Car-Mart, which belongs to the Zacks Automotive – Retail and Whole Sales industry, posted revenues of $288.3 million for the quarter ended October 2021, surpassing the Zacks Consensus Estimate by 2.03%. This compares to year-ago revenues of $223.36 million. The company has topped consensus revenue estimates four times over the last four quarters.
The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.
America’s Car-Mart shares have added about 15.1% since the beginning of the year versus the S&P 500’s gain of 25.2%.
What’s Next for America’s Car-Mart?
While America’s Car-Mart has underperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?
There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.
Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.
Ahead of this earnings release, the estimate revisions trend for America’s Car-Mart was mixed. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #3 (Hold) for the stock. So, the shares are expected to perform in line with the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $3.13 on $273.24 million in revenues for the coming quarter and $13.31 on $1.13 billion in revenues for the current fiscal year.
Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Automotive – Retail and Whole Sales is currently in the top 8% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.
Zacks’ Top Picks to Cash in on Artificial Intelligence
This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Copa Holdings (CPA) Q3 Earnings and Revenues Beat Estimates
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
Copa Holdings (CPA) came out with quarterly earnings of $0.70 per share, beating the Zacks Consensus Estimate of a loss of $0.17 per share. This compares to loss of $2.86 per share a year ago. These figures are adjusted for non-recurring items.
– Zacks
This quarterly report represents an earnings surprise of 511.76%. A quarter ago, it was expected that this holding company for Panama’s national airline would post a loss of $1.08 per share when it actually produced a loss of $0.38, delivering a surprise of 64.81%.
Over the last four quarters, the company has surpassed consensus EPS estimates three times.
Copa Holdings, which belongs to the Zacks Transportation – Airline industry, posted revenues of $445 million for the quarter ended September 2021, surpassing the Zacks Consensus Estimate by 5.73%. This compares to year-ago revenues of $32.38 million. The company has topped consensus revenue estimates three times over the last four quarters.
The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.
Copa Holdings shares have lost about 4.2% since the beginning of the year versus the S&P 500’s gain of 25.2%.
What’s Next for Copa Holdings?
While Copa Holdings has underperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?
There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.
Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.
Ahead of this earnings release, the estimate revisions trend for Copa Holdings was mixed. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #3 (Hold) for the stock. So, the shares are expected to perform in line with the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $0.45 on $508.83 million in revenues for the coming quarter and -$2.37 on $1.41 billion in revenues for the current fiscal year.
Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Transportation – Airline is currently in the bottom 9% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.
Zacks’ Top Picks to Cash in on Artificial Intelligence
This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
I3 Verticals (IIIV) Q4 Earnings and Revenues Beat Estimates
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
I3 Verticals (IIIV) came out with quarterly earnings of $0.33 per share, beating the Zacks Consensus Estimate of $0.29 per share. This compares to earnings of $0.20 per share a year ago. These figures are adjusted for non-recurring items.
– Zacks
This quarterly report represents an earnings surprise of 13.79%. A quarter ago, it was expected that this company would post earnings of $0.28 per share when it actually produced earnings of $0.26, delivering a surprise of -7.14%.
Over the last four quarters, the company has surpassed consensus EPS estimates two times.
i3 Verticals, which belongs to the Zacks Internet – Software industry, posted revenues of $67.19 million for the quarter ended September 2021, surpassing the Zacks Consensus Estimate by 4.31%. This compares to year-ago revenues of $38.43 million. The company has topped consensus revenue estimates four times over the last four quarters.
The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.
I3 Verticals shares have lost about 30.9% since the beginning of the year versus the S&P 500’s gain of 25.2%.
What’s Next for i3 Verticals?
While i3 Verticals has underperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?
There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.
Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.
Ahead of this earnings release, the estimate revisions trend for i3 Verticals was unfavorable. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #4 (Sell) for the stock. So, the shares are expected to underperform the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $0.31 on $62.13 million in revenues for the coming quarter and $1.22 on $266.25 million in revenues for the current fiscal year.
Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Internet – Software is currently in the bottom 27% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.
Zacks’ Top Picks to Cash in on Artificial Intelligence
This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Will ETFs Suffer as US Consumer Sentiment Slips in November?
U.S. consumers have started feeling the pinch of rising inflation levels. The latest disappointing preliminary consumer sentiment readings for early November that have slipped to the lowest level in a decade highlight the same. The University of Michigan’s preliminary consumer sentiment declined to 66.8 in early November from 71.7 last month. The metric lagged the market forecast of 72.4, per the Reuters survey on economists.
– Zacks
The disappointing consumer sentiment reading might affect the consumer discretionary sector, which attracts a major portion of consumer spending amid rising inflation levels. Certain ETFs that can feel the impact are The Consumer Discretionary Select Sector SPDR Fund (XLY), Vanguard Consumer Discretionary ETF (VCR), First Trust Consumer Discretionary AlphaDEX Fund (FXD) and Fidelity MSCI Consumer Discretionary Index ETF (FDIS).
Going on, the measure of current economic conditions dipped to 73.2 in November –the lowest level since 2011 — according to a Bloomberg article. In November, a gauge of consumer expectations slid to 62.8, appearing to be the weakest since 2013.
One-year inflation is expected to rise 4.9% in November (the highest since 2008). The survey’s five-to-10 year inflation outlook remained flat at 2.9% in November, as stated in a Bloomberg article.
In this regard, Richard Curtin, director of the survey, said that “an escalating inflation rate and the growing belief among consumers that no effective policies have yet been developed to reduce the damage from surging inflation.” This was reported in a Bloomberg article. Curtin also said that “One in four consumers cited inflationary reductions in their living standards in November, with lower income and older consumers voicing the greatest impact,” per the same article as mentioned above.
Consumers seem disturbed about the rising prices of homes, vehicles, food and household durables. The Michigan survey has also highlighted that the buying conditions for household goods have declined to the second-lowest level since the recording of data began in 1978. The metric came in at a reading of 78 (per a Bloomberg article).
Present U.S. Economic Scenario
Investors have started worrying about the hot inflation data releases amid the Fed’s stance of calling inflation levels ‘transitory’. Per the latest Labor Department report, the Consumer Price Index (CPI) in October rose 6.2% year over year compared to the Dow Jones estimate of a 5.9% rise, per a CNBC article. The metric came in at the highest level since December 1990 and covers a basket of products ranging from gasoline and health care to groceries and rents. It also increased 0.9% for the month, surpassing the 0.6% Dow Jones estimate. The soaring food, used vehicles and energy prices might be primarily responsible for the rising inflation levels.
According to the Federal Reserve, a major part of the inflation has been triggered by the pandemic-driven supply-demand imbalance, which might get resolved in a few months (per a CNBC article).
However, the impressive third-quarter earnings results have been keeping investors busy. The earnings results have also eased investors’ worries surrounding the rising supply-chain disturbances eroding corporate profit margins. The upside in the market has also been driven by the much-anticipated announcements from the Federal Reserve. The central bank has informed about its plan to initiate the tapering of bond purchases “later this month” (according to a CNBC article).
In another positive development, the U.S. jobs report for November seems very impressive. The nonfarm payrolls rose by 531,000 in October, surpassing the estimate of 450,000, per a CNBC article. Also, beating expectations, the unemployment rate declined to 4.6%, hitting a new pandemic low level (according to a CNBC article).
Wall Street has another reason to cheer as the U.S. House of Representatives has passed the more than $1-trillion infrastructure bill on Nov 5. The bill has now moved to President Biden for his signature. The legislation was approved in a 228-206 vote.
Going on, the Atlanta Fed stated that the U.S. economy will grow 8.2% in fourth-quarter 2021 in his latest forecasts on Nov 10 (per the verified sources). This signals an improvement from the previous expectation of 6.6% on Oct 29. Heading into the holiday season, given the reopening of domestic and international borders for traveling, we are enthusiastic about U.S. economic growth.
ETFs That Might Suffer
Here we discuss in detail the four most popular funds that target the broader consumer discretionary sector (see all Consumer Discretionary ETFs):
The Consumer Discretionary Select Sector SPDR FundXLY
The Consumer Discretionary Select Sector SPDR Fund is the largest and the most popular product in the consumer discretionary space, with AUM of $23.28 billion. XLY tracks the Consumer Discretionary Select Sector Index.
The Consumer Discretionary Select Sector SPDR Fund charges an expense ratio of 0.12%. XLY carries a Zacks ETF Rank #2 (Buy), with a Medium-risk outlook. Also, The Consumer Discretionary Select Sector SPDR Fund trades in three-month average volume of about 5.2 million shares (read: ETFs in Trouble as Tesla Takes the Hit of Musk’s Twitter Poll).
Vanguard Consumer Discretionary ETF currently follows the MSCI US Investable Market Consumer Discretionary 25/50 Index.
Vanguard Consumer Discretionary ETF has an AUM of $7.44 billion and charges an expense ratio of 0.10%. VCR carries a Zacks ETF Rank #1 (Strong Buy), with a Medium-risk outlook. Also, Vanguard Consumer Discretionary ETF trades in three-month average volume of about 73,000 shares (read: Consumer Discretionary ETFs to Gain as COVID-19 Situation Improves).
First Trust Consumer Discretionary AlphaDEX Fund FXD
First Trust Consumer Discretionary AlphaDEX Fund tracks the StrataQuant Consumer Discretionary Index, which employs the AlphaDEX stock-selection methodology to select stocks from the Russell 1000 Index.
First Trust Consumer Discretionary AlphaDEX Fund has AUM of $2.02 billion. FXD charges 63 bps in annual fees and has a Zacks ETF Rank #3 (Hold), with a Medium-risk outlook. Also, First Trust Consumer Discretionary AlphaDEX Fund trades in three-month average volume of about 100,000 shares.
Fidelity MSCI Consumer Discretionary Index ETF FDIS
Fidelity MSCI Consumer Discretionary Index ETF tracks the MSCI USA IMI Consumer Discretionary Index.
Fidelity MSCI Consumer Discretionary Index ETF has amassed $1.78 billion in its asset base. FDIS charges 8 bps in annual fees from investors and carries a Zacks ETF Rank #2, with a Medium-risk outlook. Fidelity MSCI Consumer Discretionary Index ETF trades in three-month average volume of about 99,000 shares.
Want key ETF info delivered straight to your inbox?
Zacks’ free Fund Newsletter will brief you on top news and analysis, as well as top-performing ETFs, each week.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Vivint Smart Home (VVNT) Reports Q3 Loss, Tops Revenue Estimates
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
Vivint Smart Home (VVNT) came out with a quarterly loss of $0.52 per share versus the Zacks Consensus Estimate of a loss of $0.36. This compares to loss of $0.58 per share a year ago. These figures are adjusted for non-recurring items.
– Zacks
This quarterly report represents an earnings surprise of -44.44%. A quarter ago, it was expected that this company would post a loss of $0.44 per share when it actually produced a loss of $0.38, delivering a surprise of 13.64%.
Over the last four quarters, the company has surpassed consensus EPS estimates just once.
Vivint Smart Home, which belongs to the Zacks Retail – Consumer Electronics industry, posted revenues of $386.71 million for the quarter ended September 2021, surpassing the Zacks Consensus Estimate by 8.86%. This compares to year-ago revenues of $318.96 million. The company has topped consensus revenue estimates four times over the last four quarters.
The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.
Vivint Smart Home shares have lost about 53% since the beginning of the year versus the S&P 500’s gain of 24.7%.
What’s Next for Vivint Smart Home?
While Vivint Smart Home has underperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?
There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.
Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.
Ahead of this earnings release, the estimate revisions trend for Vivint Smart Home was mixed. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #3 (Hold) for the stock. So, the shares are expected to perform in line with the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is -$0.33 on $365.77 million in revenues for the coming quarter and -$1.50 on $1.42 billion in revenues for the current fiscal year.
Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Retail – Consumer Electronics is currently in the top 14% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.
5 Stocks Set to Double
Each was handpicked by a Zacks expert as the #1 favorite stock to gain +100% or more in 2021. Previous recommendations have soared +143.0%, +175.9%, +498.3% and +673.0%.
Most of the stocks in this report are flying under Wall Street radar, which provides a great opportunity to get in on the ground floor.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
AMMO, Inc. (POWW) Q2 Earnings and Revenues Top Estimates
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
AMMO, Inc. (POWW) came out with quarterly earnings of $0.11 per share, beating the Zacks Consensus Estimate of $0.10 per share. This compares to loss of $0.05 per share a year ago. These figures are adjusted for non-recurring items.
– Zacks
This quarterly report represents an earnings surprise of 10%. A quarter ago, it was expected that this company would post earnings of $0.06 per share when it actually produced earnings of $0.13, delivering a surprise of 116.67%.
Over the last four quarters, the company has surpassed consensus EPS estimates three times.
AMMO, Inc.Which belongs to the Zacks Leisure and Recreation Products industry, posted revenues of $61 million for the quarter ended September 2021, surpassing the Zacks Consensus Estimate by 10.91%. This compares to year-ago revenues of $12.01 million. The company has topped consensus revenue estimates three times over the last four quarters.
The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.
AMMO, Inc. Shares have added about 115.8% since the beginning of the year versus the S&P 500’s gain of 24.7%.
What’s Next for AMMO, Inc.
While AMMO, Inc. Has outperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?
There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.
Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.
Ahead of this earnings release, the estimate revisions trend for AMMO, Inc. Was mixed. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #3 (Hold) for the stock. So, the shares are expected to perform in line with the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $0.12 on $60.1 million in revenues for the coming quarter and $0.42 on $219.8 million in revenues for the current fiscal year.
Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Leisure and Recreation Products is currently in the top 26% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.
5 Stocks Set to Double
Each was handpicked by a Zacks expert as the #1 favorite stock to gain +100% or more in 2021. Previous recommendations have soared +143.0%, +175.9%, +498.3% and +673.0%.
Most of the stocks in this report are flying under Wall Street radar, which provides a great opportunity to get in on the ground floor.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
10 Top Penny Stocks To Watch With Potential Biotech Catalysts This Week
Last week was mixed for the penny stocks and higher-priced ones alike. While there were plenty of trends to follow, some continued gaining steam heading into the middle of November. Sure, you’ve got things like metaverse stocks, short squeeze penny stocks, and your typical low float stocks to watch. Heading into this week, we’ll follow these trends, but you also can’t ignore traditional, industry trends including what’s going on in biotech specifically.
PennyStocks.com – PennyStocks
Why biotech? This is one of the “classic” industries fueled by speculation. Suppose you take a look at some of the biggest moving penny stocks in the last ten months. The vast majority were from companies exposed to health, wellness, medical devices, and the like. So does this mean all penny stocks with exposure to biotech end up breaking out big? No, however, since this industry is full of potential catalysts beyond traditional things like earnings. Phase trial updates, interim study details, and even industry presentations can become a big focus for traders and investors alike.
Today we’ll look at 10 penny stocks to watch this week and into the rest of this month that have potential catalysts to pay attention to. Thanks to significant updates last week from companies like Johnson & Johnson (NYSE:JNJ), Biogen (NASDAQ:BIIB), and other leading biotechs, eyes are on this sector once again heading into Monday. With that, here are 10 to watch and some dates to know right now.
As with all penny stocks on this list, CymaBay is developing unique treatments for unmet needs. In this case, the company specializes in therapies for liver and other chronic diseases. Its lead candidate, seladelpar, is its treatment for people with primary biliary cholangitis (PBC). Seladelpar has received breakthrough therapy designation (U.S. FDA), PRIority MEdicines status (European Medicines Agency), and orphan drug status (the U.S. and Europe).
What To Watch With CBAY Stock This Week
This week CBAY stock kicks of a busy one for biotech stocks. It will host a Key Opinion Leader webinar on seladelpar for PBR after the close on November 15, at 4:30 pm EST. This latest presentation comes a few days after CymaBay reported Q3 results and a corporate update last week.
Summing up the company’s quarterly progress, Sujal Shah, President, and CEO of CymaBay, said, “We now have over 100 sites activated across over 20 countries in our global registration study, RESPONSE, and expect these efforts to continue and ultimately drive the completion of enrollment in the first half of 2022. We are excited to also share additional data from our prior studies in PBC at The Liver Meeting(R) 2021 that demonstrate improved benefit of seladelpar between one to two years of treatment and differentiation from other existing treatments in a population of patients with more advanced disease.”
Last week, analysts at Raymond James also updated some of their outlook on the company. The firm maintained a Strong Buy on the stock and boosted its price target from $12 to $14.
Peny Stocks To Watch On November 15:
PhaseBio Pharmaceuticals Inc.(NASDAQ:PHAS)
This next company specializes in treatment development for cardiopulmonary diseases. Its lead product candidate, bentracimab, is in development as an antiplatelet therapy in significant bleeding and urgent surgery situations. Bentracimab has already received Breakthrough Therapy Designation from the FDA. Earlier this month, PhaseBio completed a Phase 2b trial in which bentracimab was investigated in healthy, older, and elderly subjects on dual antiplatelet therapy of ticagrelor and low-dose aspirin. Results demonstrated that all active treatment arms in both the Phase 2a and Phase 2b trials achieved immediate and sustained reversal of the antiplatelet effects of ticagrelor and was generally well-tolerated.
What To Watch With PHAS Stock This Week
This week PhaseBio will be in focus as it has a few things happening, both on November 15. First, its REVERSE-IT pivotal Phase 3 trial with bentracimab was accepted for presentation in a virtual Late-Breaking Science session at the American Heart Association Scientific Sessions 2021. The company will also host an investor call on November 15 at 12:30 p.m. ET to discuss these results.
InflaRx (NASDAQ:IFRX)
While some companies will be in focus ahead of key data, others like InflaRx have other things to keep track of. The company specializes in therapies addressing inflammation. Its anti-C5a technology is an inflammatory mediator targeting a broad range of autoimmune and other inflammatory diseases.
Late last month, InflaRx announced s positive data from the third cohort of patients in the Phase IIa open-label study with vilobelimab in Pyoderma Gangraenosum (PG). This helped send the stock higher heading into November. Dr. Korinna Pilz, Chief Clinical Development Officer of InflaRx, explained, “There is a need for better treatment options for this painful and debilitating condition. With the good safety profile and promising efficacy results we have seen in this trial, we will seek FDA guidance on next steps towards a pivotal program.”
Analysts at Raymond James responded in kind with an upgraded rating from Buy to Outperform and a price target set at $14.
What To Watch With IFRX Stock This Week
This week the company presents t a corporate overview at the H.C. Wainwright 7th Annual Israel Conference. If IFRX stock is on your list, make sure to keep November 15 in mind. InflaRx’s presentation begins at 8 AM EST.
Penny Stocks To Watch On November 16:
Seelos Therapeutics Inc.(NASDAQ:SEEL)
One of the biotech penny stocks we’ve followed this year is Seelos Therapeutics. It has gone through a fair share of ups and downs. But thanks to a growing interest in psychedelics and medical breakthroughs for neurological disease treatments, Seelos remains one of the penny stocks to watch. It’s also one of the top 10 holdings in the Horizons Psychedelic Stock Index ETF.
Seelos has a robust pipeline of treatment candidates addressing conditions including Acute Suicidal Ideation and Behavior in Major Depressive Disorder or Post-Traumatic Stress Disorder, Amyotrophic lateral sclerosis, Spinocerebellar ataxia, Sanfilippo syndrome, and Parkinson’s disease, among others.
What To Watch With SEEL Stock This Week
This week Seelos will participate in the Guggenheim Healthcare Talks, Idea Forum, 3rd Annual Neuro/Immunology Day on November 16. This presentation is one of several upcoming events that include Seelos. Later this month, Seelos will attend the 4th Annual ALS ONE Research Symposium, presenting details on its SLS-005 treatment candidate, November 30. The company will also participate in Benchmark’s Discovery One on One Investor Conference on December 2.
Penny Stocks To Watch On November 17:
ASLAN Pharmaceuticals Limited (NASDAQ:ASLN)
Like Seelos, ASLAN could be in focus later this week thanks to participation at an industry conference. The company has recently focused on furthering its ASLAN004 platform, ASLAN’s treatment candidate for atopic dermatitis. Earlier this year, the company reported positive top-line results from the double-blind placebo-controlled MAD trial of ASLAN004. It also achieved a “statistically significant improvement versus placebo” in the Intent to Treat population. With the first patient enrolment in the global Phase 2b trial of ASLAN004 expected this quarter, there’s plenty to watch for when it comes to ASLAN.
Other than ASLAN004, the company also plans to advance its ASLAN003 into clinical trials early next year. This is ASLAN’s candidate for treating n inflammatory bowel disease.
What To Watch With ASLN Stock This Week
This week CEO Dr. Carl Firth will participate at the Jefferies London Healthcare Conference on November 17. If ASLN stock is on your list, make sure to keep this date in mind.
Penny Stocks To Watch On November 18:
Corbus Pharmaceuticals Holdings Inc.(NASDAQ:CRBP)
Heading into this week, Corbus Pharmaceuticals is already a likely focus, thanks to last week’s earnings update. The company reported year-over-year EPS growth posting a loss per share of 2 cents. This was significantly better than 2020’s Q3 EPS loss of 43 cents. The immunology company also discussed its execution strategy thanks to this more robust performance. This strategy includes advancing its Lenabasum, which is expected to have Phase 2 topline data in treating lupus patients reported this quarter. The company said it’s also working on gaining clarity from the FDA on the potential path forward in its dermatomyositis program.
What To Watch With CRBP Stock This Week
This week, Corbus could be in the spotlight, as is the case with the following few penny stocks on this list, thanks to the Jefferies Conference. Similar to ASLAN, the company presents this week during the latter half of the conference. If CRBP stock is on your radar right now, keep November 18 in mind.
Concert Pharmaceuticals Inc (NASDAQ:CNCE)
Earlier this month, shares of CNCE stock were red hot. The big move came after Concert Pharmaceuticals announced that it agreed with BVF Partners L.P. and RA Capital Management to raise gross proceeds of $65 million. Furthermore, Concert said it could receive an additional $103 million upon the entire exercise of warrants issued in connection with the agreement.
Concert’s lead treatment, CTP-543, is in development for treating alopecia areata. A Phase 3 THRIVE-AA1 trial and Phase 3 THRIVE-AA2 trial are fully enrolled with topline data expected next year. So far, previous data has shown CTP-543 to have meaningful results. In the company’s corporate update last week, CEO Tung, Ph.D., explained, “We continue to believe that CTP-543, with its Breakthrough Therapy designation, has the potential to be a best-in-class compound to treat this challenging autoimmune disease and hope to make it available to patients as soon as possible.”
What To Watch With CNCE Stock This Week
Like others on this list of penny stocks, Concert will participate in the Jefferies London Healthcare Conference. This will follow on the heels of analyst action last week, which saw JMP Securities maintain its Market Outperform rating but cut its $17 price target to $10.
Verastem Inc.(NASDAQ:VSTM)
Specializing in cancer treatments, Verastem Oncology has been on the move over the last few sessions. In addition, if you look at the year-to-date trend, VSTM stock has maintained a steady uptrend in price as well. Since the start of 2021, the penny stock has climbed more than 40% so far.
Verastem’s VS-6766 has been one of the core focal points of the company. This is its candidate for blocking against tumor growth and proliferation. It’s currently in combination trials with Amgen’s (NASDAQ:AMGN) LUMAKRAS™ for non-small cell lung cancer patients as well as with Verastem’s defactinib in ovarian cancer.
What To Watch With VSTM Stock This Week
The Jefferies Conference is in the spotlight for Verastem this week. The company presents on November 18. So if VSTM stock is on your list, make sure to keep that in mind as a critical date heading into the second half of the week.
Penny Stocks To Watch On November 19:
Dermata Therapeutics Inc.(NASDAQ:DRMA)
Rounding out the week, Dermata Therapeutics has an upcoming presentation to keep an eye on. The company develops treatments for medical and aesthetic skin conditions and has been in and out of the retail trading spotlight since its IPO on the Nasdaq in August. Most of the recent focus has been on Dermata’s skin inflammation treatment, DMT310. It targets different conditions, including acne, psoriasis, and rosacea.
Recent Phase 1b results released last month demonstrated potential in the treatment. According to management, “DMT310 appears to be safe and well-tolerated by psoriasis patients, and that DMT310 demonstrated efficacy improvements in PGA, PASI, and pruritis scores for the target psoriatic lesion.”
CEO Gerry Proehl said that “Based upon the improvements witnessed across all three of our exploratory endpoints, combined with the tolerability profile observed and the continued need for safe and effective topical products for the treatment of psoriasis, we plan to continue investigation of DMT310 in psoriasis.”
What To Watch With DRMA Stock This Week
This week DRMA stock could be in focus on Friday. The company presents efficacy and safety results for its Phase 1b proof-of-concept study evaluating DMT410, its treatment for multiple aesthetic skin conditions. If Dermata is on your list right now, the presentation at the American Society for Dermatologic Surgery begins at 8:30 AM CT.
Peny Stocks To Watch In Q4:
MEI Pharma Inc.(NASDAQ: MEIP)
While this week doesn’t explicitly have a set date for watching MEI Pharma, previous updates suggest that this quarter could be important for the company. MEI is advancing cancer therapy treatments. Earlier this month, the company and Kyowa Kirin announced that the FDA granted orphan drug designation to zandelisib. It is an investigational cancer treatment for patients with B-cell malignancies, which the two companies entered into a global license agreement in 2020 to develop and commercialize.
This latest designation has brought some attention to the company in November. In particular, the ODD is for zandelisib as a potential therapy in follicular lymphoma. There’s currently a TIDAL study evaluating the treatment for this condition well as marginal zone lymphomas.
What To Watch With MEIP Stock This Quarter
In September, the company commented on this TIDAL study. MEI expects to report top-line data from the potentially registrational Phase 2 TIDAL study by the end of the calendar year. While no further details have emerged, this week marks the halfway point for Q4.
Biotech Penny Stocks To Watch
Heading into the week, these are just a handful of penny stocks to watch with potential catalysts. Understand, however, that just because there are dates to make a note of, that doesn’t guarantee that any potential catalysts will be bullish (or bearish, for that matter). However, if you’re putting your watch list together and some of these names are on it, these events could be one of the reasons behind recent attention in the stock market this month.
https://www.entrepreneur.com/article/397132
Buy These Growth-Focused Stocks Before Earnings and Hold for Years?
Stocks bounced back in the last two sessions after the market finally snapped its winning streak during the week of November 8. Wall Street took profits after a month-plus rally sent all three major U.S. indexes to new records to start the second month of the fourth quarter.
– Zacks
Many have pointed to continuing inflation, and rightfully so after it hit a 30-year high in October. Investors are now left to decide if the hot CPI data will force the Fed to start lifting rates sooner than projected.
The central bank has started to taper its bond-buying program and it plans to conclude its stimulus-focused purchases by June, with it set to keep it core interest rate at its current rock-bottom levels at least until then.
But the market’s quick rebound could mean Wall Street remains sanguine even in the face of rising prices, persistent supply chain bottlenecks, and a struggle to fill open jobs.
It’s worth pointing out that the current surge in prices have yet to show up in the S&P 500 margins outlook for FY22 or FY23, even though they are impacting things in the near-term (also read: What’s Going on with Earnings in Q4 and Beyond).
Uncertainty and headwinds remain, but investors likely want to stay on the hunt for strong stocks, especially if they are long-term buyers. Today, we explore a few new-age retailers trading well below their highs heading into their upcoming earnings reports. The stocks also happen to trade between $20 to $35 a share…
Traeger helped pioneer the wood pellet grill that it calls a “versatile and easy to use outdoor cooking system.” The company’s pellet grills use all-natural hardwood fuel and aim to provide 6-in-1 versatility in order to grill, smoke, bake, roast, braise and barbecue. Traeger has caught fire as part of a wave of new-age, high-end brands popular among a younger generation of consumers.
COOK went public at the end of July and climbed nearly 25% on its debut as Wall Street continued to jump on IPOs. Traeger’s first quarter as a public firm saw it post 39% revenue growth, with grills up 40%, consumables 28% higher, while accessories surged 65%. It did face earnings pressure amid supply chain setbacks, but its adjusted EPS of $0.15 a share easily topped our $0.04 estimate.
Zacks estimates call for COOK’s fiscal 2021 revenue to climb 40% to $764.6 million and then jump over 25% higher in FY22 to start closing in on $1 billion in sales ($958.7 million). Meanwhile, it is projected to post adjusted full year earnings of $0.56 a share this year and then see its EPS pop 35% to $0.76 in 2022.
Traeger executives believe it has the “potential to deliver approximately 20% annual revenue growth and 20% adjusted EBITDA margins” over the long term as it continues to expand. These plans include its newly launched (Nov. 2) Traeger Provisions meal-kit style food delivery service to help make a variety of meals on the grill.
COOK has fallen over 35% from its early August highs and is currently trading just under $20 a share. Yet, its Zacks consensus price target of $31.57 a share marks over 50% upside. Traeger lands a Zacks Rank #3 (Hold) heading into Q3 financial release on Monday, November 15. And seven of the eight brokerage recommendations Zacks has are “Strong Buys,” with the other at a “Buy.”
Sonos is a home audio firm that specializes in wireless and multi-room sound systems. It competes against Bose and others in the higher-end home speaker space. The firm sells a range of sleek, connected speakers, subwoofers, soundbars for TVs, and more, with packages that run up to nearly $2,000. Earlier this year, Sonos entered the popular portable smart speaker space with its $179 mass-market Roam speaker.
The company has benefited from the larger shift to modern, connected devices and it’s poised to gain as more people spend on home-based upgrades. The firm is also boosted its non-speaker space, with an ad-free streaming tier of its music service dubbed Sonos Radio HD. The offering costs $7.99 a month and competes against Spotify and various other streaming music platforms.
Sonos revenue climbed 11% in FY19 and 5% last year. Zacks estimates call for its 2021 (year ended October 2) sales to surge 29% to $1.71 billion, with FY22 projected to jump another 11% higher to come in at $1.90 billion. And it’s expected to swing from an adjusted loss of -$0.18 a share last year all the way to +$1.11 in FY21, with FY22 set to climb another 6% higher.
The speaker company’s strong management team helped it rip off four-straight massive quarterly earnings beats. This included posting adjusted earnings of +$0.27 a share last quarter vs. the Zacks consensus that called for a -$0.17 loss. Plus, the most recent Q4 EPS estimate—which Zacks calls the most accurate—comes in at +$0.07 a share, compared to the overall consensus of an adjusted loss of -$0.07. This could mean Sonos is due for another huge beat.
Sonos is scheduled to report its Q4 results on Wednesday, November 17 and its recent earnings revisions help it land a Zacks Rank #1 (Strong Buy) right now. Sonos also grabs an “A” grade for Growth in our Style Scores system and its Audio Video Production space ranks in the top 13% of our 250 Zacks industries.
The audio firm’s shares soared off their covid lows of under $10 to over $40 in April 2021. SONO is still up 50% this year, but it trades 20% beneath its highs at around $34 a share right now. Plus, its current Zacks consensus price target represents nearly 25% upside to Friday’s levels. And Sonos just recently popped above its 50-day moving average and it trades near its year-long lows at 26.7X forward earnings.
Tech IPOs With Massive Profit Potential
In the past few years, many popular platforms and like Uber and Airbnb finally made their way to the public markets. But the biggest paydays came from lesser-known names.
For example, electric carmaker X Peng shot up +299.4% in just 2 months. Think of it this way…
If you had put $5,000 into XPEV at its IPO in September 2020, you could have cashed out with $19,970 in November.
With record amounts of cash flooding into IPOs and a record-setting stock market, this year’s lineup could be even more lucrative.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
The brunt of hot inflation readings was borne by the tech-heavy Nasdaq Composite index, which tanked 1.7% on Nov 10. The big players in the space like Alphabet GOOGL lost at least 2%. The other two broad market indices, the S&P 500 and the Dow Jones Industrial Average, also lost 0.8% and 0.7%, respectively, in yesterday’s trading session.
– Zacks
The reason for this tech market slowdown can essentially be the high inflation reading which led to the benchmark 10-year Treasury yields rising by about 11 basis points. It is a fact that growth sectors like tech space feel the pain of rising bond yields as it decreases the relative value of future earnings, making the popular stocks seem overvalued. Tech companies also face hurdles in funding their growth and buying back stocks due to higher rates (per a CNBC article).
Per the latest Labor Department report, the Consumer Price Index (CPI) in October rose 6.2% year over year compared to the Dow Jones estimate of a 5.9% rise, per a CNBC article. The metric was at the highest level since December 1990.
In this regard, Nancy Davis, founder of Quadratic Capital Management, has commented that “Wednesday’s Consumer Price Index showed another month of inflation data well above the Federal Reserve’s inflation target, primarily due to continued supply chain issues and labor shortages. If inflation doesn’t subside, the Federal Reserve may need to taper at a more substantial rate and hike interest rates, which could hurt stocks and bonds,” per a CNBC article.
However, technology plays an instrumental role amid the COVID-19 uncertainty in aiding people to maintain safe-distancing norms.
The pandemic has been a blessing in disguise for the e-commerce industry to date as people continue to practice social distancing and shopping online for all essentials, especially food items. Thus, on par with the digitization trend, the upcoming U.S. holiday season is expected to see a significant surge in online sales. The National Retail Federation (“NRF”) projects online and other non-store sales surge of 11% to 15% to reach between $218.3 billion and $226 billion compared to $196.7 billion in 2020. Mastercard SpendingPulse predicts online sales to increase 7.5% during the “75 Days of Christmas” phase.
Certain other ‘new normal’ trends have also emerged amid the health crisis like work from home, increasing digital payments, growing video streaming and soaring video game sales.
Further, the semiconductor space has been gaining from expanding digitization and growing dependency on the Internet owing to some new normal trends like online shopping, work from home, digital payments, digitization of healthcare, rising demand for video gaming and many more. According to the Semiconductor Industry Association (“SIA”), global sales of semiconductors came in at $144.8 billion in the third quarter of 2021, leading to a jump of 27.6% year over year and 7.4% from the second quarter. In fact, the growing adoption of cloud computing and the ongoing infusion of AI, machine learning and IoT are expected to keep the sector brewing with opportunities in 2021.
Technology has played a major role in the ongoing health crisis. Telemedicine and Digital Health are receiving significant importance. In the present era, data management and storage have become integral aspects of healthcare. Thus, with the technological advancements in the healthcare sector and the rising adoption of healthcare IT solutions as well as advantages of cloud usage healthcare, the cloud computing market is on a growth trajectory.
The work-from-home model has bumped up sales of PCs, laptops and other kinds of computer peripherals. According to the latest Canalys report, worldwide PC sales have climbed 5% in the third quarter of 2021 from the previous quarter. Total shipments of desktops and notebooks, including workstations, also came in at 84.1 million units during this period.
Technology ETFs to Keep a Track of
All the factors discussed above highlight the instrumental role that technology plays amid the ongoing COVID-19 uncertainty in aiding people to maintain safe-distancing norms. Thus, investors could consider the following ETFs:
The fund seeks to track the performance of the MSCI US Investable Market Information Technology 25/50 Index. It has AUM of $55.63 billion. It charges investors 10 basis points (bps) in annual fees. The fund currently sports a Zacks ETF Rank #1 (Strong Buy), with a Medium-risk outlook.
The fund seeks to provide investment results that before expenses generally correspond with the price and yield performance of the Technology Select Sector Index. It has AUM of $49.02 billion. It charges investors 12 bps in annual fees. The fund presently flaunts a Zacks ETF Rank of 1, with a Medium-risk outlook (read: 4 ETF Plays as Buybacks Bounce Back & Likely to Soar Higher).
The fund seeks to provide investment results that before expenses generally correspond with the price and yield performance of the Russell 1000 Technology RIC 22.5/45 Capped Index. It has AUM of $9.53 billion. It charges investors 41 bps in annual fees, as stated in the prospectus. The fund currently sports a Zacks ETF Rank #1, with a Medium-risk outlook (read: 4 Sector ETFs & Stocks for Bountiful Returns in November ).
First Trust NASDAQ-100-Technology Sector Index Fund QTEC
The fund seeks to replicate as closely as possible, before fees and expenses, the price and yield of the NASDAQ-100 Technology Sector Index. It has AUM of $4.14 billion. It charges investors 57 bps in annual fees. The fund also flaunts a Zacks ETF Rank #1 at present, with a High-risk outlook.
Want key ETF info delivered straight to your inbox?
Zacks’ free Fund Newsletter will brief you on top news and analysis, as well as top-performing ETFs, each week.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Riot Blockchain (RIOT): The Bitcoin You Don’t Want to Miss
[embedded content]
It’s time to gain exposure to the skyrocketing cryptocurrency market as a tidal wave of curious individual and institutional investors alike pour into this booming asset class.
– Zacks
Riot Blockchain RIOT, now one of the world’s largest public bitcoin miners following its recent acquisition of Whinestone US, is positioned to provide us with the rare and exciting opportunity to profit off the resurging crypto market’s already prolific rally.
Bitcoin BTC has rallied north of 50% since the beginning October, notching a fresh all-time high at $69,000 a coin, remaining buoyantly above $60K today. Over $2 trillion in value has being added to this nearly $3 trillion market in 2021 as deep-pocketed institutional investors begin to deploy capital into this ambiguous asset class. The opportunity cost of not being a part of this rapidly appreciating digital currencies is just too great not to have some exposure.
RIOT, which is closely tied to the performance of bitcoin, had initially overshot the crypto rally in the first month and a half of the year as momentum chasing traders such as the (self-proclaimed) “degenerates” on r/WallStreetBets (WSB) drove this leading miner’s shares far above their intrinsic value. RIOT surged as much as 385% at the beginning of 2021, but its momentum-driven valuation bubble has since deflated. The stock is now trading over 50% below its highs to the value opportunity we see today.
At the beginning of the year, euphoric purchases of short-term call options drove RIOT’s moonshot price action, pushing it further out of institutional investors’ scope of investible assets, and giving it the WSB seal of overvaluation. RIOT has fallen so far out of favor with the markets as of late that it has come down to a P/E of less than 20x despite analysts estimating an over 60% increase in 2022 profits (following a 400% earnings jump this year) and a growth outlook that continues to accerlate. This is a highly discounted blockchain innovator that can’t be ignored amid this crypto explosion.
With bitcoin’s ripping rallying staying alive coupled with Riot Blockchain’s continuous operational enhancements as its scales, analysts are getting increasingly bullish on RIOT, inflating EPS estimates across all timelines and propelling the stock into a Zacks Rank #1 (Strong Buy).
All 5 of the covering sell-side analysts call RIOT a strong buy today, with an average price target of $52 a share, with some more bullish analysts giving it targets north of $80 (over 100% upside from here).
The Catalysts
US cryptocurrency miners were given one the greatest gift they could have asked for when China and Xi’s increasingly autocratic regime announced a reinforced ban on crypto mining earlier this year.
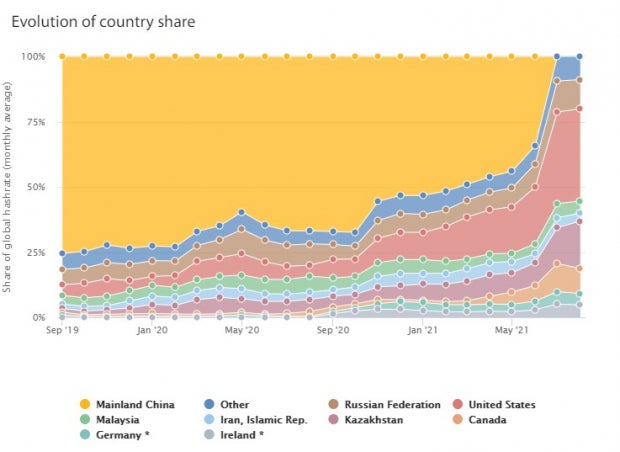
12 months ago, China controlled roughly 70% of the global bitcoin mining market, which is measured using hash rates. Hash rates are the speed at which cryptocurrencies are mined (attained through machine-based problem solving) and represent a measurement of computing power & efficiency (performance) of both individual & total market operations.
The strict crypto mining banned in Asia’s largest economy created a massive market hole, which US miners like Riot Blockchain quickly filled. The US is now the leading bitcoin miner by hash rate, controlling over 35% of this market, according to Cambridge Bitcoin Electricity Consumption Index (CBECI). Below is a graphic from the CBECI breaking down the monthly bitcoin mining market share by country.
Riot blockchain currently controls over 6% of the US’s highly fragmented bitcoin mining market and is taking more share on a seemingly daily basis. This blockchain innovator’s hash rate has more than quadrupled in the past year. Riot’s savvy management team is projecting its hash rate will reach 4.4 EH/s (doubling its rate in September) before this year is up and reach 7.7 EH/s by the end of 2022.
Its recent acquisition of Whinstone (the largest US crypto mining facility in the US) is the primary catalyst for its rapidly improving economies of scale forecast.
First Bitcoin ETF Hits Exchanges
Following SEC Chair Gary Gensler’s landmark approval, the first bitcoin-linked exchange-traded fund (ETF) hit the NYSE last month. Bitcoin soared over $65k for the first time in history following this ETF’s debut as institutional interest was further validated.
ProShares Bitcoin Strategy ETF BITO became the first bitcoin futures-backed ETF to trade in the US, and its premiere performance was outstanding, with inflows of nearly $2 billion in its first two days of trading. This was a milestone for the crypto market as its futures ETF approval opens the door for institutional funds and wary investors to obtain exposure to this dubious (yet profitable) crypto market through trusted US government-approved exchanges.
CME bitcoin futures (representing forward-looking derivative of the underlying asset) are the trusted crypto conduit the SEC is comfortable with exposing to the NYSE due to its regulatable nature – something that Defi (decentralized financial exchange) platforms, in which untraceable bitcoin trades, cannot claim.
The one primary issue surrounding this conduit for bitcoin exposure is that futures contracts will need to be continuously rolled over to the front-month contract, which will cost money and cause decay to the ETF’s value regarding bitcoin over time. You see this type of decay with virtually all commodity ETFs, similarly based on futures contracts.
Nevertheless, this SEC approval is a massive step towards legitimizing the crypto space, gaining unprecedented market traction in recent years. Today marked a significant stride towards actual bitcoin-supported ETFs, but Gary Gensler and the rest of the apprehensive SEC will need some convincing before this occurs.
Bitcoin bulls are on the hunt for $70k (trading within 1% of this level), which would mark a fresh all-time high for this currency of the future.
Energy Concerns
There has been growing attention surrounding the excessive use of energy required to power bitcoin mining facilities. Elon Musk is the most notable character voicing concerns about the use of fossil fuels to power digital asset mining operations, deciding to halt Tesla’s TSLA bitcoin usage earlier this year because of it. Energy is also the most significant variable cost for blockchain-based enterprises like Riot, so it’s central to assessing an investment in this unique space.
Riot’s primary operations are in Texas, ironically one of the cleanest and cheapest energy states (considering it’s the oil capital of the US). The Electric Reliable Council of Texas (ERCOT) powers one of the few deregulated energy markets with a vast competitive push towards inexpensive and sustainable sources. Wind and solar make up nearly 30% of the ERCOT market’s energy capacity, with relatively lower-carbon natural gas generating just over half.
Free-market energy in Texas provides Riot with relatively inexpensive variable costs from increasingly clean sources.
Final Thoughts
Like it or not, bitcoin is here to stay, and it’s time to get some portfolio exposure, if you haven’t already. RIOT presents us with a unique opportunity to acquire bitcoin exposure at a sizable discount as its underlining profit driver takes flight and its controlling market share proliferates.
RIOT has a significant competitive advantage in a market where scale means everything, with its recent acquisition of Whinstone leapfrogging its hash rate expansion. I would jump on this trade today before the window of opportunity for this rare high-growth value-play disappears.
Tech IPOs With Massive Profit Potential
In the past few years, many popular platforms and like Uber and Airbnb finally made their way to the public markets. But the biggest paydays came from lesser-known names.
For example, electric carmaker X Peng shot up +299.4% in just 2 months. Think of it this way…
If you had put $5,000 into XPEV at its IPO in September 2020, you could have cashed out with $19,970 in November.
With record amounts of cash flooding into IPOs and a record-setting stock market, this year’s lineup could be even more lucrative.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report