Are Earnings Estimates Going Down?

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

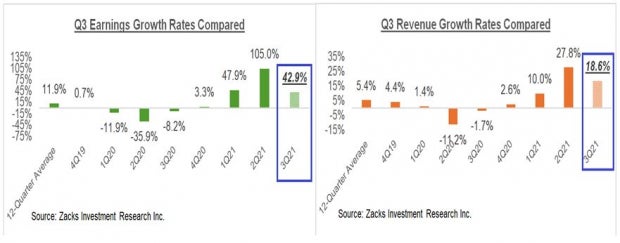
Earnings and revenue growth has come down in the ongoing Q3 earnings season from the first-half’s breakneck speed, but it is still very high.
– Zacks

You can see this in the comparison charts below that shows the Q3 earnings and revenue growth for the 445 S&P 500 members that have reported results through Friday, November 5th.
Zacks Investment ResearchImage Source: Zacks Investment Research

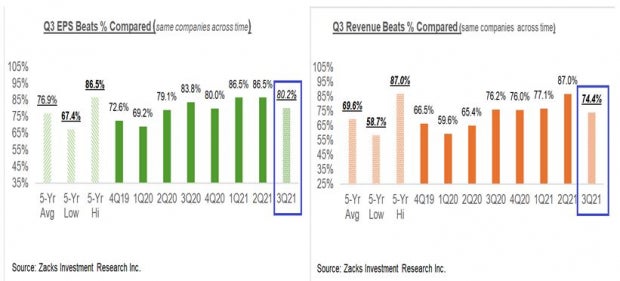
The unfavorable comparison to the first half of the year isn’t only with respect to the growth rates, as the proportion of these companies beating EPS and revenue estimates is also tracking below what we had seen from this same group earlier in the year, as you can see in the charts below.
Zacks Investment ResearchImage Source: Zacks Investment Research

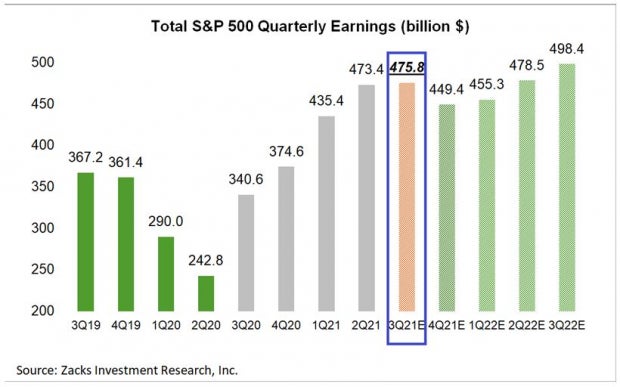
The decelerated growth pace notwithstanding, aggregate Q3 earnings for the S&P 500 index are on track to reach a new all-time quarterly record, surpassing the record set in the preceding quarter. You can see this in the chart below that shows the 2021 Q3 aggregate total at $475.8 billion.
Zacks Investment ResearchImage Source: Zacks Investment Research

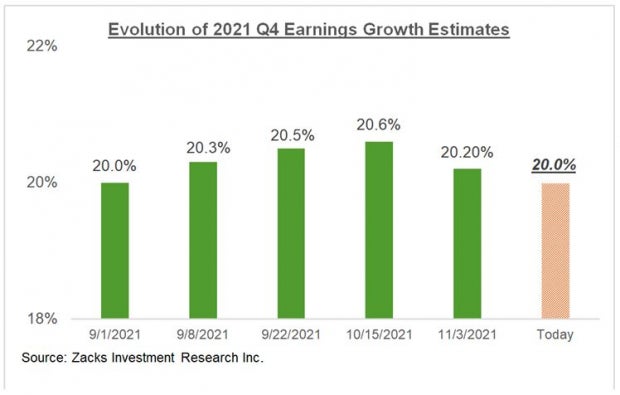
The one notable disconcerting development this earnings season is on the revisions front, with estimates for the current period (2021 Q4) turning modestly lower over the last few days.
Zacks Investment ResearchImage Source: Zacks Investment Research

This is in contrast to the persistent positive revisions trend that we have been seeing since the Summer of 2020. While the magnitude of negative revisions in the aggregate to Q4 estimates is fairly modest, it is relatively more pronounced for the Retail and Transportation sectors.

A case in point is Amazon AMZN, part of the Zacks Retail sector, whose Q4 consensus EPS estimate has dropped from $12.13 a few weeks back to $5.11 at present.

Partly offsetting these estimate cuts are rising estimates for the Energy sector, which have been steadily going up lately.

While estimates for 2021 Q4 have modestly come down, we are seeing the opposite for next year’s estimates. Earnings estimates for full-year 2022 have gone up +24.8% since January 2020 and +10% since the start of October.

Sectors enjoying the strongest positive estimate revisions include Consumer Discretionary, Autos, Transportation, Aerospace, Energy, Construction, Business Services and Finance. 

The bottom line on the revisions front is that it still remains positive, with estimates for next year going up even though they have trended down modestly for the current period (2021 Q4).

Q3 Earnings Season Scorecard

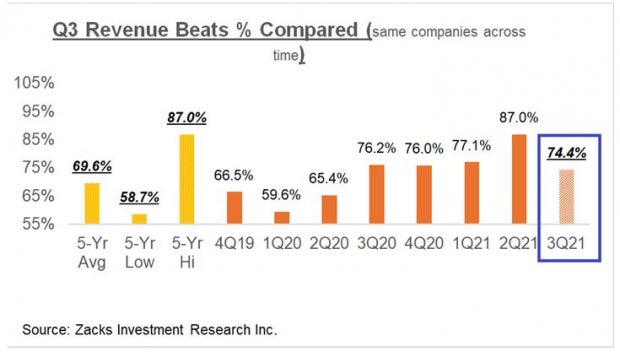
Including all the results that came out through Friday, November 5th, we now have Q3 results from 445 S&P 500 members or 89.2% of the index’s total membership. Total earnings (or aggregate net income) for these companies are up +42.9% from the same period last year on +18.6% lower revenues, with 80.2% beating EPS estimates and 74.4% beating revenue estimates. The proportion of these companies beating both EPS and revenue estimates is 62.9%, the blended beats percentage.

The comparison chart below shows how the Q3 blended beats percentage compare to other recent periods for this same group of 445 index members.
Zacks Investment ResearchImage Source: Zacks Investment Research

This week brings Q3 results from more than 850 companies, including 13 S&P 500 members. The notable index members reporting results this week include Disney DIS, PayPal PYPL and DR Horton DRH. 

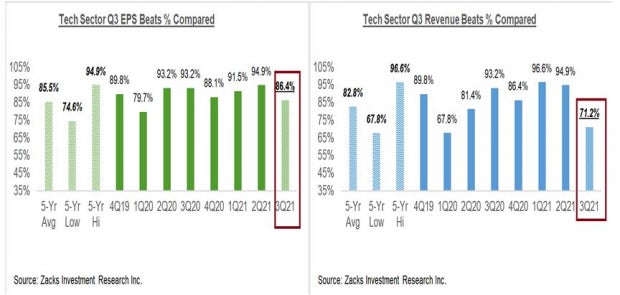
For the Technology sector, we now have Q3 results from 82.5% of the sector’s market capitalization in the S&P 500 index. Total Q3 earnings for these Tech companies are up +35.8% from the same period last year on +17.3% higher revenues, with 86.4% beating EPS estimates and 71.2% beating revenue estimates.

The comparison charts below put the sector’s Q3 EPS and revenue beats percentages in a historical context.
Zacks Investment ResearchImage Source: Zacks Investment Research

As you can see above, the proportion of these Tech companies beating revenue estimates has been clearly on the low side this earnings season.

Expectations for Q3 & Beyond

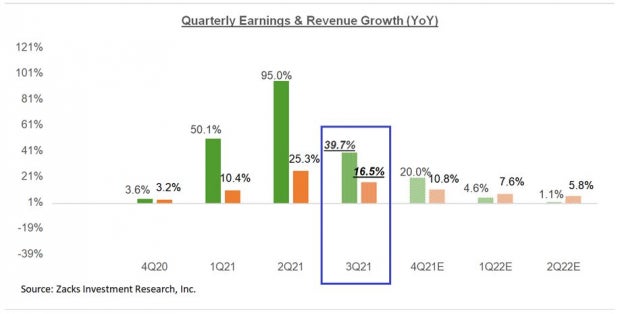
Looking at the quarter as a whole, combining the actual results that have come out with estimates for the still-to-come companies, total Q3 earnings for the S&P 500 index are expected to be up +39.7% from the same period last year on +16.5% higher revenues.

The chart below presents the earnings and revenue growth picture on a quarterly basis, with expectations for 2021 Q3 contrasted with the actual growth achieved over the preceding four quarters and estimates for the following three.
Zacks Investment ResearchImage Source: Zacks Investment Research

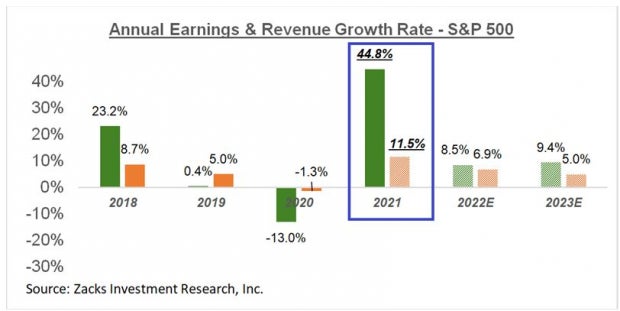
The chart below shows the comparable picture on an annual basis.
Zacks Investment ResearchImage Source: Zacks Investment Research

For a detailed look at the overall earnings picture, including expectations for the coming periods, please check out our weekly Earnings Trends report >>>>Looking At Margins in the Face of Inflationary and Logistical Issues

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Amazon.com, Inc. (AMZN): Free Stock Analysis Report
 
The Walt Disney Company (DIS): Free Stock Analysis Report
 
DiamondRock Hospitality Company (DRH): Free Stock Analysis Report
 
PayPal Holdings, Inc. (PYPL): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/395797


Itron (ITRI) Earnings Beat Estimates in Q3, Revenues Miss

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Itron, Inc. ITRI reported third-quarter 2021 non-GAAP earnings of 21 cents per share, which surpassed the Zacks Consensus Estimate by 50%.
However, the bottom line declined 65.6% year over year.
Revenues were $486.95 million, which lagged the Zacks Consensus Estimate of $524 million. Further, the top line decreased 9.9% year over year.
The decline in the top line was attributed to component constraints. Sluggishness in the company’s Device Solutions and Networked Solutions segment was another major concern.
Nevertheless, Outcomes segments performed well in the reported quarter.
Product revenues were $410.9 million (84.4% of total revenues), down 12.7% year over year. Service revenues totaled $76 million (15.6%), which increased 9.3% from the year-ago quarter.
The company’s bookings were $395 million and the backlog totaled $3.4 billion at the end of the reported quarter.

– Zacks

Segments in Detail

Device Solutions: The company generated revenues of $152.2 million (31.2% of total revenues) from the segment, down 13.6% from the year-ago quarter.
Networked Solutions: Revenues from the segment were $274.5 million (56.4% of total revenues), down 10.5% year over year.
Outcomes: The segment generated revenues of $60.2 million (12.4% of total revenues), up 4.9% on a year-over-year basis.

Operating Details

For the third quarter, Itron’s gross margin was 27.7%, which expanded 120 basis points (bps) on a year-over-year basis. This was driven by a favorable product mix.
Non-GAAP operating expenses were $118.6 million, up 4.4% year over year.
Non-GAAP operating margin was 3.4%, contracting 210 bps from the year-ago quarter.

Balance Sheet & Cash Flows

As of Sep 30, 2021, cash and cash equivalents totaled $188.7 million, down from $207.1 million as of Jun 30, 2021. Accounts receivables were $320.9 million, down from $336.1 million in the prior quarter.
Long-term debt at the end of the third quarter stood at $449.6 million compared with $479.03 million at the end of the second quarter.
Itron generated $18.5 million of cash from operations in the reported quarter compared with $72.7 million in the prior quarter.
It generated a free cash flow of $11.2 million in the third quarter.

Zacks Rank & Stocks to Consider

Currently, Itron has a Zacks Rank #5 (Strong Sell).
Some better-ranked stocks in the broader technology sector include Advanced Micro Devices AMD, PerkinElmer PKI and Mimecast Ltd. MIME. While Advanced Micro Devices sports a Zacks Rank #1 (Strong Buy), PerkinElmer and Mimecast carry a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Long-term earnings growth rates for Advanced Micro Devices, PerkinElmer, and Mimecast are currently projected at 46.2%, 41.7%, and 35%, respectively.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Advanced Micro Devices, Inc. (AMD): Free Stock Analysis Report
 
Itron, Inc. (ITRI): Free Stock Analysis Report
 
PerkinElmer, Inc. (PKI): Free Stock Analysis Report
 
Mimecast Limited (MIME): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/395798


Mack-Cali Realty (CLI) Q3 FFO and Revenues Surpass Estimates

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Mack-Cali Realty (CLI) came out with quarterly funds from operations (FFO) of $0.17 per share, beating the Zacks Consensus Estimate of $0.13 per share. This compares to FFO of $0.30 per share a year ago. These figures are adjusted for non-recurring items.

– Zacks

This quarterly report represents an FFO surprise of 30.77%. A quarter ago, it was expected that this real estate investment trust would post FFO of $0.12 per share when it actually produced FFO of $0.15, delivering a surprise of 25%.

Over the last four quarters, the company has surpassed consensus FFO estimates three times.

Mack-Cali, which belongs to the Zacks REIT and Equity Trust – Other industry, posted revenues of $83.74 million for the quarter ended September 2021, surpassing the Zacks Consensus Estimate by 8.63%. This compares to year-ago revenues of $77.65 million. The company has topped consensus revenue estimates just once over the last four quarters.

The sustainability of the stock’s immediate price movement based on the recently-released numbers and future FFO expectations will mostly depend on management’s commentary on the earnings call.

Mack-Cali shares have added about 47.8% since the beginning of the year versus the S&P 500’s gain of 23.3%.

What’s Next for Mack-Cali?

While Mack-Cali has outperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?

There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s FFO outlook. Not only does this include current consensus FFO expectations for the coming quarter(s), but also how these expectations have changed lately.

Empirical research shows a strong correlation between near-term stock movements and trends in estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of estimate revisions.

Ahead of this earnings release, the estimate revisions trend for Mack-Cali was unfavorable. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #4 (Sell) for the stock. So, the shares are expected to underperform the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus FFO estimate is $0.13 on $74.77 million in revenues for the coming quarter and $0.60 on $319.8 million in revenues for the current fiscal year.

Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, REIT and Equity Trust – Other is currently in the top 41% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.

Zacks Names “Single Best Pick to Double”

From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.

You know this company from its past glory days, but few would expect that it’s poised for a monster turnaround. Fresh from a successful repositioning and flush with A-list celeb endorsements, it could rival or surpass other recent Zacks’ Stocks Set to Double like Boston Beer Company which shot up +143.0% in a little more than 9 months and Nvidia which boomed +175.9% in one year.

Free: See Our Top Stock and 4 Runners Up >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
MackCali Realty Corporation (CLI): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/395304


Titan International (TWI) Matches Q3 Earnings Estimates

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Titan International (TWI) came out with quarterly earnings of $0.17 per share, in line with the Zacks Consensus Estimate. This compares to loss of $0.10 per share a year ago. These figures are adjusted for non-recurring items.

– Zacks

A quarter ago, it was expected that this wheel and tire supplier would post earnings of $0.14 per share when it actually produced earnings of $0.22, delivering a surprise of 57.14%.

Over the last four quarters, the company has surpassed consensus EPS estimates three times.

Titan International, which belongs to the Zacks Manufacturing – Farm Equipment industry, posted revenues of $450.38 million for the quarter ended September 2021, surpassing the Zacks Consensus Estimate by 8.32%. This compares to year-ago revenues of $304.77 million. The company has topped consensus revenue estimates four times over the last four quarters.

The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.

Titan International shares have added about 53.7% since the beginning of the year versus the S&P 500’s gain of 23.3%.

What’s Next for Titan International?

While Titan International has outperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?

There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.

Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.

Ahead of this earnings release, the estimate revisions trend for Titan International was mixed. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #3 (Hold) for the stock. So, the shares are expected to perform in line with the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $0.11 on $399.16 million in revenues for the coming quarter and $0.55 on $1.66 billion in revenues for the current fiscal year.

Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Manufacturing – Farm Equipment is currently in the bottom 31% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.

Zacks Names “Single Best Pick to Double”

From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.

You know this company from its past glory days, but few would expect that it’s poised for a monster turnaround. Fresh from a successful repositioning and flush with A-list celeb endorsements, it could rival or surpass other recent Zacks’ Stocks Set to Double like Boston Beer Company which shot up +143.0% in a little more than 9 months and Nvidia which boomed +175.9% in one year.

Free: See Our Top Stock and 4 Runners Up >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Titan International, Inc. (TWI): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/395305


TechTarget (TTGT) Tops Q3 Earnings and Revenue Estimates

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

TechTarget (TTGT) came out with quarterly earnings of $0.60 per share, beating the Zacks Consensus Estimate of $0.57 per share. This compares to earnings of $0.30 per share a year ago. These figures are adjusted for non-recurring items.

– Zacks

This quarterly report represents an earnings surprise of 5.26%. A quarter ago, it was expected that this operator of websites for information technology vendors would post earnings of $0.48 per share when it actually produced earnings of $0.51, delivering a surprise of 6.25%.

Over the last four quarters, the company has surpassed consensus EPS estimates four times.

TechTarget, which belongs to the Zacks Internet – Content industry, posted revenues of $69.75 million for the quarter ended September 2021, surpassing the Zacks Consensus Estimate by 4.39%. This compares to year-ago revenues of $36.24 million. The company has topped consensus revenue estimates four times over the last four quarters.

The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.

TechTarget shares have added about 61% since the beginning of the year versus the S&P 500’s gain of 23.3%.

What’s Next for TechTarget?

While TechTarget has outperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?

There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.

Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.

Ahead of this earnings release, the estimate revisions trend for TechTarget was mixed. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #3 (Hold) for the stock. So, the shares are expected to perform in line with the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $0.66 on $77.01 million in revenues for the coming quarter and $2.15 on $266.16 million in revenues for the current fiscal year.

Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Internet – Content is currently in the bottom 32% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.

Zacks Names “Single Best Pick to Double”

From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.

You know this company from its past glory days, but few would expect that it’s poised for a monster turnaround. Fresh from a successful repositioning and flush with A-list celeb endorsements, it could rival or surpass other recent Zacks’ Stocks Set to Double like Boston Beer Company which shot up +143.0% in a little more than 9 months and Nvidia which boomed +175.9% in one year.

Free: See Our Top Stock and 4 Runners Up >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
TechTarget, Inc. (TTGT): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/395306


Anterix (ATEX) Reports Q2 Loss, Tops Revenue Estimates

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Anterix (ATEX) came out with a quarterly loss of $0.67 per share versus the Zacks Consensus Estimate of a loss of $0.68. This compares to loss of $0.94 per share a year ago. These figures are adjusted for non-recurring items.

– Zacks

This quarterly report represents an earnings surprise of 1.47%. A quarter ago, it was expected that this wireless communications company would post a loss of $0.63 per share when it actually produced a loss of $0.67, delivering a surprise of -6.35%.

Over the last four quarters, the company has surpassed consensus EPS estimates three times.

Anterix, which belongs to the Zacks Communication – Infrastructure industry, posted revenues of $0.18 million for the quarter ended September 2021, surpassing the Zacks Consensus Estimate by 1.11%. This compares to year-ago revenues of $0.25 million. The company has topped consensus revenue estimates three times over the last four quarters.

The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.

Anterix shares have added about 72.5% since the beginning of the year versus the S&P 500’s gain of 23.3%.

What’s Next for Anterix?

While Anterix has outperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?

There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.

Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.

Ahead of this earnings release, the estimate revisions trend for Anterix was favorable. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #2 (Buy) for the stock. So, the shares are expected to outperform the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is -$0.67 on $0.54 million in revenues for the coming quarter and -$2.11 on $1.7 million in revenues for the current fiscal year.

Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Communication – Infrastructure is currently in the top 42% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.

Zacks Names “Single Best Pick to Double”

From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.

You know this company from its past glory days, but few would expect that it’s poised for a monster turnaround. Fresh from a successful repositioning and flush with A-list celeb endorsements, it could rival or surpass other recent Zacks’ Stocks Set to Double like Boston Beer Company which shot up +143.0% in a little more than 9 months and Nvidia which boomed +175.9% in one year.

Free: See Our Top Stock and 4 Runners Up >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Anterix Inc. (ATEX): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/395294


Owl Rock Capital Corporation (ORCC) Q3 Earnings and Revenues Surpass Estimates

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Owl Rock Capital Corporation (ORCC) came out with quarterly earnings of $0.33 per share, beating the Zacks Consensus Estimate of $0.32 per share. This compares to earnings of $0.33 per share a year ago. These figures are adjusted for non-recurring items.

– Zacks

This quarterly report represents an earnings surprise of 3.13%. A quarter ago, it was expected that this company would post earnings of $0.29 per share when it actually produced earnings of $0.30, delivering a surprise of 3.45%.

Over the last four quarters, the company has surpassed consensus EPS estimates three times.

Owl Rock Capital Corporation, which belongs to the Zacks Financial – Miscellaneous Services industry, posted revenues of $269.19 million for the quarter ended September 2021, surpassing the Zacks Consensus Estimate by 4.03%. This compares to year-ago revenues of $187.06 million. The company has topped consensus revenue estimates three times over the last four quarters.

The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.

Owl Rock Capital Corporation shares have added about 14.5% since the beginning of the year versus the S&P 500’s gain of 23.3%.

What’s Next for Owl Rock Capital Corporation?

While Owl Rock Capital Corporation has underperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?

There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.

Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.

Ahead of this earnings release, the estimate revisions trend for Owl Rock Capital Corporation was mixed. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #3 (Hold) for the stock. So, the shares are expected to perform in line with the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $0.32 on $262.89 million in revenues for the coming quarter and $1.20 on $992.24 million in revenues for the current fiscal year.

Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Financial – Miscellaneous Services is currently in the top 19% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.

Zacks Names “Single Best Pick to Double”

From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.

You know this company from its past glory days, but few would expect that it’s poised for a monster turnaround. Fresh from a successful repositioning and flush with A-list celeb endorsements, it could rival or surpass other recent Zacks’ Stocks Set to Double like Boston Beer Company which shot up +143.0% in a little more than 9 months and Nvidia which boomed +175.9% in one year.

Free: See Our Top Stock and 4 Runners Up >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Owl Rock Capital Corporation (ORCC): Free Stock Analysis Report
 
To read this article on Zacks.com click here.

https://www.entrepreneur.com/article/395295


Markel (MKL) Surpasses Q3 Earnings Estimates

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Markel (MKL) came out with quarterly earnings of $13.77 per share, beating the Zacks Consensus Estimate of $12.94 per share. This compares to earnings of $4.41 per share a year ago. These figures are adjusted for non-recurring items.

– Zacks

This quarterly report represents an earnings surprise of 6.41%. A quarter ago, it was expected that this insurer would post earnings of $15.45 per share when it actually produced earnings of $19.14, delivering a surprise of 23.88%.

Over the last four quarters, the company has surpassed consensus EPS estimates three times.

Markel, which belongs to the Zacks Insurance – Property and Casualty industry, posted revenues of $2.71 billion for the quarter ended September 2021, missing the Zacks Consensus Estimate by 1.13%. This compares to year-ago revenues of $2.37 billion. The company has topped consensus revenue estimates two times over the last four quarters.

The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.

Markel shares have added about 27.4% since the beginning of the year versus the S&P 500’s gain of 22.8%.

What’s Next for Markel?

While Markel has outperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?

There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.

Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.

Ahead of this earnings release, the estimate revisions trend for Markel was unfavorable. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #4 (Sell) for the stock. So, the shares are expected to underperform the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $15.66 on $2.78 billion in revenues for the coming quarter and $57.93 on $10.72 billion in revenues for the current fiscal year.

Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Insurance – Property and Casualty is currently in the bottom 31% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.

5 Stocks Set to Double

Each was handpicked by a Zacks expert as the #1 favorite stock to gain +100% or more in 2021. Previous recommendations have soared +143.0%, +175.9%, +498.3% and +673.0%.

Most of the stocks in this report are flying under Wall Street radar, which provides a great opportunity to get in on the ground floor.

Today, See These 5 Potential Home Runs >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Markel Corporation (MKL): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/395031


B2Gold (BTG) Misses Q3 Earnings and Revenue Estimates

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

B2Gold (BTG) came out with quarterly earnings of $0.12 per share, missing the Zacks Consensus Estimate of $0.13 per share. This compares to earnings of $0.15 per share a year ago. These figures are adjusted for non-recurring items.

– Zacks

This quarterly report represents an earnings surprise of -7.69%. A quarter ago, it was expected that this gold, silver and copper miner would post earnings of $0.07 per share when it actually produced earnings of $0.04, delivering a surprise of -42.86%.

Over the last four quarters, the company has surpassed consensus EPS estimates two times.

B2Gold, which belongs to the Zacks Mining – Gold industry, posted revenues of $510.86 million for the quarter ended September 2021, missing the Zacks Consensus Estimate by 2.77%. This compares to year-ago revenues of $487.17 million. The company has topped consensus revenue estimates two times over the last four quarters.

The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.

B2Gold shares have lost about 25% since the beginning of the year versus the S&P 500’s gain of 22.8%.

What’s Next for B2Gold?

While B2Gold has underperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?

There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.

Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.

Ahead of this earnings release, the estimate revisions trend for B2Gold was mixed. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #3 (Hold) for the stock. So, the shares are expected to perform in line with the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $0.14 on $529.4 million in revenues for the coming quarter and $0.43 on $1.76 billion in revenues for the current fiscal year.

Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Mining – Gold is currently in the bottom 13% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.

5 Stocks Set to Double

Each was handpicked by a Zacks expert as the #1 favorite stock to gain +100% or more in 2021. Previous recommendations have soared +143.0%, +175.9%, +498.3% and +673.0%.

Most of the stocks in this report are flying under Wall Street radar, which provides a great opportunity to get in on the ground floor.

Today, See These 5 Potential Home Runs >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
B2Gold Corp (BTG): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/395032


Amdocs (DOX) Misses Q4 Earnings and Revenue Estimates

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Amdocs (DOX) came out with quarterly earnings of $1.16 per share, missing the Zacks Consensus Estimate of $1.18 per share. This compares to earnings of $1.23 per share a year ago. These figures are adjusted for non-recurring items.

– Zacks

This quarterly report represents an earnings surprise of -1.69%. A quarter ago, it was expected that this provider of computer systems integration would post earnings of $1.18 per share when it actually produced earnings of $1.35, delivering a surprise of 14.41%.

Over the last four quarters, the company has surpassed consensus EPS estimates two times.

Amdocs, which belongs to the Zacks Computers – IT Services industry, posted revenues of $1.09 billion for the quarter ended September 2021, missing the Zacks Consensus Estimate by 1.76%. This compares to year-ago revenues of $1.05 billion. The company has topped consensus revenue estimates three times over the last four quarters.

The sustainability of the stock’s immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management’s commentary on the earnings call.

Amdocs shares have added about 10.1% since the beginning of the year versus the S&P 500’s gain of 22.8%.

What’s Next for Amdocs?

While Amdocs has underperformed the market so far this year, the question that comes to investors’ minds is: what’s next for the stock?

There are no easy answers to this key question, but one reliable measure that can help investors address this is the company’s earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.

Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.

Ahead of this earnings release, the estimate revisions trend for Amdocs was mixed. While the magnitude and direction of estimate revisions could change following the company’s just-released earnings report, the current status translates into a Zacks Rank #3 (Hold) for the stock. So, the shares are expected to perform in line with the market in the near future. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $1.29 on $1.14 billion in revenues for the coming quarter and $5.21 on $4.51 billion in revenues for the current fiscal year.

Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Computers – IT Services is currently in the bottom 22% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.

5 Stocks Set to Double

Each was handpicked by a Zacks expert as the #1 favorite stock to gain +100% or more in 2021. Previous recommendations have soared +143.0%, +175.9%, +498.3% and +673.0%.

Most of the stocks in this report are flying under Wall Street radar, which provides a great opportunity to get in on the ground floor.

Today, See These 5 Potential Home Runs >>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Amdocs Limited (DOX): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/395021