Why This 1 Computer and Technology Stock Could Be a Great Addition to Your Portfolio

Here at Zacks, we offer our members many different opportunities to take full advantage of the stock market, as well as how to invest in ways that lead to long-term success.

– Zacks

The Zacks Premium service, which provides daily updates of the Zacks Rank and Zacks Industry Rank; full access to the Zacks #1 Rank List; Equity Research reports; and Premium stock screens like the Earnings ESP filter, makes these more manageable goals. All of the features can help you identify what stocks to buy, what to sell, and what are today’s hottest industries.

Also included in Zacks Premium is the Focus List. This is a long-term portfolio of top stocks that have all the traits to beat the market.

Breaking Down the Zacks Focus List

If you could, wouldn’t you jump at the chance for access to a curated list of stocks to kickstart your investing journey?

Enter the Zacks Focus List. It’s a portfolio made up of 50 stocks that are set to beat the market over the next 12 months; each company selected serves as a foundation for long-term investors looking to create an individual portfolio.

Additionally, each selection is accompanied by a full Zacks Analyst Report, something that makes the Focus List even more valuable. The report explains in detail why each stock was picked and why we believe it’s good for the long-term.

The portfolio’s past performance only solidifies why investors should consider it as a starting point. For 2020, the Focus List gained 13.85% on an annualized basis compared to the S&P 500’s return of 9.38%. Cumulatively, the portfolio has returned 2,519.23% while the S&P returned 854.95%. Returns are for the period of February 1, 1996 to March 31, 2021.

Focus List Methodology

When stocks are picked for the Focus List, it reflects our enduring reliance on the power of earnings estimate revisions.

Earnings estimates are expectations of growth and profitability, and are determined by brokerage analysts. Together with company management, these analysts examine every aspect that may affect future earnings, like interest rates, the economy, and sector and industry optimism.

Earnings estimate revisions are very important, since investors also need to take into consideration what a company will earn in the future.

When a stock receives upward earnings estimate revisions, it will likely get even more positive changes in the future. For instance, if an analyst raised their earnings outlook last month, they’ll probably do so again this month, and other analysts will follow.

Utilizing the power of earnings estimate revisions is when the Zacks Rank joins the party. A unique, proprietary stock-rating model, the Zacks Rank uses changes to quarterly earnings expectations to help investors create a winning portfolio.

The Zacks Rank consists of four main pillars: Agreement, Magnitude, Upside, and Surprise. Each one is given a raw score, which is recalculated every night and compiled into the Rank. Then, stocks are classified into five groups, ranging from “Strong Buy” to “Strong Sell,” using this data.

The Focus List is comprised of stocks hand-picked from a long list of #1 (Strong Buy) or #2 (Buy) ranked companies, meaning that each new addition boasts a bullish earnings consensus among analysts.

Since stock prices respond to revisions, it can be very profitable to buy stocks with rising earnings estimates. By buying Focus List stocks, then, you’re likely getting into companies whose future earnings estimates will be raised, potentially leading to price momentum.

Focus List Spotlight: Microsoft MSFT

Redmond, WA-based Microsoft Corporation is one of the largest broad-based technology providers in the world. The company dominates the PC software market with more than 80% of the market share for operating systems.

MSFT, a #2 (Buy) stock, was added to the Focus List on February 1, 2016 at $55.09 per share. Since then, shares have increased 424.16% to $288.76.

For fiscal 2022, one analyst revised their earnings estimate upwards in the last 60 days, and the Zacks Consensus Estimate sits at $8.64 per share. MSFT boasts an average earnings surprise of 16.9%.

Earnings for MSFT are forecasted to see growth of 8.4% for the current fiscal year as well.

Another standout Focus List stock you could consider is Visa Inc. V. Visa is a financial transaction processing company that offers a wide range of branded payment products like credit, debit, and prepaid cards.

Visa is a #2 (Buy)-ranked stock, and shares have gained almost 140% since being added to the portfolio.

Two analysts have raised their earnings outlook for the current fiscal year, with Visa’s bottom line now expected to rise 15.5% year-over-year; the Zacks Consensus Estimate has increased $0.04 to $5.82 per share. Additionally, Visa has an average earnings surprise of 9.03%.

Reveal Winning Stocks

Unlock all of our powerful research, tools and analysis, including the Zacks #1 Rank List, Equity Research Reports, Zacks Earnings ESP Filter, Premium Screener and more, as part of Zacks Premium. You’ll quickly identify which stocks to buy, hold and sell, and target today’s hottest industries, to help improve the performance of your portfolio. Gain full access now >>

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Microsoft Corporation (MSFT): Free Stock Analysis Report
 
Visa Inc. (V): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/389792


Buy the Dip in Vale, Here’s Why

One of the largest iron ore producers in the world, Vale’s (VALE) shares have plunged significantly from its 52-week high of $23.18, which it hit on June 25, 2021. However, it could be wise to buy the dip in the stock because of its solid financials. Read on for details.

shutterstock.com – StockNews

Headquartered in Rio de Janeiro, Brazil, Vale S.A. (VALE) is one of the largest iron ore, pellets, and nickel producers. The company has run into several issues over the past few years. On October 5, it halted the production of copper concentrate at its Salobo mine. In June 2021, Judge Vivianne Celia Ferreira Ramos Correa ordered VALE to pay $197,240 in compensation to each of the families of 131 employees killed in the collapse of a mining dam in 2019. Consequently, the stock has lost 39.4% since hitting its 52-week high of $23.18 on June 25, 2021, to close yesterday’s trading session at $13.74.

The stock has gained 27.8% over the past year. Its revenue and EPS have grown at CAGRs of 35.7% and 74.7%, respectively, over the past three years. VALE paid $7.60 billion in first-half dividends, its largest payout since its 2019 dam collapse. Moreover, its top line and bottom line increased in the second quarter. So, the stock’s near-term prospects look promising.

Here are the factors that could shape VALE’s performance in the upcoming months:

Positive Developments

On September 9, VALE launched ‘green briquette,’ developed over almost 20 years, which can reduce by up to 10% of the greenhouse gases (GHG) emissions in the steel production by its steelmaking clients. This solution is part of the company’s strategy to reduce its Scope 3 emissions related to its value chain by 15% by 2035.

VALE announced on September 2 that it had begun using self-driving trucks for the first time at its Carajas complex as it continues to expand its use of driverless technology. In addition, the company signed a Memorandum of Understanding with Ternium S.A. (TX) on August 19 to pursue opportunities to develop steelmaking solutions focused on reducing CO2 emissions.

Solid Financials

For the second quarter ended June 30, 2021, VALE’s net operating revenue came in at $16.68 billion, representing a 121.8% year-over-year rise. The company’s operating income increased 366.1% year-over-year to $9.71 billion. While its net income increased 720.1% year-over-year to $7.54 billion, its EPS came in at $1.49, up 684.2% year-over-year. Also, its adjusted EBITDA increased 227.4% from the same period last year to $11.04 billion.

Favorable Analyst Estimates

Analysts expect VALE’s revenue to increase 51.6% for the quarter ended September 30, 2021, and 48.7% in fiscal 2021. The company’s EPS is expected to increase 125.4% for the quarter ended September 30, 2021, and 447.4% this year. Also, its EPS is expected to grow at a rate of 11.1% per annum over the next five years. Moreover, Wall Street analysts expect the stock to hit $20.94 in the near term, which indicates a potential upside of 52.4%.

POWR Ratings Show Promise

VALE has an overall rating of B, which equates to a Buy in our POWR Ratings system. The POWR Ratings are calculated by taking into account 118 different factors, with each factor weighted to an optimal degree. 

Our proprietary rating system also evaluates each stock based on eight different categories. Out of these categories, VALE has a B grade for Growth, consistent with analysts’ expectations that its revenue and EPS will increase this year.

The stock has an A grade for Value, in sync with its forward non-GAAP P/E and EV/S of 2.82x and 1.27x, lower than the industry averages of 14.10x and 1.65x, respectively.

Moreover, VALE has an A grade for Quality. This is justified as its trailing-12-month gross profit margin of 61.64% is 103.1% higher than the industry average of 30.35%. Its trailing-12-month ROCE and ROTA of 46.08% and 18.83% are higher than the industry averages of 12.35% and 5.07%, respectively.

VALE is ranked #5 out of 36 stocks in the Industrial – Metals industry. Also, click here to see VALE’s ratings for Stability, Sentiment, and Momentum as well.

Bottom Line

VALE reported impressive results in the second quarter, thanks to increased iron ore sales volume and favorable market conditions. Even as regional supply issues persist and demand recovers, the company expects to see the market in a marginal surplus this year. So, it could be wise to bet on the stock now.

How Does Vale (VALE) Stack Up Against its Peers?

While VALE has an overall POWR Rating of B, you could also check out these other stocks within the Industrial – Metals industry with an A (Strong Buy) rating: Ryerson Holding Corporation (RYI), Atkore Inc. (ATKR), and Norsk Hydro ASA (NHYDY).


VALE shares were trading at $14.04 per share on Wednesday afternoon, up $0.30 (+2.18%). Year-to-date, VALE has declined -1.83%, versus a 17.08% rise in the benchmark S&P 500 index during the same period.


About the Author: Manisha Chatterjee

Since she was young, Manisha has had a strong interest in the stock market. She majored in Economics in college and has a passion for writing, which has led to her career as a research analyst.

More…

The post Buy the Dip in Vale, Here’s Why appeared first on StockNews.com

https://www.entrepreneur.com/article/389802


Wells Fargo (WFC) Earnings Expected to Grow: What to Know Ahead of Q3 Release

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Wall Street expects a year-over-year increase in earnings on lower revenues when Wells Fargo (WFC) reports results for the quarter ended September 2021. While this widely-known consensus outlook is important in gauging the company’s earnings picture, a powerful factor that could impact its near-term stock price is how the actual results compare to these estimates.

– Zacks

The earnings report might help the stock move higher if these key numbers are better than expectations. On the other hand, if they miss, the stock may move lower.

While management’s discussion of business conditions on the earnings call will mostly determine the sustainability of the immediate price change and future earnings expectations, it’s worth having a handicapping insight into the odds of a positive EPS surprise.

Zacks Consensus Estimate

This biggest U.S. mortgage lender is expected to post quarterly earnings of $1.04 per share in its upcoming report, which represents a year-over-year change of +85.7%.

Revenues are expected to be $18.7 billion, down 0.9% from the year-ago quarter.

Estimate Revisions Trend

The consensus EPS estimate for the quarter has been revised 3.37% higher over the last 30 days to the current level. This is essentially a reflection of how the covering analysts have collectively reassessed their initial estimates over this period.

Investors should keep in mind that the direction of estimate revisions by each of the covering analysts may not always get reflected in the aggregate change.

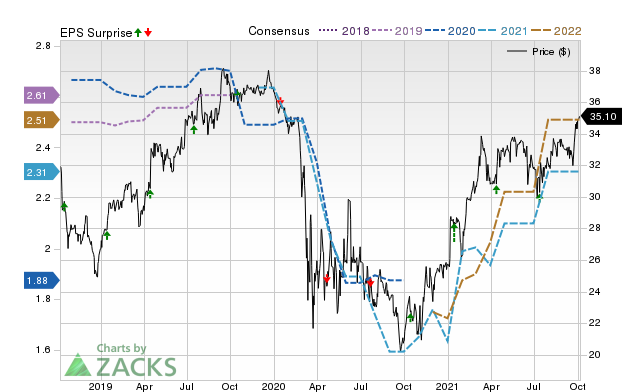
Price, Consensus and EPS Surprise

Earnings Whisper

Estimate revisions ahead of a company’s earnings release offer clues to the business conditions for the period whose results are coming out. Our proprietary surprise prediction model — the Zacks Earnings ESP (Expected Surprise Prediction) — has this insight at its core.

The Zacks Earnings ESP compares the Most Accurate Estimate to the Zacks Consensus Estimate for the quarter; the Most Accurate Estimate is a more recent version of the Zacks Consensus EPS estimate. The idea here is that analysts revising their estimates right before an earnings release have the latest information, which could potentially be more accurate than what they and others contributing to the consensus had predicted earlier.

Thus, a positive or negative Earnings ESP reading theoretically indicates the likely deviation of the actual earnings from the consensus estimate. However, the model’s predictive power is significant for positive ESP readings only.

A positive Earnings ESP is a strong predictor of an earnings beat, particularly when combined with a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold). Our research shows that stocks with this combination produce a positive surprise nearly 70% of the time, and a solid Zacks Rank actually increases the predictive power of Earnings ESP.

Please note that a negative Earnings ESP reading is not indicative of an earnings miss. Our research shows that it is difficult to predict an earnings beat with any degree of confidence for stocks with negative Earnings ESP readings and/or Zacks Rank of 4 (Sell) or 5 (Strong Sell).

How Have the Numbers Shaped Up for Wells Fargo?

For Wells Fargo, the Most Accurate Estimate is higher than the Zacks Consensus Estimate, suggesting that analysts have recently become bullish on the company’s earnings prospects. This has resulted in an Earnings ESP of +1.15%.

On the other hand, the stock currently carries a Zacks Rank of #3.

So, this combination indicates that Wells Fargo will most likely beat the consensus EPS estimate.

Does Earnings Surprise History Hold Any Clue?

While calculating estimates for a company’s future earnings, analysts often consider to what extent it has been able to match past consensus estimates. So, it’s worth taking a look at the surprise history for gauging its influence on the upcoming number.

For the last reported quarter, it was expected that Wells Fargo would post earnings of $0.95 per share when it actually produced earnings of $1.38, delivering a surprise of +45.26%.

Over the last four quarters, the company has beaten consensus EPS estimates four times.

Bottom Line

An earnings beat or miss may not be the sole basis for a stock moving higher or lower. Many stocks end up losing ground despite an earnings beat due to other factors that disappoint investors. Similarly, unforeseen catalysts help a number of stocks gain despite an earnings miss.

That said, betting on stocks that are expected to beat earnings expectations does increase the odds of success. This is why it’s worth checking a company’s Earnings ESP and Zacks Rank ahead of its quarterly release. Make sure to utilize our Earnings ESP Filter to uncover the best stocks to buy or sell before they’ve reported.

Wells Fargo appears a compelling earnings-beat candidate. However, investors should pay attention to other factors too for betting on this stock or staying away from it ahead of its earnings release.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Wells Fargo & Company (WFC): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/389793


Washington Federal (WAFD) Earnings Expected to Grow: Should You Buy?

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Washington Federal (WAFD) is expected to deliver a year-over-year increase in earnings on higher revenues when it reports results for the quarter ended September 2021. This widely-known consensus outlook gives a good sense of the company’s earnings picture, but how the actual results compare to these estimates is a powerful factor that could impact its near-term stock price.

– Zacks

The stock might move higher if these key numbers top expectations in the upcoming earnings report. On the other hand, if they miss, the stock may move lower.

While the sustainability of the immediate price change and future earnings expectations will mostly depend on management’s discussion of business conditions on the earnings call, it’s worth handicapping the probability of a positive EPS surprise.

Zacks Consensus Estimate

This holding company for Washington Federal Savings Bank is expected to post quarterly earnings of $0.63 per share in its upcoming report, which represents a year-over-year change of +40%.

Revenues are expected to be $144.4 million, up 14.7% from the year-ago quarter.

Estimate Revisions Trend

The consensus EPS estimate for the quarter has remained unchanged over the last 30 days. This is essentially a reflection of how the covering analysts have collectively reassessed their initial estimates over this period.

Investors should keep in mind that the direction of estimate revisions by each of the covering analysts may not always get reflected in the aggregate change.

Price, Consensus and EPS Surprise

Earnings Whisper

Estimate revisions ahead of a company’s earnings release offer clues to the business conditions for the period whose results are coming out. Our proprietary surprise prediction model — the Zacks Earnings ESP (Expected Surprise Prediction) — has this insight at its core.

The Zacks Earnings ESP compares the Most Accurate Estimate to the Zacks Consensus Estimate for the quarter; the Most Accurate Estimate is a more recent version of the Zacks Consensus EPS estimate. The idea here is that analysts revising their estimates right before an earnings release have the latest information, which could potentially be more accurate than what they and others contributing to the consensus had predicted earlier.

Thus, a positive or negative Earnings ESP reading theoretically indicates the likely deviation of the actual earnings from the consensus estimate. However, the model’s predictive power is significant for positive ESP readings only.

A positive Earnings ESP is a strong predictor of an earnings beat, particularly when combined with a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold). Our research shows that stocks with this combination produce a positive surprise nearly 70% of the time, and a solid Zacks Rank actually increases the predictive power of Earnings ESP.

Please note that a negative Earnings ESP reading is not indicative of an earnings miss. Our research shows that it is difficult to predict an earnings beat with any degree of confidence for stocks with negative Earnings ESP readings and/or Zacks Rank of 4 (Sell) or 5 (Strong Sell).

How Have the Numbers Shaped Up for Washington Federal?

For Washington Federal, the Most Accurate Estimate is the same as the Zacks Consensus Estimate, suggesting that there are no recent analyst views which differ from what have been considered to derive the consensus estimate. This has resulted in an Earnings ESP of 0%.

On the other hand, the stock currently carries a Zacks Rank of #3.

So, this combination makes it difficult to conclusively predict that Washington Federal will beat the consensus EPS estimate.

Does Earnings Surprise History Hold Any Clue?

Analysts often consider to what extent a company has been able to match consensus estimates in the past while calculating their estimates for its future earnings. So, it’s worth taking a look at the surprise history for gauging its influence on the upcoming number.

For the last reported quarter, it was expected that Washington Federal would post earnings of $0.52 per share when it actually produced earnings of $0.61, delivering a surprise of +17.31%.

Over the last four quarters, the company has beaten consensus EPS estimates four times.

Bottom Line

An earnings beat or miss may not be the sole basis for a stock moving higher or lower. Many stocks end up losing ground despite an earnings beat due to other factors that disappoint investors. Similarly, unforeseen catalysts help a number of stocks gain despite an earnings miss.

That said, betting on stocks that are expected to beat earnings expectations does increase the odds of success. This is why it’s worth checking a company’s Earnings ESP and Zacks Rank ahead of its quarterly release. Make sure to utilize our Earnings ESP Filter to uncover the best stocks to buy or sell before they’ve reported.

Washington Federal doesn’t appear a compelling earnings-beat candidate. However, investors should pay attention to other factors too for betting on this stock or staying away from it ahead of its earnings release.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Washington Federal, Inc. (WAFD): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/389796


Analysts Estimate Sleep Number (SNBR) to Report a Decline in Earnings: What to Look Out for

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Sleep Number (SNBR) is expected to deliver a year-over-year decline in earnings on higher revenues when it reports results for the quarter ended September 2021. This widely-known consensus outlook gives a good sense of the company’s earnings picture, but how the actual results compare to these estimates is a powerful factor that could impact its near-term stock price.

– Zacks

The earnings report might help the stock move higher if these key numbers are better than expectations. On the other hand, if they miss, the stock may move lower.

While the sustainability of the immediate price change and future earnings expectations will mostly depend on management’s discussion of business conditions on the earnings call, it’s worth handicapping the probability of a positive EPS surprise.

Zacks Consensus Estimate

This seller of beds, mattresses and bedding products is expected to post quarterly earnings of $1.43 per share in its upcoming report, which represents a year-over-year change of -20.1%.

Revenues are expected to be $566.75 million, up 6.7% from the year-ago quarter.

Estimate Revisions Trend

The consensus EPS estimate for the quarter has remained unchanged over the last 30 days. This is essentially a reflection of how the covering analysts have collectively reassessed their initial estimates over this period.

Investors should keep in mind that an aggregate change may not always reflect the direction of estimate revisions by each of the covering analysts.

Price, Consensus and EPS Surprise

Earnings Whisper

Estimate revisions ahead of a company’s earnings release offer clues to the business conditions for the period whose results are coming out. Our proprietary surprise prediction model — the Zacks Earnings ESP (Expected Surprise Prediction) — has this insight at its core.

The Zacks Earnings ESP compares the Most Accurate Estimate to the Zacks Consensus Estimate for the quarter; the Most Accurate Estimate is a more recent version of the Zacks Consensus EPS estimate. The idea here is that analysts revising their estimates right before an earnings release have the latest information, which could potentially be more accurate than what they and others contributing to the consensus had predicted earlier.

Thus, a positive or negative Earnings ESP reading theoretically indicates the likely deviation of the actual earnings from the consensus estimate. However, the model’s predictive power is significant for positive ESP readings only.

A positive Earnings ESP is a strong predictor of an earnings beat, particularly when combined with a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold). Our research shows that stocks with this combination produce a positive surprise nearly 70% of the time, and a solid Zacks Rank actually increases the predictive power of Earnings ESP.

Please note that a negative Earnings ESP reading is not indicative of an earnings miss. Our research shows that it is difficult to predict an earnings beat with any degree of confidence for stocks with negative Earnings ESP readings and/or Zacks Rank of 4 (Sell) or 5 (Strong Sell).

How Have the Numbers Shaped Up for Sleep Number?

For Sleep Number, the Most Accurate Estimate is the same as the Zacks Consensus Estimate, suggesting that there are no recent analyst views which differ from what have been considered to derive the consensus estimate. This has resulted in an Earnings ESP of 0%.

On the other hand, the stock currently carries a Zacks Rank of #3.

So, this combination makes it difficult to conclusively predict that Sleep Number will beat the consensus EPS estimate.

Does Earnings Surprise History Hold Any Clue?

Analysts often consider to what extent a company has been able to match consensus estimates in the past while calculating their estimates for its future earnings. So, it’s worth taking a look at the surprise history for gauging its influence on the upcoming number.

For the last reported quarter, it was expected that Sleep Number would post earnings of $1.11 per share when it actually produced earnings of $0.88, delivering a surprise of -20.72%.

Over the last four quarters, the company has beaten consensus EPS estimates three times.

Bottom Line

An earnings beat or miss may not be the sole basis for a stock moving higher or lower. Many stocks end up losing ground despite an earnings beat due to other factors that disappoint investors. Similarly, unforeseen catalysts help a number of stocks gain despite an earnings miss.

That said, betting on stocks that are expected to beat earnings expectations does increase the odds of success. This is why it’s worth checking a company’s Earnings ESP and Zacks Rank ahead of its quarterly release. Make sure to utilize our Earnings ESP Filter to uncover the best stocks to buy or sell before they’ve reported.

Sleep Number doesn’t appear a compelling earnings-beat candidate. However, investors should pay attention to other factors too for betting on this stock or staying away from it ahead of its earnings release.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Sleep Number Corporation (SNBR): Free Stock Analysis Report
 
To read this article on Zacks.com click here.

https://www.entrepreneur.com/article/389794


Analysts Estimate Progressive (PGR) to Report a Decline in Earnings: What to Look Out for

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

The market expects Progressive (PGR) to deliver a year-over-year decline in earnings on higher revenues when it reports results for the quarter ended September 2021. This widely-known consensus outlook is important in assessing the company’s earnings picture, but a powerful factor that might influence its near-term stock price is how the actual results compare to these estimates.

– Zacks

The stock might move higher if these key numbers top expectations in the upcoming earnings report. On the other hand, if they miss, the stock may move lower.

While management’s discussion of business conditions on the earnings call will mostly determine the sustainability of the immediate price change and future earnings expectations, it’s worth having a handicapping insight into the odds of a positive EPS surprise.

Zacks Consensus Estimate

This insurer is expected to post quarterly earnings of $0.33 per share in its upcoming report, which represents a year-over-year change of -82.4%.

Revenues are expected to be $12.4 billion, up 19.1% from the year-ago quarter.

Estimate Revisions Trend

The consensus EPS estimate for the quarter has been revised 5.17% higher over the last 30 days to the current level. This is essentially a reflection of how the covering analysts have collectively reassessed their initial estimates over this period.

Investors should keep in mind that the direction of estimate revisions by each of the covering analysts may not always get reflected in the aggregate change.

Price, Consensus and EPS Surprise

Earnings Whisper

Estimate revisions ahead of a company’s earnings release offer clues to the business conditions for the period whose results are coming out. This insight is at the core of our proprietary surprise prediction model — the Zacks Earnings ESP (Expected Surprise Prediction).

The Zacks Earnings ESP compares the Most Accurate Estimate to the Zacks Consensus Estimate for the quarter; the Most Accurate Estimate is a more recent version of the Zacks Consensus EPS estimate. The idea here is that analysts revising their estimates right before an earnings release have the latest information, which could potentially be more accurate than what they and others contributing to the consensus had predicted earlier.

Thus, a positive or negative Earnings ESP reading theoretically indicates the likely deviation of the actual earnings from the consensus estimate. However, the model’s predictive power is significant for positive ESP readings only.

A positive Earnings ESP is a strong predictor of an earnings beat, particularly when combined with a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold). Our research shows that stocks with this combination produce a positive surprise nearly 70% of the time, and a solid Zacks Rank actually increases the predictive power of Earnings ESP.

Please note that a negative Earnings ESP reading is not indicative of an earnings miss. Our research shows that it is difficult to predict an earnings beat with any degree of confidence for stocks with negative Earnings ESP readings and/or Zacks Rank of 4 (Sell) or 5 (Strong Sell).

How Have the Numbers Shaped Up for Progressive?

For Progressive, the Most Accurate Estimate is lower than the Zacks Consensus Estimate, suggesting that analysts have recently become bearish on the company’s earnings prospects. This has resulted in an Earnings ESP of -34.82%.

On the other hand, the stock currently carries a Zacks Rank of #3.

So, this combination makes it difficult to conclusively predict that Progressive will beat the consensus EPS estimate.

Does Earnings Surprise History Hold Any Clue?

While calculating estimates for a company’s future earnings, analysts often consider to what extent it has been able to match past consensus estimates. So, it’s worth taking a look at the surprise history for gauging its influence on the upcoming number.

For the last reported quarter, it was expected that Progressive would post earnings of $1.17 per share when it actually produced earnings of $1.51, delivering a surprise of +29.06%.

Over the last four quarters, the company has beaten consensus EPS estimates three times.

Bottom Line

An earnings beat or miss may not be the sole basis for a stock moving higher or lower. Many stocks end up losing ground despite an earnings beat due to other factors that disappoint investors. Similarly, unforeseen catalysts help a number of stocks gain despite an earnings miss.

That said, betting on stocks that are expected to beat earnings expectations does increase the odds of success. This is why it’s worth checking a company’s Earnings ESP and Zacks Rank ahead of its quarterly release. Make sure to utilize our Earnings ESP Filter to uncover the best stocks to buy or sell before they’ve reported.

Progressive doesn’t appear a compelling earnings-beat candidate. However, investors should pay attention to other factors too for betting on this stock or staying away from it ahead of its earnings release.

Zacks’ Top Picks to Cash in on Artificial Intelligence

This world-changing technology is projected to generate $100s of billions by 2025. From self-driving cars to consumer data analysis, people are relying on machines more than we ever have before. Now is the time to capitalize on the 4th Industrial Revolution. Zacks’ urgent special report reveals 6 AI picks investors need to know about today.

See 6 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
The Progressive Corporation (PGR): Free Stock Analysis Report
 
To read this article on Zacks.com click here.

https://www.entrepreneur.com/article/389795


Buy These 5 Large-Cap Stocks for Their Dividends

Attempting to guess which way the market will move is a difficult exercise in the best of times. And when things are as volatile as they are now, your guess is probably as good as mine.

– Zacks

Take China, for example. That government is cracking down on tech companies, bailing out its construction giant, issuing directives to bring down manufacturing and a host of other things. And with the way supply chains are connected these days, there will of course be an impact in the rest of the world, no matter what it does.

China is also the manufacturing hub of so many different things that its decisions to buy or sell commodities also has a significant impact on global markets. And since we don’t really know if there are more actions in store, a bit of China-driven volatility and risk will be there.

Then there’s the Fed that has been supportive so far. But conversations on tapering and interest rate hikes have escalated, and this of course has an impact on sentiments. Particularly when companies appear to be losing sales because of supply chain issues and when input cost inflation is set to increase further, partly driven by sky-high energy prices. And given all this, we are seeing steadily rising inflation, however temporary it may be.

The third point is to do with the earnings season. A good earnings season usually lifts the market. But with the supply chains being what they’ve been, we could be in for some negative surprises. Analyst estimates don’t look too bad right now with third quarter earnings for the S&P 500 expected to be up 26.1% year over year, on revenue that’s expected to grow 13.8%.

This is nothing to scoff at, but it’s worth noting that it follows a second quarter earnings increase of 95.3% on revenue growth of 25.3%. So it’s possible that investors will be disappointed with this showing, even if we don’t see the negative surprises, which will very likely be there considering that supply side issues have piled up rather than alleviated through the quarter.

And finally, we have COVID, which is another unguessable phenomenon. It continues to create production issues in Asia and consumption issues in the U.S., although there have been some reports that restaurants are holding up.

So that’s where we’re at right now, and although all these problems will likely blow over, it’s better to adopt a safe strategy, if we still want to buy stocks.

Today’s recommendations are therefore based on large cap safe plays that have a steady and rising dividend, as well as solid cash flows to ensure continuity in the dividend stream.

Zacks metrics like a Zacks Buy or Strong Buy Rank, Value and Growth Scores of A or B, and an attractive Zacks Industry Rank outline the safety parameter. The estimated earnings growth is indicative of positive current prospects. The dividend stream ensures that returns for investors even if all else fails.

Additionally, all these stocks have an attractive valuation.

Best Buy Co., Inc. BBY

Best Buy is a multinational specialty retailer of consumer electronics, home office products, entertainment software, communication, food preparation, wellness, heath, security, appliances and related services. The company operates in the United States and Canada.

The Zacks Rank #1 (Strong Buy) stock with value and Growth Scores of A belongs to the Retail – Consumer Electronics industry, which is in the top 10% of Zacks-classified industries.

The company is expected to grow its earnings 25.9% this year. Its dividend yields 2.65% and its 5-year historical dividend growth is 19.0%.

Valuation multiples of 10.6X earnings and 0.50X sales indicates that investors are undervaluing both its revenue and earnings.

C.H. Robinson Worldwide, Inc. CHRW

C.H. Robinson operates as an asset-light logistics company offering freight transportation services and logistic solutions to companies across a range of industries. It has both single-shipment as well as comprehensive and integrated relationships.

The scale of its operations is evident in the 19 million shipments it handled in 2020 that served more than 105,000 customers. This was achieved through 73,000 contracted transportation companies, including motor carriers, railroads (mainly intermodal service providers), air and ocean carriers.

The Zacks Rank #2 (Buy) stock with Value and Growth Scores of B operates in the Transportation – Services industry (top 24% of 250+ Zacks-classified industries).

Currently, its earnings are expected to grow 45.4%. Its dividend yields 2.36%. The dividend has grown 3.5% over the past five years.

The shares are currently trading at a P/E multiple of 16.0X and a P/S multiple of 0.60X, both of which support appreciation in share prices.

Deutsche Post AG DPSGY

One of the world’s largest logistics services companies, Deutsche Post operates in Germany, Europe, America, Asia Pacific and other regions. Its Post-eCommerce-Parcel division offers various mail delivery services; the Express division offers time-definite international (TDI) shipments of urgent documents and goods; Global Forwarding transports goods by rail, road, air and sea; the Supply Chain division warehousing, distribution, managed transport, value-added services and supply chain management and consulting services; the eCommerce Solutions segment provides parcel delivery and cross-border non-TDI services.

The supply chain issues stemming from port congestion and driver shortages impacts the company just as it does other transportation companies. But the company is seeing pricing strength, which is likely an offsetting factor in the current environment.

The Zacks Rank #2 stock with Value and Growth Scores of A also operates in the Transportation – Services industry.

It is currently expected to grow its 2021 earnings by 67.0%. The company’s dividend yields 1.87% at current share prices. The dividend has grown 1.0% over the last five years.

Its P/E valuation of 13.9X and P/S valuation of 0.88X indicate upside potential in share prices.

Steel Dynamics, Inc. STLD

Steel Dynamics is among the leading steel producers and metal recyclers in the United States. It is also extremely diversified with a vast range of specialty steel products. It currently has steelmaking and coating capacity of more than 11 million tons.

The Zacks Rank #1 stock with value and Growth Scores of B operates in the Steel – Producers industry (top 24%).

The company’s earnings are set to grow 431.0% this year. Its dividend has grown 15.0% over the last five years and now yields 1.78%.

At 3.9X earnings and 0.92X sales, the shares are definitely worth considering.

ITOCHU Corp. ITOCY

This is a trading company with domestic trading operations in Japan, as well as import and export operations. It deals in textiles, machinery, information and communications technology, aerospace, electronics, energy, metals, minerals, chemicals, forest products, general merchandise, food, finance, realty, insurance, etc.

The Zacks Rank #2 stocks with Value and Growth Scores of A and B, respectively operates in the Retail – Miscellaneous industry (top 40%).

Its earnings are expected to grow 69.8% this year. Its dividend yields 2.25% and it has grown 20.9% over the last five years.

Additionally, Its 6.5X earnings and 0.43X sales indicates an extremely cheap valuation.

One-Month Price Performance

Zacks Investment ResearchImage Source: Zacks Investment Research

Zacks’ Top Picks to Cash in on Artificial Intelligence

In 2021, this world-changing technology is projected to generate $327.5 billion in revenue. Now Shark Tank star and billionaire investor Mark Cuban says AI will create “the world’s first trillionaires.” Zacks’ urgent special report reveals 3 AI picks investors need to know about today.

See 3 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Steel Dynamics, Inc. (STLD): Free Stock Analysis Report
 
Best Buy Co., Inc. (BBY): Free Stock Analysis Report
 
C.H. Robinson Worldwide, Inc. (CHRW): Free Stock Analysis Report
 
Deutsche Post AG (DPSGY): Free Stock Analysis Report
 
Itochu Corp. (ITOCY): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/389495


Regions Financial (RF) to Acquire CRE Lender Sabal Capital

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

Regions Financial Corporation’s RF subsidiary, Regions Bank, has agreed to acquire Sabal Capital Partners, LLC, a diversified financial services firm leveraging tech-driven origination and servicing platform for the small-balance commercial real estate market. Closing of the deal, expected in fourth-quarter 2021, is subject to the satisfaction of certain governmental agencies and government-sponsored enterprises’ consents as well as customary closing conditions.

– Zacks

Sabal is one of the culminating originators of the Fannie Mae and Freddie Mac small-balance commercial real estate loans, and has a strong presence in the non-agency commercial mortgage-backed securities loan origination. Sabal has originated financing worth nearly $6 billion across the United States since its inception and retains its current servicing portfolio worth $5 billion.

The acquisition does not include Sabal’s investment management business and the investment funds handled by Stone Point Capital LLC. Regions will uphold Sabal’s flagship offices in Irvine and Pasadena, California as well as New York City. When linked with Regions’ Real Estate Capital Markets’ current production offices, the consolidated platform will have 20 production offices nationwide.

While the financial terms of the transaction have not been disclosed, the acquisition of Sabal is likely to expand Regions’ real estate solutions across the full gamut of agency offerings. Regions Financial will be better poised to further build on the client base and deliver augmented range of agency as well as non-agency real estate lending options.

Sabal aids clients via the company’s proprietary avant-garde SNAP platform, a tool developed to improve the lending and communications processes with clients, and its investor base. Sabal capitalizes on tools, such as real-time commercial property financing scenarios, seamless online loan applications, and technology enabling clients, to scan loan progress through the deal’s closure.

Regions has a proven track record of delivering economical options for clients in the small- and middle-market commercial real estate space, while retaining a judicious approach to risk management. By joining forces, the companies can make a larger impact on their new and existing client base through the integration of technology-powered services, years of experience as well as strategic decision making.

Joel Stephens, head of Capital Markets for Regions Bank, said, “Sabal’s industry-leading technology platform and its leadership in the small-balance commercial real estate arena make the company a great match for Regions. Our current affordable and large-balance Fannie Mae and Freddie Mac products, combined with Sabal’s small-balance agency capabilities, will allow Regions to offer real estate solutions across the full spectrum of agency offerings. We look forward to working together to provide superior service to more real estate clients across the country.”

The acquisition boosts Regions’ strategy of acquiring businesses that facilitate it to reinforce the current client relationships, while also drawing new ones, who are attracted by the services, competencies, and technologies imparted by companies such as Sabal.

Regions continues to explore opportunities for bolt-on acquisitions, primarily in mortgage servicing rights, and adding capabilities in the wealth management unit. Last month, Regions Bank’s Real Estate Capital Markets division became an approved Freddie Mac Multifamily Conventional and Targeted Affordable Housing Optigo lender. The latest approval further enhances the company’s lending suite within its Capital Markets division.

The company is also currently working on a digital advisory solution, which is likely to be deployed in late 2021 or early 2022. As it is committed to diversifying its revenue streams and meeting customer needs through diverse services, we believe such endeavors will support the company’s growth prospects over the long term.

Shares of Regions have gained 3.6% in the past six months, outperforming 2.7% growth of the industry it belongs to.

Zacks Investment ResearchImage Source: Zacks Investment Research

Currently, the company carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.

Similar Expansion Efforts by Other Banks

At present, banks have resorted to mergers and acquisitions to dodge the heightened costs of investments in technology and counter lower rates.

Recently, U.S. Bancorp USB had entered into a definitive agreement to acquire MUFG Union Bank’s core retail banking operations from Mitsubishi UFJ Financial Group MUFG for a cash-and-stock transaction valued at $8 billion, in a bid to boost its presence on the West Coast. The deal’s closure, expected in the first-half of 2022, is subject to the satisfaction of customary closing conditions and regulatory approvals. No shareholder approvals are required from both companies.

Southern Missouri Bancorp Inc. SMBC announced that it will acquire Fortune Financial Corporation in a stock-and-cash transaction worth $30 million.

Zacks’ Top Picks to Cash in on Artificial Intelligence

In 2021, this world-changing technology is projected to generate $327.5 billion in revenue. Now Shark Tank star and billionaire investor Mark Cuban says AI will create “the world’s first trillionaires.” Zacks’ urgent special report reveals 3 AI picks investors need to know about today.

See 3 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Regions Financial Corporation (RF): Free Stock Analysis Report
 
U.S. Bancorp (USB): Free Stock Analysis Report
 
Valley National Bancorp (VLY): Free Stock Analysis Report
 
Southern Missouri Bancorp, Inc. (SMBC): Free Stock Analysis Report
 
Mitsubishi UFJ Financial Group, Inc. (MUFG): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/389496


Gap (GPS) Embraces CB4 to Enhance Customer Experience & Sales

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

The Gap, Inc. GPS is making concerted efforts to strengthen its digital business via advancements in technology besides boosting assortments across its brands. In a latest move, to enhance its digital portal, the clothing retailer bought Context-Based 4 Casting Ltd. (CB4), which is a renowned New York and Tel Aviv-based AI platform.
CB4 uses the latest AI technology and machine-learning tools to transform its retail operations to lift sales and enrich customer experience through analytical research and demand sensing. The CB4 team will join the company as full-time employees. We note that the latest transaction was brokered by Gap’s Strategic Growth Office. This division taps growth opportunities and looks forward to new capabilities across its brands’ portfolio.
The CB4 technology provides recommendations to boost new sales and satisfy customers. The technology was implemented by retailers like Levi’s LEVI, Urban Outfitters URBN, Lidl and Kum & Go. We believe that investment in CB4 will pay off in the future by better understanding consumer insights and greatly increasing sales and profits.

– Zacks

More on Digital Drive

Gap has been making significant investments in technology to bring innovations after it moved to the cloud last October. The company had earlier acquired Drapr, which is an e-commerce startup with 3D-fit technology and virtual fitting rooms to lower online returns.
Gap rolled out AthletaWell, which is an immersive digital platform created to develop loyalty and a community of empowered women. Customers can also engage in conversations with vetted experts on subjects like outfitting, fitness, mental health and body positivity. They can also join interactive workshops on guided meditation and avail premium content from partners like obe Fitness. The obe fitness is a digital fitness platform and partners Gap’s Athleta to convey entertainment, pop culture and design to fitness.
The company is on track to embrace a try fast, learn fast, think big mentality to offer a seamless customer experience. With the debut of Yeezy Gap, it rolled out a modern out-of-the-box online experience. Gap’s Athleta and Old Navy Instagram shopping file proved to be immensely successful while the company’s work-on-site speed and inventory availability are contributing to its better Net Promoter Score.
Gap has been experiencing substantial growth in its scaled digital business since the onset of the pandemic. During second-quarter fiscal 2021, digital sales surged 65% from the second-quarter fiscal 2019 tally, accounting for 33% of total sales in the reported quarter.
Continued growth in e-commerce business hugely bolstered the company’s consolidated sales as well as gains in its Gap, Old Navy and Athleta brands. Online business is benefiting from the company’s dominant omni-channel strength and scaled distribution network. Going forward, the e-commerce momentum is likely to stay and keep driving its overall results.

Price Performance

Contributions from the e-commerce wing and other strategic efforts have helped this currently Zacks Rank #1 (Strong Buy) stock return 18.3% so far in the year against the industry’s 1.9% dip. You can see the complete list of today’s Zacks #1 Rank stocks here.

Zacks Investment ResearchImage Source: Zacks Investment Research

Another stock in the same space that is worth a look is Abercrombie ANF, which has a long-term earnings growth rate of 18% and a Zacks Rank of 1 at present.

Zacks’ Top Picks to Cash in on Artificial Intelligence

In 2021, this world-changing technology is projected to generate $327.5 billion in revenue. Now Shark Tank star and billionaire investor Mark Cuban says AI will create “the world’s first trillionaires.” Zacks’ urgent special report reveals 3 AI picks investors need to know about today.

See 3 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
Abercrombie & Fitch Company (ANF): Free Stock Analysis Report
 
The Gap, Inc. (GPS): Free Stock Analysis Report
 
Urban Outfitters, Inc. (URBN): Free Stock Analysis Report
 
Levi Strauss & Co. (LEVI): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/389497


Allstate (ALL) on Track to Shed Its Life and Annuity Business

You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks

The Allstate Corporation ALL has inched a step closer in the process to sell its Allstate Life Insurance Company of New York (ALNY) to Wilton Re for approximately $400 million with the receipt of regulatory approval.

– Zacks

The sale of ALNY is in sync with the company’s long-term strategy to move away from life and annuity business and focus on other businesses, such as personal property-liability and protection services.

In a separate move, earlier this year, Allstate agreed to divest Allstate Life Insurance Company to Everlake US Holdings Company. This transaction is expected to close in 2021, subject to regulatory approval and other closing conditions.

These deals will help the company completely exit the domain of traditional life and annuity businesses. Proceeds from these transactions will be deployed to growing core business.

Allstate’s strategy of increasing personal profit liability market share and expanding protection solutions was visible in the recent quarterly results.  Property-liability market share increased by approximately one percentage point owing to the acquisition of National General made in January earlier this year. The deal strengthened the company’s strategic position in the independent agent distribution channel. The move advances its policy to increase its market share in personal property-liability, which actually inched up 1%.

National General has a strong position in the higher risk or “non-standard” auto insurance space. The acquisition will be accretive to Allstate’s earnings per share and its ROE will reflect significant cost synergies. The company expects a high-single digit earnings accretion in the first year post close. It also anticipates ROE accretion of approximately 100 bps, mirroring substantial cost efficiency.

Later this year, Allstate expects to launch standard auto and homeowners insurance offerings on the National General platform and intends to place the same in less than two years.
The company is on track to acquire SafeAuto soon. This deal will leverage its recently-closed acquisition of National General. It will add capabilities and distribution to the acquired entity’s direct-to-consumer non-standard auto insurance operations..

Allstate is making concerted efforts to expand its Protection Services business (previously known as Service business), which provides diversification benefits. To this end, it acquired SquareTrade in 2017, a provider of protection plans for mobile phones, consumer electronics and appliances.

The company also acquired PlumChoice in 2018, a leading provider of cloud and technical support services to consumers and small businesses. In February 2019, iCracked was acquired, which expanded SquareTrade’s protection offerings. These buyouts will expand Allstate’s Protection Services business, which improved revenues by 7.3% and 16.6% in 2019 and 2020, respectively.

It is also overhauling its operations by investing in technology. This should increase its efficiency and save operational costs.

We believe, the company is firing on all cylinders to boost growth and that the catastrophe losses will not dent its profitability.

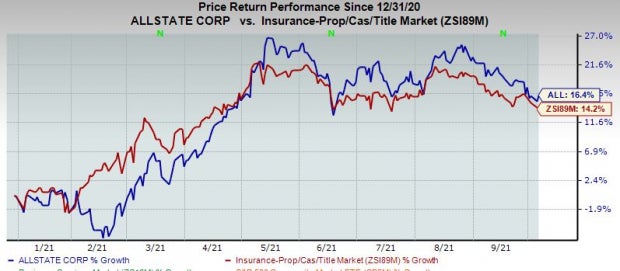
Year to date, shares of the company have gained 15.2% compared with the industry‘s growth of 14.2%.


Zacks Investment ResearchImage Source: Zacks Investment Research

The stock carries a Zacks Rank #3 (Hold) at present. You can see the complete list of today’s Zacks #1 Rank stocks here.

Some better-ranked stocks in the insurance space are American Financial Group Inc. AFG, RLI Corp. RLI and ProAssurance Corporation PRA, each stock currently sporting a Zacks Rank #1 (Strong Buy).

Earnings of both RLI Corp. and American Financial Group beat estimates in the trailing four quarters by 155.2% and 52.82%, respectively, on average.

ProAssurance Corporation’s bottom line beat estimates in three of the last four quarters (missing the mark in one) by 200.6%, on average.
 

Zacks’ Top Picks to Cash in on Artificial Intelligence

In 2021, this world-changing technology is projected to generate $327.5 billion in revenue. Now Shark Tank star and billionaire investor Mark Cuban says AI will create “the world’s first trillionaires.” Zacks’ urgent special report reveals 3 AI picks investors need to know about today.

See 3 Artificial Intelligence Stocks With Extreme Upside Potential>>

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
RLI Corp. (RLI): Free Stock Analysis Report
 
The Allstate Corporation (ALL): Free Stock Analysis Report
 
ProAssurance Corporation (PRA): Free Stock Analysis Report
 
American Financial Group, Inc. (AFG): Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

https://www.entrepreneur.com/article/389498