Tilray (TLRY) to Report Q1 Earnings: What’s in the Cards?
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
Tilray, Inc. TLRY will release financial results for the first quarter of fiscal 2022 (ended Aug 31, 2021), before market open on Oct 7.
– Zacks
Let us see how things have shaped up prior to this announcement.
Factors at Play
Tilray is a leading global cannabis-lifestyle and consumer packaged goods company.
In May 2021, the company completed its previously announced business combination with Aphria. Each Aphria shareholder received 0.8381 of a Tilray share for each Aphria common share held on Apr 30, 2021. The consolidated entity is now one of the leading cannabis-focused consumer packaged goods companies with the largest global footprint in the industry.
Revenues increased 25% in the fourth quarter of 2021, driven by 36% growth in net cannabis revenues. The same trends are likely to have prevailed in the fiscal first quarter.
Tilray has been gaining market share nationally in Canada month over month since April 2021. The combination with Aphria strengthened its infrastructure with the addition of SweetWater, a leading cannabis lifestyle branded craft brewer.
In July 2021, SweetWater announced the launch of 420 Imperial IPA, the first-line extension off of its flagship 420 brand. In the same month, the company announced the completion and shipment of the first successful EU GMP-certified medical cannabis harvest grown in Germany for German distribution. In June 2021, Tilray announced unveiling the medical cannabis brand Symbios. These factors are expected to have driven revenues in the quarter under review.
The new company expects to generate approximately $80 million of annual cost synergies within 18 months and plans to achieve cost synergies in the key areas of cultivation and production, cannabis and product purchasing, sales and marketing, and corporate expenses. To date, Tilray has achieved $35 million worth of synergies.
Earnings Whispers
Our proven model does not predict an earnings beat for Tilray this reporting cycle. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. Unfortunately, that is not the case here as you will see below. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Earnings ESP: Tilray has an Earnings ESP of +35.72%.
Zacks Rank: Tilray currently carries a Zacks Rank #4 (Sell).
Share Price Performance
Tilray’s stock has surged 32.6% in the year so far against the industry’s decline of 17%.
Image Source: Zacks Investment Research
Stocks to Consider
Here are a few stocks worth considering as our model shows that these have the right combination of elements to beat on earnings this season.
GlaxoSmithKlineGSK has an Earnings ESP of +2.52% and a Zacks Rank #3 at present.
Merck MRK has an Earnings ESP of +5.51% and a Zacks Rank of 3 at present.
Zacks’ Top Picks to Cash in on Artificial Intelligence
In 2021, this world-changing technology is projected to generate $327.5 billion in revenue. Now Shark Tank star and billionaire investor Mark Cuban says AI will create “the world’s first trillionaires.” Zacks’ urgent special report reveals 3 AI picks investors need to know about today.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Will Industrial ETFs Make Good Bets? Let’s Find Out
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
The industrial sector has been attracting investor attention as the gradual reopening of U.S. and global economies highlights brighter prospects. The S&P 500 Industrials index has already returned 29.3% in the past year compared with the S&P 500’s 28.9% rise.
– Zacks
The latest ISM Manufacturing Purchasing Managers’ Index (PMI) data for the United States paints a rosy picture for the industrial sector. The metric rose to 61.1% in September from 59.9% in August and surpassed forecasts of a decrease to 59.6, per a Reuters article. Any reading above 50% indicates expansion in U.S. manufacturing activities. Notably, the manufacturing sector, which makes up 12% of the U.S. economy, saw the reading rise forthe 16th consecutive month. 17 out of 18 manufacturing industries witnessed growth in September. The New Orders Index remained flat at 66.7%. The Supplier Deliveries Index reading was 73.4%, increasing 3.9 percentage points from the August figure.
In another positive development, optimism surrounding the news highlighting positive updates on Merck (MRK) and Ridgeback Biotherapeutics’ investigational oral antiviral medicine, molnupiravir, can support the sector. The update supports the spaces, which are expected to gain from the reopening of economies as the molnupiravir will help fight against COVID-19, if approved by the FDA.
Going on, U.S. consumer sentiment marginally improved despite rising concerns about coronavirus cases and inflation levels. The University of Michigan’s preliminary consumer sentiment inched up to 71 in September from 70.3 last month, per a BloombergQuint article.
The strength in consumer sentiment can be the primary driving force behind the solid performance by the consumer discretionary space as consumers are expected to splurge this holiday season after being restricted for more than a year.
The retail sales data has surprised investors pleasantly. According to a CNBC article, the metric inched up 0.7% sequentially in August 2021 against market expectations of a 0.8% decline. According to the Reuters article, online retail sales rose 5.3% last month after dropping 4.6% in July. There was an increase in clothing sales and building material and furniture.
The progress in coronavirus vaccine rollout presents a strong case in favor of a faster return to normalcy and economic recovery. The FDA has approved emergency use of a booster dose of the Pfizer Inc. (PFE) and BioNTech SE (BNTX) COVID-19 vaccine. President Joe Biden has also outlined an effective plan to accelerate the vaccination rate and control the coronavirus outbreak. He has made it mandatory for federal employees to get the COVID-19 vaccination, per a CNBC article. The Biden government will also issue guidelines to the Labor Department for imposing vaccine mandates for employers with more than 100 employees or running weekly tests.
Industrial ETFs in Focus
In the current scenario, we believe it is prudent to discuss ETFs that can gain from the growing optimism on the reopening U.S. economy:
The fund seeks to provide investment results that, before expenses, match the performance of the Industrial Select Sector Index. Its AUM is $17.37 billion and expense ratio is 0.12% (read: Fed Plans QE Taper: Time for Cyclical Sector ETFs?).
This fund offers exposure to the industrial sector and follows the MSCI US Investable Market Industrials 25/50 Index. Its AUM is $5.10 billion and expense ratio is 0.10% (read: Will ETFs Suffer as US Industrial Output Falls in August?).
The Fidelity MSCI Industrials Index ETF seeks to provide investment returns that match, before fees and expenses, the performance of the MSCI USA IMI Industrials Index. Its AUM is $819.6 million and expense ratio, 0.08%.
The iShares U.S. Industrials ETF seeks to track the investment results of the Russell 1000 Industrials 40 Act 15/22.5 Daily Capped Index. Its AUM is $1.60 billion and expense ratio is 0.41%, as stated in the prospectus.
5 Stocks Set to Double
Each was handpicked by a Zacks expert as the #1 favorite stock to gain +100% or more in 2021. Previous recommendations have soared +143.0%, +175.9%, +498.3% and +673.0%.
Most of the stocks in this report are flying under Wall Street radar, which provides a great opportunity to get in on the ground floor.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Here’s Why You Should Retain Myriad Genetics (MYGN) for Now
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
Myriad Genetics, Inc.MYGN is well poised for growth in the coming quarters on the ongoing strong recovery in testing volumes. The company’s recent launches of myRisk and RiskScore raise optimism. A strong solvency position is an added advantage. However, escalating expenses and foreign exchange fluctuations do not bode well for the stock.
– Zacks
Over the past year, the Zacks Rank #3 (Hold) stock has gained 139.4% against the 6.8% decline of the industry and the 29.7% rise of the S&P 500.
The renowned molecular diagnostic company has a market capitalization of $2.49 billion.
Over the past five years, the company’s earnings have seen a 171.7% decline, compared to the industry’s 14.4% rise and the S&P 500’s 2.8% increase. The expected growth rate for the next year is 153.9%, compared with the industry’s growth expectation of 1.4% and the S&P 500’s estimated 15.5% growth for the next year.
Image Source: Zacks Investment Research
Let’s delve deeper.
Factors in Play
Product Volume Rebound: We are upbeat about Myriad Genetics’ strong testing volumes in second-quarter 2021. Total testing volumes reflected a 70% improvement year over year and 8% growth on a sequential basis in this quarter. The sequential growth was largely led by strength in hereditary cancer, prenatal products, and GeneSight test in Mental Health.
Myriad Genetics reported 7% volume growth in hereditary cancer sequentially despite considerable alignment changes to most territories and a significant reduction in field sales force during April. Notably, the company’s tumor profiling volume grew 13% sequentially, driven by myChoice CDx and Prolaris.
Product Launches: Myriad Genetics’ slew of products launches raise optimism. During its earnings call for the second quarter of 2021, the company noted the launch of myRisk and RiskScore, which marked a significant step toward improving access to genetic testing.
The myRisk with RiskScore offers breast cancer risk assessment for all women not previously diagnosed with breast cancer. In February 2021, the company launched the new Vectra Cardiovascular Risk assessment that can predict the risk for cardiovascular events in patients with rheumatoid arthritis. The new test report provides a customized estimate of a patient’s one-year risk of rapid radiographic progression.
Strong Solvency: Myriad Genetics exited the second quarter of 2021 with cash and cash equivalents of $184.3 million. Short-term debt at the end of the second quarter of 2021 was $104 million. The figure is much lower than the quarter-end cash and cash equivalent and marketable investment securities. Moreover, the company had no long-term debt on its balance sheet at the end of the second quarter of 2021.
Downsides
Escalating Expenses: Myriad Genetics registered a significant rise in operating costs in second-quarter 2021. Research and development (R&D) expenses rose 12.1% year over year in the reported quarter. Meanwhile, selling, general and administrative (SG&A) expenses climbed 25.5%.
Foreign Exchange Headwinds: Myriad Genetics is susceptible to the risk of exchange rate fluctuations between foreign currencies and the U.S. dollar since the company receives a considerable portion of its revenues and pays a portion of its expenses in foreign currencies. The translation of these foreign currency-denominated transactions will result in decreased revenues and net income, and increased operating expenses, if dollar strengthens against foreign currencies.
Increasing Competition: Myriad Genetics is currently facing competition in its key BRACAnalysis market, according to management. The company expects competition to intensify in its current fields with recently observed advancements in technology. Further, Myriad Genetics anticipates that other companies may also launch molecular diagnostic tests, posing competition to its testing products and services.
Estimate Trend
Myriad Genetics has been witnessing a positive estimate revision trend for 2021. Over the past 90 days, the Zacks Consensus Estimate for its earnings has moved north to 13 cents.
The Zacks Consensus Estimate for its third-quarter 2021 revenues is pegged at $165.03 million, suggesting a 13.7% rise from the year-ago reported number.
Key Picks
A few better-ranked stocks from the Medical- Biomedical and Genetics industry include Horizon Therapeutics Public Ltd. Co.HZNP, Vertex Pharmaceuticals Inc.VRTX and Moderna, Inc.MRNA.
Vertex Pharmaceuticals, sporting a Zacks Rank #2 (Buy), has a long-term earnings growth rate of 9.8%.
Moderna, carrying a Zacks Rank #2, has a long-term earnings growth rate of 29.1%.
5 Stocks Set to Double
Each was handpicked by a Zacks expert as the #1 favorite stock to gain +100% or more in 2021. Previous recommendations have soared +143.0%, +175.9%, +498.3% and +673.0%.
Most of the stocks in this report are flying under Wall Street radar, which provides a great opportunity to get in on the ground floor.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
ViacomCBS (VIAC) Dips More Than Broader Markets: What You Should Know
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
ViacomCBS (VIAC) closed the most recent trading day at $39.11, moving -1.98% from the previous trading session. This change lagged the S&P 500’s 1.3% loss on the day.
– Zacks
Prior to today’s trading, shares of the company had lost 3.34% over the past month. This has lagged the Consumer Discretionary sector’s loss of 2.9% and was narrower than the S&P 500’s loss of 3.58% in that time.
VIAC will be looking to display strength as it nears its next earnings release. In that report, analysts expect VIAC to post earnings of $0.76 per share. This would mark a year-over-year decline of 16.48%. Meanwhile, the Zacks Consensus Estimate for revenue is projecting net sales of $6.59 billion, up 7.76% from the year-ago period.
Looking at the full year, our Zacks Consensus Estimates suggest analysts are expecting earnings of $3.94 per share and revenue of $28.09 billion. These totals would mark changes of -6.19% and +8.3%, respectively, from last year.
Investors might also notice recent changes to analyst estimates for VIAC. These revisions typically reflect the latest short-term business trends, which can change frequently. With this in mind, we can consider positive estimate revisions a sign of optimism about the company’s business outlook.
Research indicates that these estimate revisions are directly correlated with near-term share price momentum. Investors can capitalize on this by using the Zacks Rank. This model considers these estimate changes and provides a simple, actionable rating system.
The Zacks Rank system ranges from #1 (Strong Buy) to #5 (Strong Sell). It has a remarkable, outside-audited track record of success, with #1 stocks delivering an average annual return of +25% since 1988. Within the past 30 days, our consensus EPS projection has moved 0.3% higher. VIAC is holding a Zacks Rank of #3 (Hold) right now.
Digging into valuation, VIAC currently has a Forward P/E ratio of 10.12. This represents a discount compared to its industry’s average Forward P/E of 32.39.
The Film and Television Production and Distribution industry is part of the Consumer Discretionary sector. This group has a Zacks Industry Rank of 113, putting it in the top 45% of all 250+ industries.
The Zacks Industry Rank gauges the strength of our individual industry groups by measuring the average Zacks Rank of the individual stocks within the groups. Our research shows that the top 50% rated industries outperform the bottom half by a factor of 2 to 1.
You can find more information on all of these metrics, and much more, on Zacks.com.
5 Stocks Set to Double
Each was handpicked by a Zacks expert as the #1 favorite stock to gain +100% or more in 2021. Previous recommendations have soared +143.0%, +175.9%, +498.3% and +673.0%.
Most of the stocks in this report are flying under Wall Street radar, which provides a great opportunity to get in on the ground floor.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Weyerhaeuser (WY) Stock Moves -0.14%: What You Should Know
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
In the latest trading session, Weyerhaeuser (WY) closed at $35.72, marking a -0.14% move from the previous day. This change was narrower than the S&P 500’s daily loss of 1.3%.
– Zacks
Prior to today’s trading, shares of the timber and paper products company had lost 2.37% over the past month. This has was narrower than the Construction sector’s loss of 6.52% and the S&P 500’s loss of 3.58% in that time.
Wall Street will be looking for positivity from WY as it approaches its next earnings report date. This is expected to be October 29, 2021. On that day, WY is projected to report earnings of $0.57 per share, which would represent year-over-year growth of 9.62%. Meanwhile, the Zacks Consensus Estimate for revenue is projecting net sales of $2.36 billion, up 11.61% from the year-ago period.
For the full year, our Zacks Consensus Estimates are projecting earnings of $3.20 per share and revenue of $10.11 billion, which would represent changes of +148.06% and +34.19%, respectively, from the prior year.
Investors should also note any recent changes to analyst estimates for WY. These revisions typically reflect the latest short-term business trends, which can change frequently. With this in mind, we can consider positive estimate revisions a sign of optimism about the company’s business outlook.
Research indicates that these estimate revisions are directly correlated with near-term share price momentum. To benefit from this, we have developed the Zacks Rank, a proprietary model which takes these estimate changes into account and provides an actionable rating system.
Ranging from #1 (Strong Buy) to #5 (Strong Sell), the Zacks Rank system has a proven, outside-audited track record of outperformance, with #1 stocks returning an average of +25% annually since 1988. The Zacks Consensus EPS estimate has moved 5.04% lower within the past month. WY is currently sporting a Zacks Rank of #3 (Hold).
Investors should also note WY’s current valuation metrics, including its Forward P/E ratio of 11.18. This valuation marks a discount compared to its industry’s average Forward P/E of 12.57.
The Building Products – Wood industry is part of the Construction sector. This industry currently has a Zacks Industry Rank of 100, which puts it in the top 40% of all 250+ industries.
The Zacks Industry Rank gauges the strength of our individual industry groups by measuring the average Zacks Rank of the individual stocks within the groups. Our research shows that the top 50% rated industries outperform the bottom half by a factor of 2 to 1.
To follow WY in the coming trading sessions, be sure to utilize Zacks.com.
5 Stocks Set to Double
Each was handpicked by a Zacks expert as the #1 favorite stock to gain +100% or more in 2021. Previous recommendations have soared +143.0%, +175.9%, +498.3% and +673.0%.
Most of the stocks in this report are flying under Wall Street radar, which provides a great opportunity to get in on the ground floor.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
UnitedHealth Group (UNH) Dips More Than Broader Markets: What You Should Know
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
UnitedHealth Group (UNH) closed the most recent trading day at $387.01, moving -1.38% from the previous trading session. This change lagged the S&P 500’s daily loss of 1.3%.
– Zacks
Prior to today’s trading, shares of the largest U.S. health insurer had lost 7.2% over the past month. This has lagged the Medical sector’s loss of 6.02% and the S&P 500’s loss of 3.58% in that time.
Investors will be hoping for strength from UNH as it approaches its next earnings release, which is expected to be October 14, 2021. In that report, analysts expect UNH to post earnings of $4.41 per share. This would mark year-over-year growth of 25.64%. Our most recent consensus estimate is calling for quarterly revenue of $71.5 billion, up 9.8% from the year-ago period.
For the full year, our Zacks Consensus Estimates are projecting earnings of $18.74 per share and revenue of $285.28 billion, which would represent changes of +11.02% and +10.94%, respectively, from the prior year.
It is also important to note the recent changes to analyst estimates for UNH. These revisions help to show the ever-changing nature of near-term business trends. As a result, we can interpret positive estimate revisions as a good sign for the company’s business outlook.
Based on our research, we believe these estimate revisions are directly related to near-team stock moves. To benefit from this, we have developed the Zacks Rank, a proprietary model which takes these estimate changes into account and provides an actionable rating system.
The Zacks Rank system ranges from #1 (Strong Buy) to #5 (Strong Sell). It has a remarkable, outside-audited track record of success, with #1 stocks delivering an average annual return of +25% since 1988. The Zacks Consensus EPS estimate has moved 0.09% higher within the past month. UNH is currently sporting a Zacks Rank of #2 (Buy).
Looking at its valuation, UNH is holding a Forward P/E ratio of 20.94. Its industry sports an average Forward P/E of 18.21, so we one might conclude that UNH is trading at a premium comparatively.
Investors should also note that UNH has a PEG ratio of 1.58 right now. This popular metric is similar to the widely-known P/E ratio, with the difference being that the PEG ratio also takes into account the company’s expected earnings growth rate. Medical – HMOs stocks are, on average, holding a PEG ratio of 1.14 based on yesterday’s closing prices.
The Medical – HMOs industry is part of the Medical sector. This industry currently has a Zacks Industry Rank of 113, which puts it in the top 45% of all 250+ industries.
The Zacks Industry Rank includes is listed in order from best to worst in terms of the average Zacks Rank of the individual companies within each of these sectors. Our research shows that the top 50% rated industries outperform the bottom half by a factor of 2 to 1.
Make sure to utilize Zacks. Com to follow all of these stock-moving metrics, and more, in the coming trading sessions.
5 Stocks Set to Double
Each was handpicked by a Zacks expert as the #1 favorite stock to gain +100% or more in 2021. Previous recommendations have soared +143.0%, +175.9%, +498.3% and +673.0%.
Most of the stocks in this report are flying under Wall Street radar, which provides a great opportunity to get in on the ground floor.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Procter & Gamble (PG) Stock Moves -0.57%: What You Should Know
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
In the latest trading session, Procter & Gamble (PG) closed at $138.79, marking a -0.57% move from the previous day. This move was narrower than the S&P 500’s daily loss of 1.3%.
– Zacks
Coming into today, shares of the world’s largest consumer products maker had lost 3.1% in the past month. In that same time, the Consumer Staples sector lost 4.57%, while the S&P 500 lost 3.58%.
Investors will be hoping for strength from PG as it approaches its next earnings release, which is expected to be October 19, 2021. The company is expected to report EPS of $1.58, down 3.07% from the prior-year quarter. Meanwhile, our latest consensus estimate is calling for revenue of $19.79 billion, up 2.47% from the prior-year quarter.
PG’s full-year Zacks Consensus Estimates are calling for earnings of $5.94 per share and revenue of $78.97 billion. These results would represent year-over-year changes of +4.95% and +3.74%, respectively.
Any recent changes to analyst estimates for PG should also be noted by investors. These revisions typically reflect the latest short-term business trends, which can change frequently. As such, positive estimate revisions reflect analyst optimism about the company’s business and profitability.
Our research shows that these estimate changes are directly correlated with near-term stock prices. To benefit from this, we have developed the Zacks Rank, a proprietary model which takes these estimate changes into account and provides an actionable rating system.
The Zacks Rank system, which ranges from #1 (Strong Buy) to #5 (Strong Sell), has an impressive outside-audited track record of outperformance, with #1 stocks generating an average annual return of +25% since 1988. The Zacks Consensus EPS estimate has moved 0.07% higher within the past month. PG is currently a Zacks Rank #3 (Hold).
Digging into valuation, PG currently has a Forward P/E ratio of 23.51. Its industry sports an average Forward P/E of 23.46, so we one might conclude that PG is trading at a premium comparatively.
Also, we should mention that PG has a PEG ratio of 3.36. This popular metric is similar to the widely-known P/E ratio, with the difference being that the PEG ratio also takes into account the company’s expected earnings growth rate. PG’s industry had an average PEG ratio of 3.91 as of yesterday’s close.
The Soap and Cleaning Materials industry is part of the Consumer Staples sector. This industry currently has a Zacks Industry Rank of 246, which puts it in the bottom 4% of all 250+ industries.
The Zacks Industry Rank gauges the strength of our individual industry groups by measuring the average Zacks Rank of the individual stocks within the groups. Our research shows that the top 50% rated industries outperform the bottom half by a factor of 2 to 1.
To follow PG in the coming trading sessions, be sure to utilize Zacks.com.
5 Stocks Set to Double
Each was handpicked by a Zacks expert as the #1 favorite stock to gain +100% or more in 2021. Previous recommendations have soared +143.0%, +175.9%, +498.3% and +673.0%.
Most of the stocks in this report are flying under Wall Street radar, which provides a great opportunity to get in on the ground floor.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Strength Seen in Gogo (GOGO): Can Its 7.3% Jump Turn into More Strength?
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
Gogo (GOGO) shares rallied 7.3% in the last trading session to close at $18.57. This move can be attributable to notable volume with a higher number of shares being traded than in a typical session. This compares to the stock’s 26.7% gain over the past four weeks.
– Zacks
GOGO’s stock rallied after it hiked its long-term financial targets. Per the revised guidance, revenues are expected to rise, witnessing a compounded annual growth rate of 15% between 2020 and 2025 compared with the previously mentioned 10%. The annual adjusted EBITDA margin is estimated to grow from 40% in 2021 to 45% in 2025 versus the earlier stated 35-40%. Owing to the deployment of the Gogo 5G network in 2022, the free cash flow is anticipated to be $125 million and $200 million for 2023 and 2025, respectively, compared with the previous target of more than $100 million in 2023. Further, higher equipment sales on the back of solid demand for in-flight connectivity solutions coupled with booming private air travel are expected to drive its long-term margins. Based on these trends, we believe that the stock has more upside left.
This in-flight internet provider is expected to post quarterly loss of $0.05 per share in its upcoming report, which represents a year-over-year change of +54.6%. Revenues are expected to be $84.21 million, up 26.6% from the year-ago quarter.
Earnings and revenue growth expectations certainly give a good sense of the potential strength in a stock, but empirical research shows that trends in earnings estimate revisions are strongly correlated with near-term stock price movements.
For Gogo, the consensus EPS estimate for the quarter has been revised 1.6% lower over the last 30 days to the current level. And a negative trend in earnings estimate revisions doesn’t usually translate into price appreciation. So, make sure to keep an eye on GOGO going forward to see if this recent jump can turn into more strength down the road.
Each was handpicked by a Zacks expert as the #1 favorite stock to gain +100% or more in 2021. Previous recommendations have soared +143.0%, +175.9%, +498.3% and +673.0%.
Most of the stocks in this report are flying under Wall Street radar, which provides a great opportunity to get in on the ground floor.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
5 Penny Stocks To Watch This Week With Potential Biotech Catalysts
The last few weeks have started the same, and that’s with a list of penny stocks with potential catalysts. One of the exciting things about specific industries like biotech is that companies tend to pre-announce a date that news will come out in the future. Whether it’s something like a Prescription Drug User Fee Act (PDUFA) date with the FDA or new data readouts, there are many things to monitor. In most cases, biotech companies will give the public the timing of things like these.
PennyStocks.com – PennyStocks
The important part is deciding if upcoming events are potential bullish or bearish catalysts. As I’m sure many of you already know, biotech is a fickle area of the market. Companies can come out with positive data, but if one thing’s missed or came up short of expectations, a would-be optimistic report can become the reason penny stocks sell off. Last week we discussed 10 Top Penny Stocks To Watch With Potential Biotech Catalysts. Of those stocks discussed, some climbed to new September highs while others fell short. But the more you know, the better prepared you’ll be for what could be in store.
In this article, we’ll look at 5 penny stocks to watch this week with potential catalysts. Some have given specific dates, while others have shown a timeframe. After you get the lay of the land, then you can decide for yourself if they’re the best penny stocks to buy this week or if you should avoid them entirely.
The first name on this list of penny stocks to watch this week is Arbutus. We’ve discussed the company plenty of times. If you’re not familiar, however, let’s get you up to speed. Arbutus focuses on treatments for chronic infections, including hepatitis B, and new therapies for treating coronaviruses. A fair amount of attention has been on Arbutus versus Moderna, believe it or not. The two conflicted over Arbutus’s lipid formulations for nucleic acid delivery.
Last month, the European Patent Office said that its 069 patent related to lipid formulations was “Inventive” (valid). This was in line with the US Patent and Trademark Office’s response after it granted a notice of allowance in September. Moderna is moving forward with an appeal set for a hearing this month. However, if Arbutus is correct, it could open the doors for eligibility to receive royalties from Moderna’s COVID-19 vaccine sales.
What To Watch With ABUS Stock This Week
This week there are a few things to follow with Arbutus. The first comes on October 5th. The company presents at its first of 2 planned conferences. Arbutus will participate in a fireside chat at the Chardan Genetic Medicines Conference starting at 4:30 PM ET.
Later on this week, things could also put ABUS stock in focus. On October 7, the United States Court Of Appeals For The Federal Circuit will hear arguments from Arbutus and Moderna. So if ABUS stock or MRNA, for that matter, is on your list this week, keep this date in mind.
Kaleido Biosciences Inc.
Another one of the penny stocks to watch with events this week is Kaleido Biosciences. The company isn’t overly active in the stock market. However, around specific events, KLDO stock has experienced some volatility. Looking back at this summer, you’ll see a spike in June. This came just a few days after Kaleido’s presentation at the JMP Securities Life Sciences Conference. Whether or not the Conference was the official catalysts is to be seen. Fast-forward, and you’ll also see spikes when the company presented at other conferences this year, including the most recent in September at the Morgan Stanely Global Healthcare Conference.
The core point of focus with Kaleido has been on its Microbiome Metabolic Therapies (MMT) platform. Its KB295 treatment is also something traders have followed. It’s being studied in patients with mild-to-moderate ulcerative colitis. Meanwhile, the other side of Kaleido has put an emphasis on Long-Hauler COVID patients. The company’s KB109 is under evaluation for COVID-19.
What To Watch With KLDO Stock This Week
This week, the market could get a bit more clarity on where all of Kaleido’s treatments stand. On October 5, the company hosts an R&D presentation to discuss clinical data and pipeline advancement. The agenda includes corporate strategy, data from its non-IND study evaluating KB295, and preclinical data supporting the advancement of KB109 in COPD patients.
MannKind Corporation
There are other companies like MannKind, which have previously announced pending updates. However, with this company, it didn’t give specific dates but only said October would be a month to keep in mind.
MannKind specializes in therapeutic products that patients inhale. Indications include endocrine and orphan lung diseases. Afrezza® Inhalation Powder is the company’s first FDA-approved product and the only inhaled ultra rapid-acting mealtime insulin in the United States. MannKind is also preparing to manufacture Tyvaso DPI™ under a collaboration with United Therapeutics. Tyvaso DPI is under FDA review to treat pulmonary arterial hypertension (PAH) and pulmonary hypertension associated with interstitial lung disease (PH-ILD).
What To Watch With MNKD Stock This Week
This week and this month could be important for MannKind. First, on October 5, the company participates at the Lytham Partners Fall Investor Conference. CEO Michael Castagna, PharmD, will discuss different facets of the company.
In addition, while a specific date wasn’t given, a September update discussed that FDA action on a New Drug Application (NDA) for Tyvaso DPI is expected this month. This comes after United Therapeutics submitted an NDA to the FDA seeking approval of Tyvaso DPI for treating adult patients with PAH and PH-ILD.
Penny Stocks To Watch On October 9:
Adverum Biotechnologies Inc.
Last week Adverum kicked off its month of industry presentations at the Retina Society Scientific Meeting on October 1. Considering that the presentation didn’t begin under 4 PM ET, there may be more details to digest heading into the start of the new week. What’s more, Adverum will present at two more conferences this month, the second of which comes this week. The company offers data from its Phase 2 INFINITY Trial using ADVM-022 in diabetic macular edema.
The company has been in and out of the spotlight over the last few months as it advances its gene therapy candidate. There’s also a plan to complete data analysis by year-end to develop a protocol and seek investigator and regulatory feedback on a Phase 2 clinical trial in wet AMD.
What To Watch With ADVM Stock This Week
This week, October 9th, will be the date to focus on. This is when the company delivers its Phase 2 Data on ADVM-022. Following this presentation, Adverum will also give results from its Phase 1 OPTIC Trial in neovascular AMD treated with ADVM-022. These won’t come until early next week at the ASRS Scientific Meeting (which we’ll update next week).
Trevena Inc.
Trevena is another one of the penny stocks that’ve been in focus, thanks to COVID-19. Last week the company announced the results of its TRV027 proof-of-concept study in patients with the virus. Details showed a 92% probability that TRV027 has a potential beneficial impact on the primary endpoint of D-dimer levels. This is a biomarker associated with critical illness and mortality. The company also reported that treated patients had 12 days lower average hospital length of stay compared to placebo.
Other than TRV027, Trevena develops treatments for central nervous system disorders. This includes one approved product in the United States, OLINVYK® (oliceridine) injection. This is indicated in adults for acute pain management severe enough to require an intravenous opioid analgesic and for whom alternative treatments are inadequate.
What To Watch With TRVN Stock This Week
This week, Trevena’s OLINVYK® will be a point of focus. Earlier in the year, two abstracts were accepted at ANESTHESIOLOGY® 2021. Both abstracts highlight safety data from the OLINVYK (oliceridine) injection program. The meeting is sponsored by the American Society of Anesthesiologists and will be shown on October 9th.
Penny Stocks To Watch This Week
There’s a lot to watch this week. Biotech penny stocks are part of that, and it’s essential to understand that companies with upcoming events aren’t “sure things” to see a move (up or down). However, at the very least, there could be some new information to factor in if any of these are on your list of penny stocks. Will that be the case this week?
https://www.entrepreneur.com/article/389009
Snap (SNAP) Outpaces Stock Market Gains: What You Should Know
You’re reading Entrepreneur United States, an international franchise of Entrepreneur Media. This story originally appeared on Zacks
In the latest trading session, Snap (SNAP) closed at $75.25, marking a +1.87% move from the previous day. The stock outpaced the S&P 500’s daily gain of 1.15%.
– Zacks
Coming into today, shares of the company behind Snapchat had lost 0.07% in the past month. In that same time, the Computer and Technology sector lost 6.41%, while the S&P 500 lost 4.67%.
Investors will be hoping for strength from SNAP as it approaches its next earnings release. The company is expected to report EPS of -$0.01, down 200% from the prior-year quarter. Meanwhile, our latest consensus estimate is calling for revenue of $1.09 billion, up 59.98% from the prior-year quarter.
Looking at the full year, our Zacks Consensus Estimates suggest analysts are expecting earnings of $0.34 per share and revenue of $4.21 billion. These totals would mark changes of +666.67% and +67.96%, respectively, from last year.
It is also important to note the recent changes to analyst estimates for SNAP. These recent revisions tend to reflect the evolving nature of short-term business trends. As a result, we can interpret positive estimate revisions as a good sign for the company’s business outlook.
Our research shows that these estimate changes are directly correlated with near-term stock prices. We developed the Zacks Rank to capitalize on this phenomenon. Our system takes these estimate changes into account and delivers a clear, actionable rating model.
The Zacks Rank system ranges from #1 (Strong Buy) to #5 (Strong Sell). It has a remarkable, outside-audited track record of success, with #1 stocks delivering an average annual return of +25% since 1988. The Zacks Consensus EPS estimate remained stagnant within the past month. SNAP is currently sporting a Zacks Rank of #3 (Hold).
In terms of valuation, SNAP is currently trading at a Forward P/E ratio of 217.26. For comparison, its industry has an average Forward P/E of 55.56, which means SNAP is trading at a premium to the group.
The Internet – Software industry is part of the Computer and Technology sector. This industry currently has a Zacks Industry Rank of 199, which puts it in the bottom 22% of all 250+ industries.
The Zacks Industry Rank gauges the strength of our individual industry groups by measuring the average Zacks Rank of the individual stocks within the groups. Our research shows that the top 50% rated industries outperform the bottom half by a factor of 2 to 1.
Make sure to utilize Zacks. Com to follow all of these stock-moving metrics, and more, in the coming trading sessions.
Zacks Names “Single Best Pick to Double”
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
You know this company from its past glory days, but few would expect that it’s poised for a monster turnaround. Fresh from a successful repositioning and flush with A-list celeb endorsements, it could rival or surpass other recent Zacks’ Stocks Set to Double like Boston Beer Company which shot up +143.0% in a little more than 9 months and Nvidia which boomed +175.9% in one year.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report

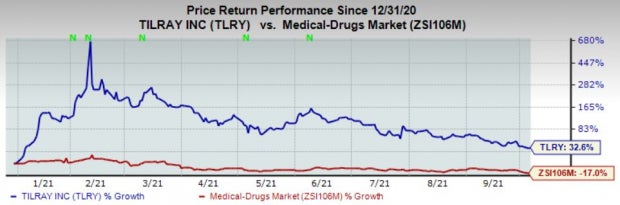 Image Source: Zacks Investment Research